



 Chat with AI
Exam 17: Business Strategy and Oligopoly

Exam 1: Ten Lessons From Economics146 Questions
Exam 2: Thinking Like an Economist133 Questions
Exam 3: Interdependence and the Gains From Trade139 Questions
Exam 4: The Market Forces of Supply and Demand215 Questions
Exam 5: Elasticity and Its Application178 Questions
Exam 6: Supply, Demand and Government Policies145 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets171 Questions
Exam 8: Application: the Costs of Taxation135 Questions
Exam 9: Application: International Trade151 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources178 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets198 Questions
Exam 15: Monopoly212 Questions
Exam 16: Monopolistic Competition212 Questions
Exam 17: Business Strategy and Oligopoly179 Questions
Exam 18: Competition Policy103 Questions
Exam 19: The Markets for the Factors of Production214 Questions
Exam 20: Earnings, Unions and Discrimination201 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice158 Questions
Exam 23: Frontiers of Microeconomics111 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living55 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment58 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy61 Questions
Exam 33: Aggregate Demand and Aggregate Supply81 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment57 Questions
Exam 36: Global Financial Crisis of 2008 and Beyond37 Questions
Exam 37: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


When oligopolists cooperate, they end up producing a total quantity that is closer to the social optimum.
(True/False)
4.9/5  (79)
(79) Table 16-5
Consider the following Duopoly game. Firm B U D Firm A U Firm A gets \1 40 Firm A get \2 20 Firm B gets \8 0 Firm B gets \1 60 D Firm A gets \1 60 Firm A gets \8 0 Firm B gets \2 20 Firm B gets \1 00
-Refer to Table 16-5.If both firms follow a dominant strategy, firm B's profits (losses) will be:
(Multiple Choice)
4.8/5 (75)
(75) During the 1990s, the members of OPEC operated independently from one another, causing the world market for crude oil to become close to a(n):
(Multiple Choice)
4.7/5 (75)
(75) The paradoxical nature of the oligopoly game can be described by the fact that even though the monopoly outcome is best for all the oligopolists:
(Multiple Choice)
4.9/5 (65)
(65) An agreement among firms over production and price is called:
(Multiple Choice)
4.9/5 (77)
(77) If duopolists can enforce an agreement, to produce collectively the monopoly output and split the market between the two firms, then the sum of their output will be:
(Multiple Choice)
4.9/5 (65)
(65) Two suspected drug dealers are stopped by the highway patrol for speeding.The officer searches the car and finds a small bag of marijuana, and arrests the two.During the interrogation, each is separately made the following offer: 'If you confess to dealing drugs and testify against your partner, you will be given immunity and released while your partner will get 10 years in prison.If you both confess, you will each get five years'.If neither confesses, there is no evidence of drug dealing, and the most they could get is one year each for possession of marijuana.If each suspected drug dealer follows a dominant strategy, what should they do?
(Multiple Choice)
4.9/5 (85)
(85) Raising production will increase total units sold, which will decrease the per unit price of all units sold.This concept is known as the:
(Multiple Choice)
4.9/5 (89)
(89) Table 16-8
Consider two countries, Eudora and the Inhabit, that are engaged in an arms race.The question each country must face is whether to build new weapons or to disarm existing weapons.Each country prefers to have more arms than the other because a large arsenal gives it more influence in world affairs.But each country also prefers to live in a world safe from the other country's weapons.The table shows the possible outcomes for each decision combination. 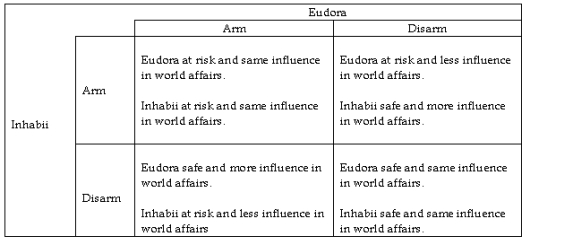 -Refer to Table 16-8.For each country, arming is what type of strategy?
 (Multiple Choice)
4.8/5 (89)
(89) When an oligopoly market is in Nash equilibrium, firms will not act as profit maximisers.
(True/False)
4.9/5 (92)
(92) Table 16-2
In the following duopoly game, the two firms can either set the price of their product high or low.The game is represented in the table below. Firm B High Price Low Price Firm A High Price Firm A gets \1 000 Firm A get \1 250 Firm B gets \1 000 Firm B gets \1 100 Low Price Firm A gets \8 00 Firm A gets \9 00 Firm B gets \8 00 Firm B gets \9 00
-Refer to Table 16-2.What is the profit firm B will earn if it plays its dominant strategy:
(Multiple Choice)
4.9/5 (64)
(64) Larger cartels have a greater probability of reaching the monopoly outcome than do smaller cartels.
(True/False)
4.9/5 (84)
(84) An important characteristic of a dominant strategy is that:
(Multiple Choice)
4.9/5 (83)
(83) Firms in industries that have competitors but, at the same time, do not face so much competition that they are price takers, are operating in either a(n):
(Multiple Choice)
4.9/5 (79)
(79) If an oligopolist is part of a cartel that is collectively producing at the monopoly level of output, then the oligopolist, being self-interested, will:
(Multiple Choice)
4.8/5 (89)
(89) An important characteristic of an oligopoly market structure is that:
(Multiple Choice)
4.8/5 (81)
(81) Table 16-3
Imagine a small town in which only two residents, Robert and John, own wells that produce water for safe drinking.Each Saturday, Robert and John work together to decide how many litres of water to pump, bring the water to town, and sell it at whatever price the market will bear.To keep things simple, suppose that Robert and John can pump as much water as they want without cost; therefore, the marginal cost of water equals zero.The weekly town demand schedule and total revenue schedule for water are shown in the table.
-Refer to Table 16-3.Suppose the town enacts new anti-trust laws that prohibit Robert and John from operating as a monopolist.What will the new price of water end up being once the Nash equilibrium is reached?
(Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)