



 Chat with AI
Exam 12: Perfect Competition and the Supply Curve

Exam 1: First Principles233 Questions
Exam 2: Economic Models: Trade-Offs and Trade 25382 Questions
Exam 3: Supply and Demand290 Questions
Exam 4: Consumer and Producer Surplus224 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets227 Questions
Exam 6: Elasticity300 Questions
Exam 7: Taxes298 Questions
Exam 8: International Trade272 Questions
Exam 9: Decision Making by Individuals Firms201 Questions
Exam 10: The Rational Consumer372 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs362 Questions
Exam 12: Perfect Competition and the Supply Curve355 Questions
Exam 13: Monopoly350 Questions
Exam 14: Oligopoly294 Questions
Exam 15: Monopolistic Competition and Product Differentiation262 Questions
Exam 16: Externalities199 Questions
Exam 17: Public Goods Common Resources224 Questions
Exam 18: The Economics of the Welfare140 Questions
Exam 19: Factor Markets and the Distribution of Income369 Questions
Exam 20: Uncertainty, Risk, and Private Information202 Questions
Select questions type


The profit-maximizing level of output for a perfectly competitive firm in the short run occurs where _____ equals _____.
(Multiple Choice)
4.9/5  (81)
(81) Use the following to answer questions: 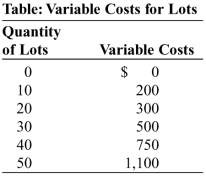 -(Table: Variable Costs for Lots) Look at the table Variable Costs for Lots. During the winter, Alexa runs a snow-clearing service in a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of clearing anywhere from 1 through 10 lots is $200. Her only fixed cost is $1,000 for a snowplow. Her variable costs include fuel, her time, and hot coffee. What is Alexa's shut-down price in the short run?
 (Multiple Choice)
4.8/5 (72)
(72) Use the following to answer questions: 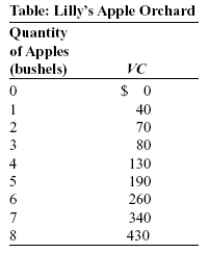 -(Table: Lilly's Apple Orchard) Look at the table Lilly's Apple Orchard. Lilly is the price-taking owner of an apple orchard. Her orchard has fixed costs of $30. If the price of a bushel of apples is $35, her economic profit will be:
 (Multiple Choice)
4.8/5 (80)
(80) Use the following to answer questions: 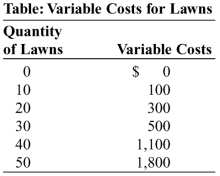 -(Table: Variable Costs for Lawns) Look at the table Variable Costs for Lawns. During the summer, Alex runs a lawn-mowing service, and lawn-mowing is a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of mowing 1 through 10 lawns is $100. His only fixed cost is $1,000 for the mower. His variable costs include fuel, his time, and mower parts. If the price for mowing a lawn is $40, how much is Alex's profit per unit at the profit-maximizing output?
 (Multiple Choice)
4.8/5 (66)
(66) In the long run, when there are economic losses, firms leave the industry, which will decrease the market supply and increase price until economic losses are zero.
(True/False)
5.0/5 (85)
(85) Use the following to answer questions:
Figure: Revenues, Costs, and Profits for Tomato Producers III 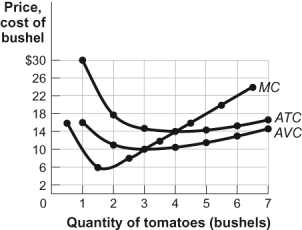 -(Figure: Revenues, Costs, and Profits for Tomato Producers III) Look at the figure Revenues, Costs, and Profits for Tomato Producers III. The market for tomatoes is perfectly competitive. The farm's short-run supply curve is the _____ cost curve above a price of _____.
 (Multiple Choice)
4.8/5 (77)
(77) A perfectly competitive firm's supply curve is its marginal cost curve above the average variable cost curve.
(True/False)
4.9/5 (84)
(84) The price received by a firm in a perfectly competitive market:
(Multiple Choice)
4.7/5 (76)
(76) A firm's total output times the price at which it sells that output is _____ revenue.
(Multiple Choice)
4.9/5 (76)
(76) In the short run, a perfectly competitive firm produces output and incurs an economic loss if:
(Multiple Choice)
4.9/5 (80)
(80) In long-run equilibrium in a perfectly competitive market, all firms will be operating at the same level of marginal cost.
(True/False)
4.8/5 (87)
(87) Use the following to answer questions:
-(Table: Variable Costs for Lawns) Look at the table Variable Costs for Lawns. During the summer, Alex runs a lawn-mowing service, and lawn-mowing is a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of mowing 1 through 10 lawns is $100. His only fixed cost is $1,000 for the mower. His variable costs include fuel, his time, and mower parts. If the price for mowing a lawn is $60, how much is Alex's total cost at the profit-maximizing output?
-(Table: Variable Costs for Lawns) Look at the table Variable Costs for Lawns. During the summer, Alex runs a lawn-mowing service, and lawn-mowing is a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of mowing 1 through 10 lawns is $100. His only fixed cost is $1,000 for the mower. His variable costs include fuel, his time, and mower parts. If the price for mowing a lawn is $60, how much is Alex's total cost at the profit-maximizing output? (Multiple Choice)
4.8/5 (75)
(75) Assume that in the short run a perfectly competitive firm does not produce output and has economic losses. This occurs at the quantity where MR = MC and:
(Multiple Choice)
4.9/5 (95)
(95) If a perfectly competitive firm is producing a quantity where P < MC, then profit:
(Multiple Choice)
4.8/5 (79)
(79) Use the following to answer questions:
-(Table: Variable Costs for Lawns) Look at the table Variable Costs for Lawns. During the summer, Alex runs a lawn-mowing service, and lawn-mowing is a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of mowing 1 through 10 lawns is $100. His only fixed cost is $1,000 for the mower. His variable costs include fuel, his time, and mower parts. If the price for mowing a lawn is $60, how much is Alex's profit per unit at the profit-maximizing output?
-(Table: Variable Costs for Lawns) Look at the table Variable Costs for Lawns. During the summer, Alex runs a lawn-mowing service, and lawn-mowing is a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of mowing 1 through 10 lawns is $100. His only fixed cost is $1,000 for the mower. His variable costs include fuel, his time, and mower parts. If the price for mowing a lawn is $60, how much is Alex's profit per unit at the profit-maximizing output? (Multiple Choice)
4.9/5 (86)
(86) Use the following to answer questions:
Figure: The Perfectly Competitive Firm 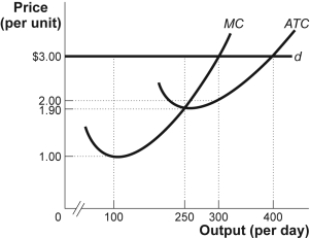 -(Figure: Perfectly Competitive Firm) Look at the figure The Perfectly Competitive Firm. The figure shows a perfectly competitive firm that faces demand curve d and maximizes profit. If the firm faces a market price of $3, its total profit per day is:
 (Multiple Choice)
4.9/5 (76)
(76) Use the following to answer questions: 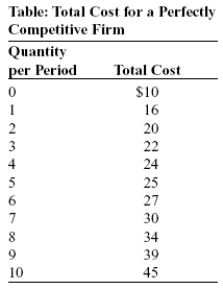 -(Table: Total Cost for a Perfectly Competitive Firm) Look at the table Total Cost for a Perfectly Competitive Firm. If the market price is $5.50, the profit-maximizing quantity of output is _____ units.
 (Multiple Choice)
4.9/5 (71)
(71) Use the following to answer questions:
Figure: Revenues, Costs, and Profits for Tomato Producers III
-(Figure: Revenues, Costs, and Profits for Tomato Producers III) Look at the figure Revenues, Costs, and Profits for Tomato Producers III. The market for tomatoes is perfectly competitive. If the market price of a bushel of tomatoes is $8, in the short run the farmer's profit-maximizing output is _____ bushels.
-(Figure: Revenues, Costs, and Profits for Tomato Producers III) Look at the figure Revenues, Costs, and Profits for Tomato Producers III. The market for tomatoes is perfectly competitive. If the market price of a bushel of tomatoes is $8, in the short run the farmer's profit-maximizing output is _____ bushels. (Multiple Choice)
5.0/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)