



 Chat with AI
Exam 12: Perfect Competition and the Supply Curve

Exam 1: First Principles233 Questions
Exam 2: Economic Models: Trade-Offs and Trade 25382 Questions
Exam 3: Supply and Demand290 Questions
Exam 4: Consumer and Producer Surplus224 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets227 Questions
Exam 6: Elasticity300 Questions
Exam 7: Taxes298 Questions
Exam 8: International Trade272 Questions
Exam 9: Decision Making by Individuals Firms201 Questions
Exam 10: The Rational Consumer372 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs362 Questions
Exam 12: Perfect Competition and the Supply Curve355 Questions
Exam 13: Monopoly350 Questions
Exam 14: Oligopoly294 Questions
Exam 15: Monopolistic Competition and Product Differentiation262 Questions
Exam 16: Externalities199 Questions
Exam 17: Public Goods Common Resources224 Questions
Exam 18: The Economics of the Welfare140 Questions
Exam 19: Factor Markets and the Distribution of Income369 Questions
Exam 20: Uncertainty, Risk, and Private Information202 Questions
Select questions type


Use the following to answer questions: 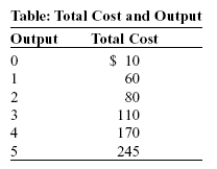 -(Table: Total Cost and Output) Look at the table Total Cost and Output, which describes Sergei's total costs for his perfectly competitive all-natural ice cream firm. If the market price of a tub of ice cream is $67.50, how much is Sergei's total revenue at the profit-maximizing output?
 (Multiple Choice)
4.9/5  (93)
(93) Use the following to answer questions:
Figure: The Profit-Maximizing Firm in the Short Run 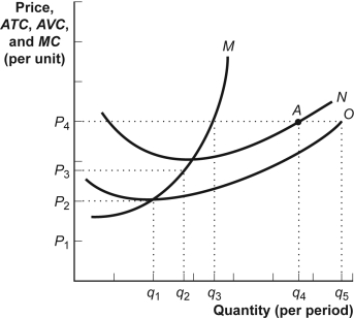 -(Figure: The Profit-Maximizing Firm in the Short Run) Look at the figure The Profit-Maximizing Firm in the Short Run. The ATC curve is represented by:
 (Multiple Choice)
4.8/5 (69)
(69) Use the following to answer questions:
Figure: Short-Run Costs 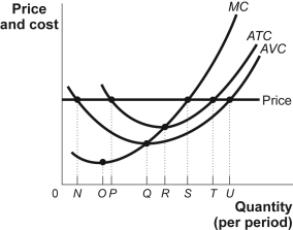 -(Figure: Short-Run Costs) Look at the figure Short-Run Costs. This firm's short-run supply curve begins at quantity:
 (Multiple Choice)
4.9/5 (61)
(61) Use the following to answer questions:
Figure: The Marginal Decision Rule 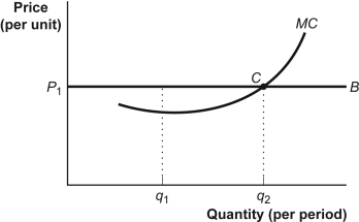 -(Figure: Marginal Decision Rule) Look at the figure The Marginal Decision Rule. As long as the price is above the minimum variable cost, this firm should produce quantity _____ where _____ equals _____ to maximize economic profit.
 (Multiple Choice)
4.8/5 (79)
(79) Use the following to answer questions: 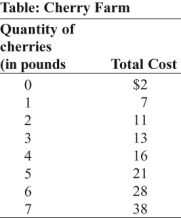 -(Table: Cherry Farm) Look at the table Cherry Farm. If Hank and Helen have one of 100 farms in the perfectly competitive cherry industry and if the price is $4, in the short run the industry will supply _____ pounds.
 (Multiple Choice)
4.8/5 (85)
(85) Use the following to answer questions: 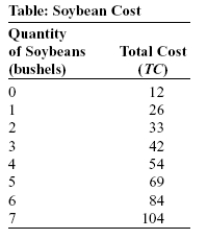 -(Table: Soybean Cost) Look at the table Soybean Cost. If the market price of a bushel of soybeans is $15, what will be the farmer's short-run maximum profit?
 (Multiple Choice)
4.8/5 (79)
(79) Use the following to answer questions:
Figure: The Profit-Maximizing Firm in the Short Run
-(Figure: The Profit-Maximizing Firm in the Short Run) Look at the figure The Profit-Maximizing Firm. O is the _____ curve.
-(Figure: The Profit-Maximizing Firm in the Short Run) Look at the figure The Profit-Maximizing Firm. O is the _____ curve. (Multiple Choice)
4.9/5 (66)
(66) In perfectly competitive markets, if the price is _____, the firm will _____.
(Multiple Choice)
5.0/5 (75)
(75) Ashley, who makes knitted caps, determines that her marginal cost of knitting one more cap is $10. A consumer offers her $12 for one more knitted cap. Ashley will:
(Multiple Choice)
4.9/5 (78)
(78) Lilly is the price-taking owner of an apple orchard. The price of apples is high enough that Lilly is earning positive economic profits. In the long run, Lilly should expect _____ apple prices due to the _____ firms.
(Multiple Choice)
4.7/5 (72)
(72) Provided that there are no external benefits or costs, resources are efficiently allocated when:
(Multiple Choice)
4.8/5 (65)
(65) A perfectly competitive firm will not produce any output in the short run and will shut down if the price is:
(Multiple Choice)
4.8/5 (80)
(80) Consider a perfectly competitive corn industry that has positive economic profit. Describe how the long-run industry supply curve might slope upward rather than be horizontal.
(Essay)
4.7/5 (68)
(68) Use the following to answer questions: 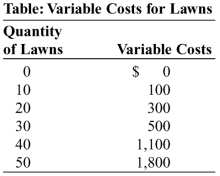 -(Table: Variable Costs for Lawns) Look at the table Variable Costs for Lawns. During the summer, Alex runs a lawn-mowing service, and lawn-mowing is a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of mowing 1 through 10 lawns is $100. His only fixed cost is $1,000 for the mower. His variable costs include fuel, his time, and mower parts. If the price for mowing a lawn is $70, how much is Alex's profit at the profit-maximizing output?
 (Multiple Choice)
4.8/5 (87)
(87) If a perfectly competitive gardening shop sells 30 evergreen bushes at $10 per bush, its marginal revenue is:
(Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)