



 Chat with AI
Exam 12: Perfect Competition and the Supply Curve

Exam 1: First Principles233 Questions
Exam 2: Economic Models: Trade-Offs and Trade 25382 Questions
Exam 3: Supply and Demand290 Questions
Exam 4: Consumer and Producer Surplus224 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets227 Questions
Exam 6: Elasticity300 Questions
Exam 7: Taxes298 Questions
Exam 8: International Trade272 Questions
Exam 9: Decision Making by Individuals Firms201 Questions
Exam 10: The Rational Consumer372 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs362 Questions
Exam 12: Perfect Competition and the Supply Curve355 Questions
Exam 13: Monopoly350 Questions
Exam 14: Oligopoly294 Questions
Exam 15: Monopolistic Competition and Product Differentiation262 Questions
Exam 16: Externalities199 Questions
Exam 17: Public Goods Common Resources224 Questions
Exam 18: The Economics of the Welfare140 Questions
Exam 19: Factor Markets and the Distribution of Income369 Questions
Exam 20: Uncertainty, Risk, and Private Information202 Questions
Select questions type


Zoe's Bakery operates in a perfectly competitive industry. When the market price of iced cupcakes is $5, the profit-maximizing output level is 150 cupcakes. Her average total cost is $4, and her average variable cost is $3. Zoe's marginal cost is _____, and her short-run profits are _____.
(Multiple Choice)
4.8/5  (83)
(83) Use the following to answer questions: 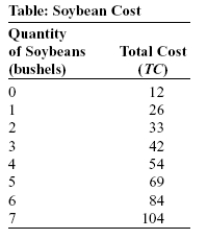 -(Table: Soybean Cost) Look at the table Soybean Cost. What is the shut-down price for this farmer?
 (Multiple Choice)
4.9/5 (83)
(83) If the long-run market supply curve for a perfectly competitive market is horizontal, then this industry exhibits _____ costs.
(Multiple Choice)
4.8/5 (72)
(72) In the short run, for a perfectly competitive firm, the portion of the MC curve at or above the shut-down price is also its:
(Multiple Choice)
4.9/5 (79)
(79) Use the following to answer questions:
Figure: Game-Day Shirts 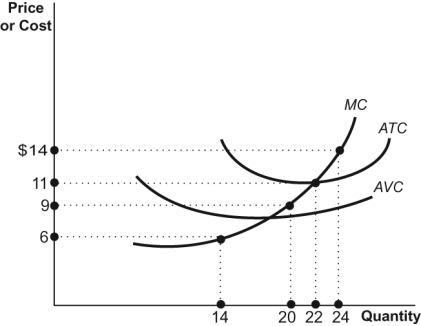 -(Figure: Game-Day Shirts) Rick is one of 10 vendors who sell game-day T-shirts at football games in a perfectly competitive market. His costs are identical to the costs of the other 9 vendors. If the price of a shirt is $11, in the long run:
 (Multiple Choice)
4.8/5 (88)
(88) Wenqin is a farmer, and in the short run she produces 100 bushels of wheat. Her average total cost per bushel is $1.75, total revenue is $450, and total fixed costs are $100. Wenqin's:
(Multiple Choice)
4.9/5 (68)
(68) Use the following to answer questions: 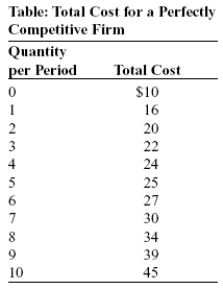 -(Table: Total Cost for a Perfectly Competitive Firm) Look at the table Total Cost for a Perfectly Competitive Firm. The firm will produce at a profit in the short run if the price is at least:
 (Multiple Choice)
4.8/5 (84)
(84) Use the following to answer question: 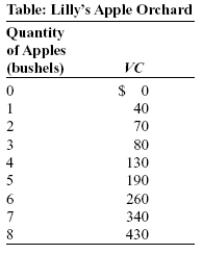 -(Table: Lilly's Apple Orchard) Look at the table Lilly's Apple Orchard. Lilly is the price-taking owner of an apple orchard. Her orchard has fixed costs of $30. If the price of a bushel of apples is $80, how many bushels will Lilly produce? Is this a long-run equilibrium? If not, what will be the price of a bushel of apples in the long run? Show your work.
 (Essay)
4.8/5 (86)
(86) The short-run industry supply curve is the sum of the marginal cost curves above average variable cost for all of the firms in the industry, assuming that the number of firms is constant.
(True/False)
4.8/5 (87)
(87) If the price is consistently below the average variable cost, then in the short run a perfectly competitive firm should:
(Multiple Choice)
4.8/5 (76)
(76) In perfect competition, the profit-maximizing level of output occurs where the:
(Multiple Choice)
4.8/5 (79)
(79) A perfectly competitive industry has 10 firms, each with an MC curve that can be expressed as MC = 5q, where q is the level of output for each firm. The minimum point of the AVC curve is $5. Which of the following equations would describe upward-sloping portion of the industry supply curve for the industry, where Q is the market quantity and P is the market price?
(Multiple Choice)
4.9/5 (77)
(77) Use the following to answer questions:
Figure: The Marginal Decision Rule 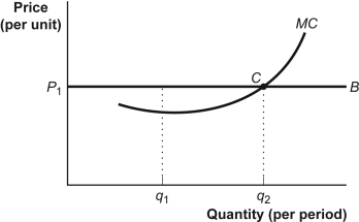 -(Figure: Marginal Decision Rule) Look at the figure The Marginal Decision Rule. Given the market price P1, B is the _____ curve.
 (Multiple Choice)
4.9/5 (69)
(69) A market that is in long-run equilibrium must also be in short-run equilibrium.
(True/False)
4.8/5 (71)
(71) When a firm produces at an output level at which MR = MC, it is operating at the _____ level.
(Multiple Choice)
4.9/5 (68)
(68) Use the following to answer questions: 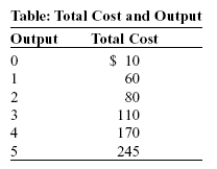 -(Table: Total Cost and Output) Look at the table Total Cost and Output, which describes Sergei's total costs for his perfectly competitive all-natural ice cream firm. If the market price of a tub of ice cream is $50, how much is Sergei's profit at the profit-maximizing output?
 (Multiple Choice)
4.8/5 (70)
(70) A competitive firm operating in the short run is producing at the output level at which ATC is at a minimum. If ATC = $8 and MR = $9, to maximize profits (or minimize losses), this firm should:
(Multiple Choice)
4.8/5 (81)
(81) A perfectly competitive firm's demand curve is perfectly elastic at the market-determined price.
(True/False)
4.8/5 (80)
(80) Use the following to answer questions: 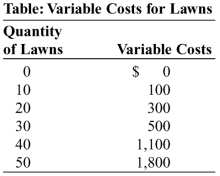 -(Table: Variable Costs for Lawns) Look at the table Variable Costs for Lawns. During the summer, Alex runs a lawn-mowing service, and lawn-mowing is a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of mowing 1 through 10 lawns is $100. His only fixed cost is $1,000 for the mower. His variable costs include fuel, his time, and mower parts. If the price for mowing a lawn is $40, how many lawns will Alex mow?
 (Multiple Choice)
4.9/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)