



 Chat with AI
Exam 12: Perfect Competition and the Supply Curve

Exam 1: First Principles233 Questions
Exam 2: Economic Models: Trade-Offs and Trade 25382 Questions
Exam 3: Supply and Demand290 Questions
Exam 4: Consumer and Producer Surplus224 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets227 Questions
Exam 6: Elasticity300 Questions
Exam 7: Taxes298 Questions
Exam 8: International Trade272 Questions
Exam 9: Decision Making by Individuals Firms201 Questions
Exam 10: The Rational Consumer372 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs362 Questions
Exam 12: Perfect Competition and the Supply Curve355 Questions
Exam 13: Monopoly350 Questions
Exam 14: Oligopoly294 Questions
Exam 15: Monopolistic Competition and Product Differentiation262 Questions
Exam 16: Externalities199 Questions
Exam 17: Public Goods Common Resources224 Questions
Exam 18: The Economics of the Welfare140 Questions
Exam 19: Factor Markets and the Distribution of Income369 Questions
Exam 20: Uncertainty, Risk, and Private Information202 Questions
Select questions type


Use the following to answer questions: 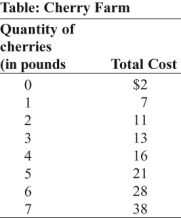 -(Table: Cherry Farm) Look at the table Cherry Farm. If the price is $6 per pound:
 (Multiple Choice)
4.9/5  (82)
(82) Use the following to answer questions:
Figure: Revenues, Costs, and Profits for Tomato Producers III 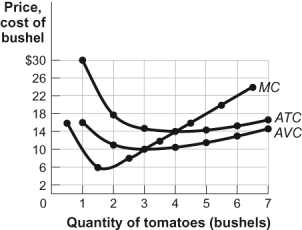 -(Figure: Revenues, Costs, and Profits for Tomato Producers III) Look at the figure Revenues, Costs, and Profits for Tomato Producers III. The market for tomatoes is perfectly competitive. If market price of a bushel of tomatoes is $18, in the short run the farmer's profit-maximizing output is _____ bushels.
 (Multiple Choice)
4.8/5 (79)
(79) If a firm's economic profits are equal to zero, its accounting profits are most likely:
(Multiple Choice)
4.8/5 (79)
(79) For a firm in a perfectly competitive market _____ revenue equals _____.
(Multiple Choice)
5.0/5 (81)
(81) Use the following to answer question:
Figure: Revenues, Costs, and Profits for Tomato Producers 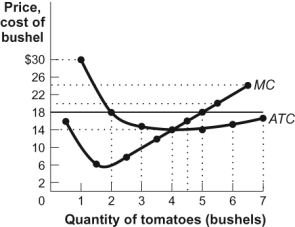 -(Figure: Revenues, Costs, and Profits for Tomato Producers) Look at the figure Revenues, Costs, and Profits for Tomato Producers. The market for tomatoes is perfectly competitive. The market price of a bushel of tomatoes is $18. At the profit-maximizing quantity of output in the figure, the farmer's total revenue is _____, total cost is _____, and profit is _____.
 (Multiple Choice)
4.8/5 (78)
(78) Use the following to answer questions: 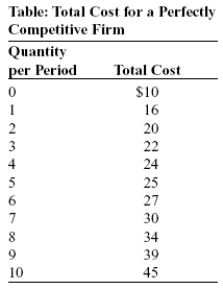 -(Table: Total Cost for a Perfectly Competitive Firm) Look at the table Total Cost for a Perfectly Competitive Firm. The firm will stop production and shut down if the price is:
 (Multiple Choice)
4.8/5 (81)
(81) Use the following to answer questions:
Figure: Costs and Profits for Tomato Producers 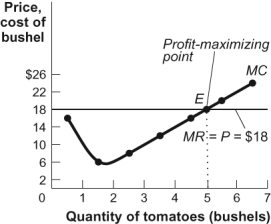 -(Figure: Costs and Profits for Tomato Producers) Look at the figure Costs and Profits for Tomato Producers. The market for tomatoes is perfectly competitive. The market price of a bushel of tomatoes is $18. If the market price increases to $20, the farmer's marginal revenue _____ and the profit-maximizing output _____.
 (Multiple Choice)
4.8/5 (74)
(74) Why is the market for soybeans a better example of perfect competition than the market for cars?
(Essay)
4.9/5 (99)
(99) The marginal revenue received by a firm in a perfectly competitive market:
(Multiple Choice)
4.8/5 (78)
(78) In the short run, a firm will continue to sell its product as long as:
(Multiple Choice)
5.0/5 (75)
(75) Use the following to answer questions: 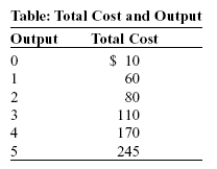 -(Table: Total Cost and Output) Look at the table Total Cost and Output, which describes Sergei's total costs for his perfectly competitive all natural ice cream firm. If there are 100 firms in the all-natural ice cream industry, which of the following is a point on the industry short-run supply curve?
 (Multiple Choice)
4.9/5 (82)
(82) When a perfectly competitive industry is in long-run equilibrium, its firms:
(Multiple Choice)
4.8/5 (73)
(73) Use the following to answer questions:
Figure: The Marginal Decision Rule 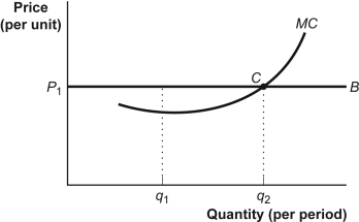 -(Figure: Marginal Decision Rule) Look at the figure The Marginal Decision Rule. If P1 is the market price and if this firm is maximizing profit, it should produce:
 (Multiple Choice)
4.8/5 (81)
(81) If a perfectly competitive firm decreases production from 11 units to 10 units and the market price is $20 per unit, total revenue for 10 units is:
(Multiple Choice)
4.7/5 (84)
(84) Use the following to answer questions:
-(Table: Cherry Farm) Look at the table Cherry Farm. If Hank and Helen have one of 100 farms in the perfectly competitive cherry industry and if the price is $3, in the short run the industry will supply _____ pounds.
-(Table: Cherry Farm) Look at the table Cherry Farm. If Hank and Helen have one of 100 farms in the perfectly competitive cherry industry and if the price is $3, in the short run the industry will supply _____ pounds. (Multiple Choice)
4.9/5 (80)
(80) The market for breakfast cereal contains hundreds of similar products, such as Froot Loops, cornflakes, and Rice Krispies, that are considered to be different products by different buyers. This situation violates the perfect competition assumption of:
(Multiple Choice)
4.8/5 (84)
(84) Suppose that the market for candy canes operates under conditions of perfect competition, that it is initially in long-run equilibrium, that the price of each candy cane is $0.10, and that the market demand curve is downward-sloping. The price of sugar rises, increasing the marginal and average total cost of producing candy canes by $0.05; there are no other changes in production costs. In the long run we will observe:
(Multiple Choice)
4.9/5 (67)
(67) Use the following to answer questions:
-(Table: Cherry Farm) Look at the table Cherry Farm. If the price is $3.60 per pound:
-(Table: Cherry Farm) Look at the table Cherry Farm. If the price is $3.60 per pound: (Multiple Choice)
4.9/5 (61)
(61) If some firms in a perfectly competitive industry are earning positive economic profits, then in the long run, the:
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)