



 Chat with AI
Exam 12: Perfect Competition and the Supply Curve

Exam 1: First Principles233 Questions
Exam 2: Economic Models: Trade-Offs and Trade 25382 Questions
Exam 3: Supply and Demand290 Questions
Exam 4: Consumer and Producer Surplus224 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets227 Questions
Exam 6: Elasticity300 Questions
Exam 7: Taxes298 Questions
Exam 8: International Trade272 Questions
Exam 9: Decision Making by Individuals Firms201 Questions
Exam 10: The Rational Consumer372 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs362 Questions
Exam 12: Perfect Competition and the Supply Curve355 Questions
Exam 13: Monopoly350 Questions
Exam 14: Oligopoly294 Questions
Exam 15: Monopolistic Competition and Product Differentiation262 Questions
Exam 16: Externalities199 Questions
Exam 17: Public Goods Common Resources224 Questions
Exam 18: The Economics of the Welfare140 Questions
Exam 19: Factor Markets and the Distribution of Income369 Questions
Exam 20: Uncertainty, Risk, and Private Information202 Questions
Select questions type


In the long run, when economic profit is zero, firms leave the industry, which will increase the market supply and price until economic profits are positive.
(True/False)
4.9/5  (75)
(75) Use the following to answer questions:
Figure: Costs and Profits for Tomato Producers 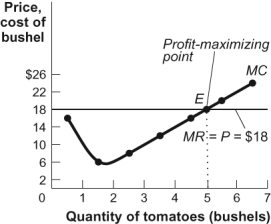 -(Figure: Costs and Profits for Tomato Producers) Look at the figure Costs and Profits for Tomato Producers. The market for tomatoes is perfectly competitive. The market price of a bushel of tomatoes is $18. If the market price falls to $16, the farmer's marginal revenue _____ and the profit-maximizing output _____.
 (Multiple Choice)
4.7/5 (66)
(66) Economic profits in a perfectly competitive industry encourage firms to _____ the industry, and losses encourage firms to _____ the industry.
(Multiple Choice)
4.8/5 (71)
(71) Hank operates a perfectly competitive firm in the long run. For several periods the market price has been $20, and his break-even price is $22. Given the chance to change his fixed costs, Hank should:
(Multiple Choice)
4.7/5 (83)
(83) Use the following to answer questions:
Figure: Game-Day Shirts 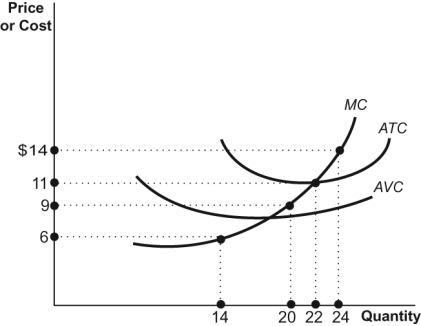 -(Figure: Game-Day Shirts) Rick is one of 10 vendors who sell game-day T-shirts at football games in a perfectly competitive market. His costs are identical to the costs of the other 9 vendors. If the price of a shirt is $9, in the long run:
 (Multiple Choice)
4.8/5 (76)
(76) Which of the following is MOST likely to cause firms to exit a perfectly competitive industry?
(Multiple Choice)
4.8/5 (66)
(66) People in the eastern part of Beirut are prevented by border guards from traveling to the western part of Beirut to shop for or sell food. This situation violates the perfect competition assumption of:
(Multiple Choice)
4.9/5 (79)
(79) In perfect competition, the assumption of easy entry and exit implies that in the _____ run all firms in the industry will earn _____ economic profits.
(Multiple Choice)
4.8/5 (76)
(76) Use the following to answer questions:
Figure: A Perfectly Competitive Firm in the Short Run 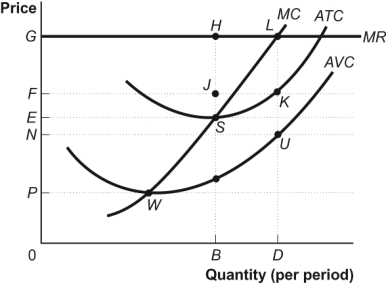 -(Figure: A Perfectly Competitive Firm in the Short Run) Look at the figure A Perfectly Competitive Firm in the Short Run. The lowest price that will yield zero economic profit is indicated by the letter:
 (Multiple Choice)
4.9/5 (81)
(81) For a firm producing at any level of output LOWER THAN the most profitable one, an increase in output adds:
(Multiple Choice)
4.9/5 (80)
(80) When a perfectly competitive firm is in long-run equilibrium, the firm is producing at _____ cost.
(Multiple Choice)
4.9/5 (73)
(73) Use the following to answer questions: 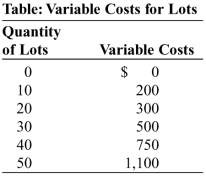 -(Table: Variable Costs for Lots) Look at the table Variable Costs for Lots. During the winter, Alexa runs a snow-clearing service in a perfectly competitive industry. Assume that costs are constant in each interval; that is, the variable cost of clearing anywhere from 1 through 10 lots is $200. Her only fixed cost is $1,000 for a snowplow. Her variable costs include fuel, her time, and hot coffee. If the price to clear a lot is $30, what is Alexa's profit at the optimal output?
 (Multiple Choice)
4.8/5 (68)
(68) The market for beef is in long-run equilibrium at $3.25 per pound. The announcement that mad cow disease has been discovered in the United States reduces the demand for beef sharply, and the price falls to $2.00 per pound. If the long-run supply curve is horizontal, when the long-run equilibrium is reestablished, the price will be:
(Multiple Choice)
4.9/5 (72)
(72) A perfectly competitive firm will incur an economic loss but will continue to produce a positive quantity of output in the short run if the price is:
(Multiple Choice)
4.9/5 (78)
(78) Explain how the long-run perfectly competitive equilibrium is efficient.
(Essay)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)