



 Chat with AI
Exam 14: Oligopoly

Exam 1: First Principles233 Questions
Exam 2: Economic Models: Trade-Offs and Trade 25382 Questions
Exam 3: Supply and Demand290 Questions
Exam 4: Consumer and Producer Surplus224 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets227 Questions
Exam 6: Elasticity300 Questions
Exam 7: Taxes298 Questions
Exam 8: International Trade272 Questions
Exam 9: Decision Making by Individuals Firms201 Questions
Exam 10: The Rational Consumer372 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs362 Questions
Exam 12: Perfect Competition and the Supply Curve355 Questions
Exam 13: Monopoly350 Questions
Exam 14: Oligopoly294 Questions
Exam 15: Monopolistic Competition and Product Differentiation262 Questions
Exam 16: Externalities199 Questions
Exam 17: Public Goods Common Resources224 Questions
Exam 18: The Economics of the Welfare140 Questions
Exam 19: Factor Markets and the Distribution of Income369 Questions
Exam 20: Uncertainty, Risk, and Private Information202 Questions
Select questions type


There are only two gas stations, Swifty Gas and Speedy Gas, in a small town. Each firm can set either a high price or a low price; customers view these two firms as nearly perfect substitutes. The table shows the payoff matrix. Profits in each cell of the payoff matrix are given as (Swifty, Speedy). If this game is played only once and each firm sets the price of gas independently, what is the Nash equilibrium? Is this game an example of a prisoners' dilemma? Explain your conclusions. 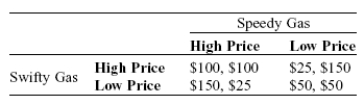

Free
(Essay)
4.8/5  (66)
(66) Correct Answer: Verified
Each gas station will set a low price. Setting a low price is a dominant strategy for each firm. If Swifty sets a high price, Speedy earns more money by setting a low price, because earning $150 is preferred to earning $100. If Swifty sets a low price, Speedy earns more money by setting a low price, because earning $50 is preferred to earning $25. Yes, it is an example of a prisoners' dilemma, because in hindsight each firm can see that there is an outcome (both setting a high price) that is mutually beneficial. Had they been able to cooperate, they might have escaped the dilemma.
Both monopolists and cartel members will find that a drop in price leads to:
Free
(Multiple Choice)
4.7/5 (75)
(75) Correct Answer:Verified
VerifiedB
An attempt by a firm to convince buyers that its product is different from the products of other firms in the industry is:
Free
(Multiple Choice)
4.8/5 (86)
(86) Correct Answer:Verified
VerifiedB
A trust is a government agency that enforces laws limiting the power of oligopolies.
(True/False)
4.9/5 (86)
(86) Use the following to answer questions:
Figure: Monopoly Profits in Duopoly  -(Figure: Monopoly Profits in Duopoly) The efficient solution in the figure Monopoly Profits in Duopoly is found where price is _____ and quantity is _____.
 (Multiple Choice)
4.7/5 (69)
(69) Unwritten or unspoken understandings through which firms restrict competition are called:
(Multiple Choice)
4.8/5 (87)
(87) Use the following to answer questions:  -(Table: Demand Schedule for Gadgets) Look at the table Demand Schedule for Gadgets. The market for gadgets consists of two producers, Margaret and Ray. Each firm can produce gadgets at a marginal cost of $2 and no fixed cost. If these two producers formed a cartel, agreed to split production of output evenly, and acted to maximize total industry profits, total industry output would be _____ and the price would be _____.
 (Multiple Choice)
4.8/5 (77)
(77) Use the following to answer questions:
Scenario: Two Identical Firms
Two identical firms make up an industry in which the market demand curve is represented by Q = 5,000 - 4P, where Q is the quantity demanded and P is price per unit. The marginal cost of producing the good in this industry is constant and equal to $650. Fixed cost is zero.
-(Scenario: Two Identical Firms) When the firms in the scenario Two Identical Firms collude and produce the profit-maximizing output, what is the profit earned by each firm?
(Multiple Choice)
4.8/5 (76)
(76) Given the large amount of interdependence among them, cooperation with one's competitors is the most profitable strategy for:
(Multiple Choice)
4.7/5 (66)
(66) Price leadership is an attempt by a firm to convince buyers that its product is different from the products of other firms in the industry.
(True/False)
4.8/5 (79)
(79) A formal agreement to limit production and raise prices leads to:
(Multiple Choice)
4.8/5 (71)
(71) In the classic prisoners' dilemma with two accomplices in crime, the Nash equilibrium is for:
(Multiple Choice)
4.8/5 (79)
(79) The largest Herfindahl-Hirschman index possible is _____, and the industry is a(n) _____.
(Multiple Choice)
5.0/5 (89)
(89) Use the following to answer questions: 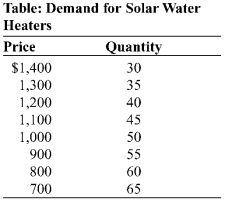 -(Table: Demand for Solar Water Heaters) Look at the table Demand for Solar Water Heaters. The marginal cost of producing solar water heaters is zero, and only two firms, Rheem and Calefi, produce them. If Rheem and Calefi get into a price war, the equilibrium price in the market will be:
 (Multiple Choice)
4.9/5 (72)
(72) Each firm in a cartel has an incentive to break its word and produce more than the agreed quantity.
(True/False)
4.8/5 (70)
(70) Use the following to answer questions:  -(Table: Demand for Crude Oil) Look at the table Demand for Crude Oil. Assume that the crude oil industry is a duopoly and the marginal and fixed cost of producing crude oil equals zero. Suppose that the two firms are maximizing industry profit and splitting the profit evenly. If firm 1 decides to cheat and increase production by 10 more barrels, it will earn profits of:
 (Multiple Choice)
4.8/5 (87)
(87) Use the following to answer questions:
-(Table: Demand Schedule for Gadgets) Look at the table Demand Schedule for Gadgets. The market for gadgets consists of two producers, Margaret and Ray. Each firm can produce gadgets at a marginal cost of $2 and no fixed cost. If the industry were perfectly competitive, the output would be _____ gadgets, and the price would be _____.
-(Table: Demand Schedule for Gadgets) Look at the table Demand Schedule for Gadgets. The market for gadgets consists of two producers, Margaret and Ray. Each firm can produce gadgets at a marginal cost of $2 and no fixed cost. If the industry were perfectly competitive, the output would be _____ gadgets, and the price would be _____. (Multiple Choice)
4.9/5 (86)
(86) Use the following to answer questions:
-(Table: Demand for Crude Oil) Look at the table Demand for Crude Oil. Assume that the crude oil industry is a duopoly and the marginal cost and fixed cost of producing crude oil equal zero. Suppose that the two firms are maximizing industry profit and splitting the profit evenly. If both firms decide to cheat and produce 10 more barrels each, industry output will be _____ barrels.
-(Table: Demand for Crude Oil) Look at the table Demand for Crude Oil. Assume that the crude oil industry is a duopoly and the marginal cost and fixed cost of producing crude oil equal zero. Suppose that the two firms are maximizing industry profit and splitting the profit evenly. If both firms decide to cheat and produce 10 more barrels each, industry output will be _____ barrels. (Multiple Choice)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)