



 Chat with AI
Exam 14: Oligopoly

Exam 1: First Principles233 Questions
Exam 2: Economic Models: Trade-Offs and Trade 25382 Questions
Exam 3: Supply and Demand290 Questions
Exam 4: Consumer and Producer Surplus224 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets227 Questions
Exam 6: Elasticity300 Questions
Exam 7: Taxes298 Questions
Exam 8: International Trade272 Questions
Exam 9: Decision Making by Individuals Firms201 Questions
Exam 10: The Rational Consumer372 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs362 Questions
Exam 12: Perfect Competition and the Supply Curve355 Questions
Exam 13: Monopoly350 Questions
Exam 14: Oligopoly294 Questions
Exam 15: Monopolistic Competition and Product Differentiation262 Questions
Exam 16: Externalities199 Questions
Exam 17: Public Goods Common Resources224 Questions
Exam 18: The Economics of the Welfare140 Questions
Exam 19: Factor Markets and the Distribution of Income369 Questions
Exam 20: Uncertainty, Risk, and Private Information202 Questions
Select questions type


Use the following to answer questions:
Figure: Pricing Strategy in Cable TV Market II 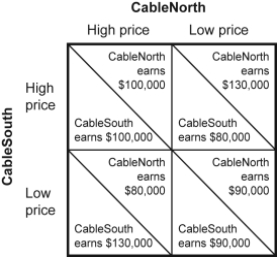 -(Figure: Pricing Strategy in Cable TV Market II) Look at the figure Pricing Strategy in Cable TV Market II. If the two firms in the cable TV market collude:
 (Multiple Choice)
4.8/5  (87)
(87) Use the following to answer questions:
Figure: Monopoly Profits in Duopoly  -(Figure: Monopoly Profits in Duopoly) The figure Monopoly Profits in Duopoly shows how an industry consisting of two firms that face identical demand curves (D1) can collude to increase profits. The market demand curve is D2. If the firms collude to share the market demand equally, then each firm will act as if its demand curve is given by:
 (Multiple Choice)
4.9/5 (74)
(74) Cartels made up of a large number of firms are unstable because each firm in the cartel:
(Multiple Choice)
4.9/5 (81)
(81) Gary's Gas and Frank's Fuel are the only two providers of gasoline in their small town. Gary and Frank decide to form a cartel to raise the price of gasoline. The total industry profits are highest when _____ cheat(s) on the agreement, and Gary's profits are highest when _____.
(Multiple Choice)
4.9/5 (75)
(75) _____ occurs when the only two firms in an industry openly agree to fix the price at a given level.
(Multiple Choice)
4.8/5 (84)
(84) A situation in which each firm acts to raise the profits of its rivals (and of itself) without any formal agreement between firms is known as tacit collusion.
(True/False)
4.8/5 (98)
(98) The airline industry often engages in price wars. This means that firms often _____ prices until profits _____.
(Multiple Choice)
4.8/5 (84)
(84) Use the following to answer questions:  -(Table: Demand Schedule for Gadgets) Look at the table Demand Schedule for Gadgets. The market for gadgets consists of two producers, Margaret and Ray. Each firm can produce gadgets with no marginal cost or fixed cost. Suppose that these two producers have formed a cartel, agreed to split production of output evenly and are maximizing total industry profits. If Margaret decides to cheat on the agreement and sell 100 more gadgets, Margaret's price effect will be a(n) _____ in profit of _____.
 (Multiple Choice)
4.7/5 (85)
(85) Use the following to answer questions:
Scenario: Payoff Matrix for Two Firms
The following table provides the payoff matrix for two firms, firm A and firm B. They are the only two firms in the industry and can either compete or cooperate with each other, with the following profit results reflecting their actions. 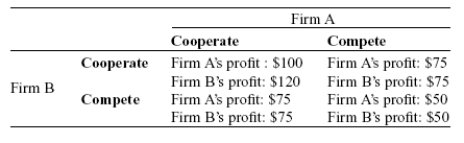 -(Scenario: Payoff Matrix for Two Firms) In the scenario Payoff Matrix for Two Firms, if both firms pursue their dominant strategies:
 (Multiple Choice)
4.8/5 (78)
(78) If Delta offers free drinks and snacks on its flights, and Southwest follows, they are engaging in tacit collusion.
(True/False)
4.8/5 (79)
(79) Use the following to answer questions:
Figure: Collusion  -(Figure: Collusion) Look at the figure Collusion. The price charged by the industry with collusion is shown by:
 (Multiple Choice)
4.8/5 (75)
(75) A strategy that is the same regardless of the action of the other player in a game is a _____ strategy.
(Multiple Choice)
4.9/5 (83)
(83) Use the following to answer questions:
Figure: Collusion
-(Figure: Collusion) Look at the figure Collusion. The quantity of output produced by firm 1 when there is collusion in the industry is shown by:
-(Figure: Collusion) Look at the figure Collusion. The quantity of output produced by firm 1 when there is collusion in the industry is shown by: (Multiple Choice)
4.9/5 (89)
(89) Use the following to answer questions:
-(Table: Demand Schedule for Gadgets) Look at the table Demand Schedule for Gadgets. The market for gadgets consists of two producers, Margaret and Ray. Each firm can produce gadgets at a marginal cost of $2 and no fixed cost. If industry output is 300 gadgets produced by Margaret and 200 gadgets produced by Ray and if Ray decides to increase output by 100, Margaret's profit will be _____, and Ray's profit will be _____.
-(Table: Demand Schedule for Gadgets) Look at the table Demand Schedule for Gadgets. The market for gadgets consists of two producers, Margaret and Ray. Each firm can produce gadgets at a marginal cost of $2 and no fixed cost. If industry output is 300 gadgets produced by Margaret and 200 gadgets produced by Ray and if Ray decides to increase output by 100, Margaret's profit will be _____, and Ray's profit will be _____. (Multiple Choice)
4.9/5 (79)
(79) A firm that is in an oligopoly knows that its _____ affect its _____ and that the _____ of its rivals will affect it.
(Multiple Choice)
4.9/5 (87)
(87) Suppose that each of the two firms in a duopoly has the independent choice of advertising or not advertising. If neither advertises, each gets $10 million in profit; if both advertise, their profits will be $5 million each; and if one advertises while the other does not, the advertiser gets profit of $15 million and the other gets profit of $2 million. According to game theory, the Nash equilibrium is:
(Multiple Choice)
4.8/5 (86)
(86) Gary's Gas and Frank's Fuel are the only two providers of gasoline in their town. Gary and Frank decide to form a cartel. Later, Gary summarizes his pricing strategy as, "I'll cheat on the cartel because regardless of what Frank does, cheating gives me the best payoff." This is an example of:
(Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)