



 Chat with AI
Exam 4: The Market Forces of Supply and Demand

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Figure 4-19 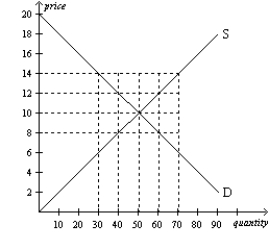 -Refer to Figure 4-19. If there is currently a shortage of 20 units of the good, then the law of
 (Multiple Choice)
4.7/5  (87)
(87) An increase in the price of cotton will increase the equilibrium price and decrease the equilibrium quantity in the market for cotton t-shirts.
(True/False)
4.9/5 (70)
(70) Today's demand curve for gasoline could shift in response to a change in
(Multiple Choice)
4.9/5 (92)
(92) The line that relates the price of a good and the quantity demanded of that good is called the demand
(Multiple Choice)
4.9/5 (86)
(86) Which of the following would most likely serve as an example of a monopoly?
(Multiple Choice)
4.9/5 (82)
(82) A likely example of substitute goods for most people would be
(Multiple Choice)
4.8/5 (82)
(82) Figure 4-13 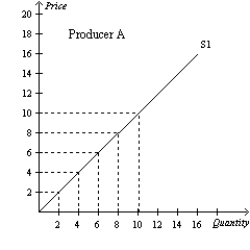
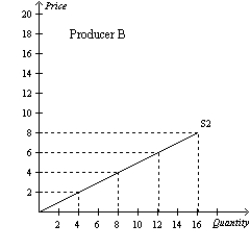 -Refer to Figure 4-13. If Producer A and Producer B are the only producers in the market, then the market quantity supplied when the price is $6 is
 (Multiple Choice)
4.8/5 (82)
(82) If a seller in a competitive market chooses to charge more than the going price, then
(Multiple Choice)
4.9/5 (79)
(79) Assume the market for tennis balls is perfectly competitive. When one tennis ball producer exits the market,
(Multiple Choice)
4.9/5 (74)
(74) If Max experiences a decrease in his income, then we would expect Max's demand for
(Multiple Choice)
4.8/5 (67)
(67) Most studies have found that tobacco and marijuana are substitutes rather than complements.
(True/False)
4.9/5 (81)
(81) Table 4-13
The demand schedule below pertains to sandwiches demanded per week. 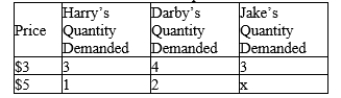 -Refer to Table 4-13. Suppose Harry, Darby, and Jake are the only demanders of sandwiches. Also suppose x = 2. Then
 (Multiple Choice)
4.7/5 (75)
(75) Suppose you make jewelry. If the price of gold falls, then we would expect you to
(Multiple Choice)
5.0/5 (84)
(84) When a supply curve or a demand curve shifts, the equilibrium price and equilibrium quantity change.
(True/False)
4.8/5 (78)
(78) Figure 4-16 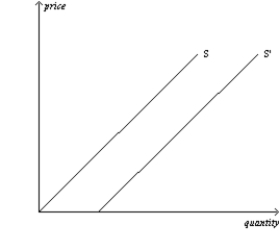 -Refer to Figure 4-16. The shift from S to S' in the market for peaches could be caused by a(n)
 (Multiple Choice)
4.9/5 (74)
(74) Figure 4-2 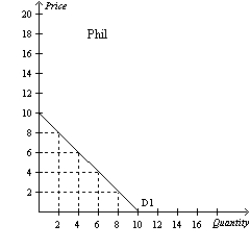
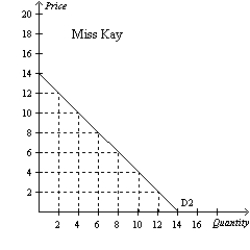 -Refer to Figure 4-2. Suppose Phil and Miss Kay are the only consumers in the market. If the price is $6, then the market quantity demanded is
 (Multiple Choice)
4.8/5 (78)
(78) Which of the following events could shift the demand curve for gasoline to the left?
(Multiple Choice)
4.8/5 (86)
(86) In a market, the price of any good adjusts until quantity demanded equals quantity supplied.
(True/False)
4.8/5 (88)
(88) Saddle shoes are not popular right now, so very few are being produced. If saddle shoes become popular, then how will this affect the market for saddle shoes?
(Multiple Choice)
4.8/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)