



 Chat with AI
Exam 4: The Market Forces of Supply and Demand

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


If the demand for a good falls when income falls, then the good is called an inferior good.
(True/False)
4.8/5  (81)
(81) Studies show that lower cigarette prices are associated with greater use of marijuana; therefore, tobacco and marijuana are
(Short Answer)
4.9/5 (85)
(85) An increase in the price of pizza will shift the demand curve for pizza to the left.
(True/False)
4.9/5 (77)
(77) 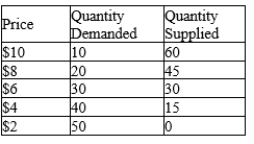 -Refer to Table 4-11. If the price were $8, a
Funsters, Inc., the largest toy company in the country, sells its most popular doll for $15. It has just learned that its leading competitor, Toysorama, is mass-producing an excellent copy and plans to flood the market with their $5 doll in six weeks. Funsters should
(Multiple Choice)
4.9/5 (80)
(80) You lose your job and, as a result, you buy fewer iTunes music downloads. This shows that you consider iTunes music downloads to be a(n)
(Multiple Choice)
4.9/5 (82)
(82) Figure 4-15 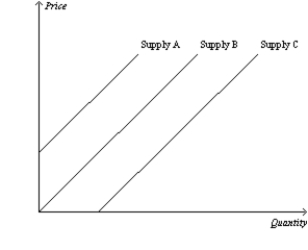 -Refer to Figure 4-15. Which of the following would cause the supply curve to shift from Supply A to Supply C in the market for sail boats?
 (Multiple Choice)
4.9/5 (94)
(94) Music compact discs are normal goods. What will happen to the equilibrium price and quantity of music compact discs if musicians accept lower royalties, compact disc players become cheaper, more firms start producing music compact discs, and music lovers experience an increase in income?
(Multiple Choice)
4.7/5 (70)
(70) Figure 4-27
Panel (a)
Panel (b) 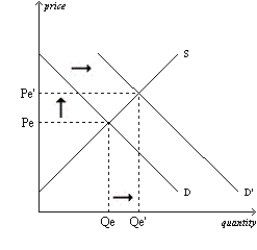
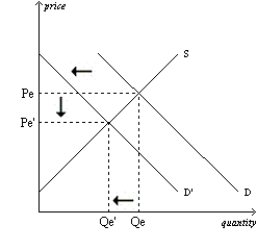 Panel (c)
Panel (d)
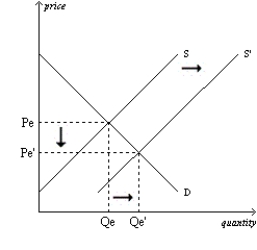
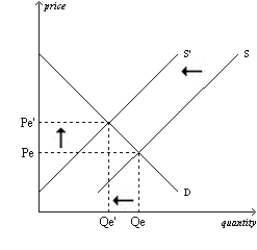 -Refer to Figure 4-27. Which of the four panels illustrates an increase in quantity demanded?
Panel (c)
Panel (d)
-Refer to Figure 4-27. Which of the four panels illustrates an increase in quantity demanded? (Multiple Choice)
4.9/5 (81)
(81) You love peanut butter. You hear on the news that 50 percent of the peanut crop in the South has been wiped out by drought and that this will cause the price of peanuts to double by the end of the year. As a result, your demand for peanut butter
(Multiple Choice)
4.8/5 (80)
(80) Assume the market for pork is perfectly competitive. When one pork buyer exits the market,
(Multiple Choice)
4.8/5 (82)
(82) If Miguel expects to earn a higher income next month, he may choose to
(Multiple Choice)
4.8/5 (72)
(72) An early frost in the vineyards of Napa Valley would cause a(n)
(Multiple Choice)
5.0/5 (84)
(84) Scenario 4-1
Suppose the demand schedule in a market can be represented by the equation 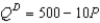 , where
 is the quantity demanded and
 is the price. Also, suppose the supply schedule can be represented by the equation
 , where
 is the quantity supplied.
-Refer to Scenario 4-1. Suppose the supply curve shifts to
 . What is the new equilibrium price and quantity in this market?
, where is the quantity demanded and is the price. Also, suppose the supply schedule can be represented by the equation , where is the quantity supplied.
-Refer to Scenario 4-1. Suppose the supply curve shifts to
. What is the new equilibrium price and quantity in this market? (Short Answer)
4.7/5 (68)
(68) There is no shortage of scarce resources in a market economy because
(Multiple Choice)
4.9/5 (76)
(76) Which of the following events must cause equilibrium quantity to fall?
(Multiple Choice)
4.7/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)