



 Chat with AI
Exam 40: International Trade Restrictions

Exam 1: Economics: The World Around You90 Questions
Exam 2: Choice, Opportunity Costs, and Specialization94 Questions
Exam 3: Markets, Demand and Supply, and the Price System97 Questions
Exam 5: The Market System and the Private and Public Sector97 Questions
Exam 4: Elasticity: Demand and Supply126 Questions
Exam 6: National Income Accounting104 Questions
Exam 7: an Introduction to the Foreign Exchange Market and the Balance of Payments90 Questions
Exam 8: Consumer Choice132 Questions
Exam 9: Supply: The Costs of Doing Business106 Questions
Exam 10: Unemployment and Inflation129 Questions
Exam 11: Macroeconomic Equilibrium: Aggregate Demand and Supply122 Questions
Exam 12: Profit Maximization122 Questions
Exam 13: Aggregate Expenditures115 Questions
Exam 14: Perfect Competition135 Questions
Exam 15: Income and Expenditures Equilibrium134 Questions
Exam 16: Monopoly118 Questions
Exam 17: Fiscal Policy93 Questions
Exam 18: Monopolistic Competition and Oligopoly111 Questions
Exam 19: Antitrust and Regulation100 Questions
Exam 10: Money and Banking125 Questions
Exam 21: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 22: Monetary Policy141 Questions
Exam 23: Macroeconomic Policy: Tradeoffs, Expectations, Credibility, and Sources of Business Cycles112 Questions
Exam 24: Resource Markets112 Questions
Exam 25: Macroeconomic Viewpoints: New Keynesian, Monetarist, and New Classical99 Questions
Exam 26: The Labor Market114 Questions
Exam 27: Capital Markets100 Questions
Exam 28: Economic Growth99 Questions
Exam 29: Development Economics104 Questions
Exam 30: the Land Market and Natural Resources55 Questions
Exam 31: Aging, Social Security and Health Care88 Questions
Exam 32: Globalization84 Questions
Exam 33: Elasticity: Demand and Supply126 Questions
Exam 34: Income Distribution, Poverty and Government Policy115 Questions
Exam 35: World Trade Equilibrium112 Questions
Exam 36: Consumer Choice132 Questions
Exam 37: International Trade Restrictions109 Questions
Exam 38: World Trade Equilibrium112 Questions
Exam 39: Exchange Rates and Financial Links Between Countries132 Questions
Exam 40: International Trade Restrictions109 Questions
Exam 41: Supply: the Costs of Doing Business106 Questions
Exam 42: Exchange Rates and Financial Links Between Countries132 Questions
Exam 43: Profit Maximization122 Questions
Exam 44: Perfect Competition135 Questions
Exam 45: Monopoly118 Questions
Exam 46: Monopolistic Competition and Oligopoly111 Questions
Exam 47: Antitrust and Regulation100 Questions
Exam 48: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 49: Resource Markets112 Questions
Exam 50: The Labor Market114 Questions
Exam 51: Capital Markets100 Questions
Exam 52: The Land Market and Natural Resources55 Questions
Exam 53: Aging, Social Security and Health Care87 Questions
Exam 54: Income Distribution, Poverty and Government Policy115 Questions
Exam 55: World Trade Equilibrium112 Questions
Exam 56: International Trade Restrictions109 Questions
Exam 57: Exchange Rates and Financial Links Between Countries132 Questions
Select questions type


The figure below shows the demand (D)and supply (S)curves of corn syrups. Figure 21.3 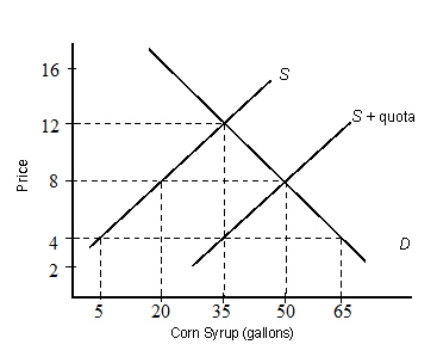 In Figure 21.3, with an import quota of 30 gallons of corn syrup, what is the new equilibrium price?
 (Multiple Choice)
4.9/5  (73)
(73) A monopoly exists when there is only one producer in an industry, and no close substitutes for the product exist.
(True/False)
4.8/5 (86)
(86) The figure given below depicts the negatively sloped demand and positively sloped supply curves of wheat in a country. Figure 21.2 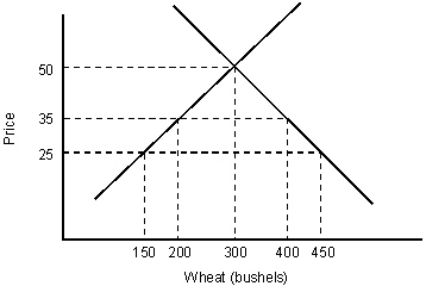 According to Figure 21.2, if the world price of wheat is $25 and a tariff of $10 is imposed by the domestic government, the total tariff revenue collected by the government is:
 (Multiple Choice)
4.8/5 (86)
(86) The world output is higher if the countries follow restrictive trade policies rather than free trade.
(True/False)
4.9/5 (84)
(84) Creating conditions for fair trade by limiting imports will make the domestic consumers better off, as they will be required to pay low prices for the products.
(True/False)
4.9/5 (75)
(75) Domestic firms often claim that foreign firms have an unfair advantage because foreign workers are willing to work for very low wages.
(True/False)
4.8/5 (76)
(76) The figure given below depicts the negatively sloped demand and positively sloped supply curves of wheat in a country. Figure 21.2 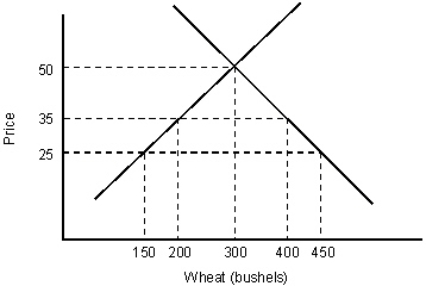 In Figure 21.2, if the world price of wheat is $25 and a $10 tariff is imposed:
 (Multiple Choice)
4.9/5 (82)
(82) In the light of the infant industry argument, identify the industry which is likely to have substantially high initial costs.
(Multiple Choice)
4.8/5 (77)
(77) When dealing with strategic trade policy, one practical problem for government is the likelihood of retaliation by the foreign government.
(True/False)
4.9/5 (72)
(72) The most successful free trade agreements achieve all of the following goals, except:
(Multiple Choice)
4.9/5 (90)
(90) The figure below shows the demand (D)and supply (S)curves of cocoa in the U.S. Figure 21.4 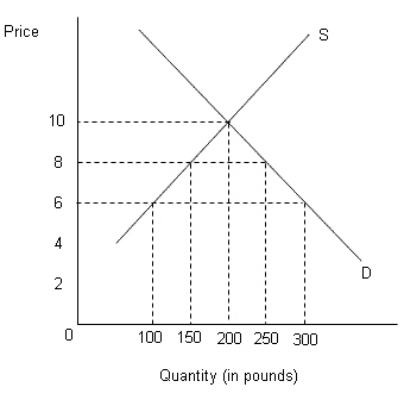 From Figure 21.4, determine the total volume of U.S.cocoa imports if its government imposes tariff at the rate of $2 per pound on cocoa.
 (Multiple Choice)
4.9/5 (85)
(85) Since individual consumers do not know how much of the price they pay for a commodity is due to protection, consumers rarely lobby their political representatives to eliminate protection and reduce prices.
(True/False)
4.8/5 (89)
(89) The figure below shows the demand (D)and supply (S)curves of corn syrups. Figure 21.3 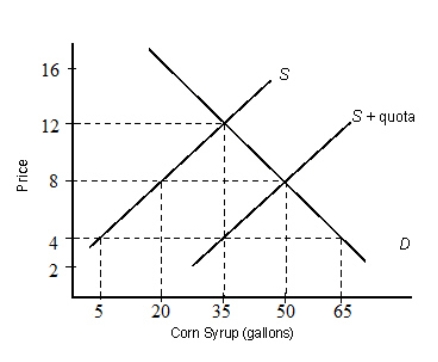 In Figure 21.3, if the world price per gallon is $8, then without quotas:
 (Multiple Choice)
4.9/5 (67)
(67) Protecting infant industries from foreign competition may make sense, but only until the industry matures.
(True/False)
4.8/5 (78)
(78) According to strategic trade policy, international trade largely involves firms which:
(Multiple Choice)
4.9/5 (94)
(94) Which of the following statements about international trade restrictions is true?
(Multiple Choice)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)