



 Chat with AI
Exam 13: Firms in Competitive Markets

Exam 1: Ten Principles of Economics438 Questions
Exam 2: Thinking Like an Economist620 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand700 Questions
Exam 5: Elasticity and Its Application598 Questions
Exam 6: Supply, Demand, and Government Policies648 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets550 Questions
Exam 8: Application: The Costs of Taxation514 Questions
Exam 9: Application: International Trade496 Questions
Exam 10: Externalities522 Questions
Exam 11: Public Goods and Common Resources434 Questions
Exam 12: The Costs of Production420 Questions
Exam 13: Firms in Competitive Markets543 Questions
Exam 14: Monopoly637 Questions
Exam 15: Measuring a Nations Income522 Questions
Exam 16: Measuring the Cost of Living545 Questions
Exam 17: Production and Growth507 Questions
Exam 18: Saving, Investment, and the Financial System567 Questions
Exam 19: The Basic Tools of Finance513 Questions
Exam 20: Unemployment699 Questions
Exam 21: The Monetary System518 Questions
Exam 22: Money Growth and Inflation487 Questions
Exam 23: Aggregate Demand and Aggregate Supply563 Questions
Exam 24: The Influence of Monetary and Fiscal Policy on Aggregate Demand512 Questions
Select questions type


A firm in a competitive market currently produces and sells 500 doorknobs for a price of $10 per doorknob. Which of the following events would decrease the firm's average revenue?
(Multiple Choice)
4.8/5  (82)
(82) Table 14-14
The following table presents cost and revenue information for Bob's bakery production and sales.
 -Refer to Table 14-14. Suppose that due to a decrease in the market demand for bread the market price of bread drops to $2.75. At this new price, if Bob produces and sells the profit-maximizing quantity, how much profit will he earn?
 (Multiple Choice)
4.9/5 (65)
(65) Table 14-12
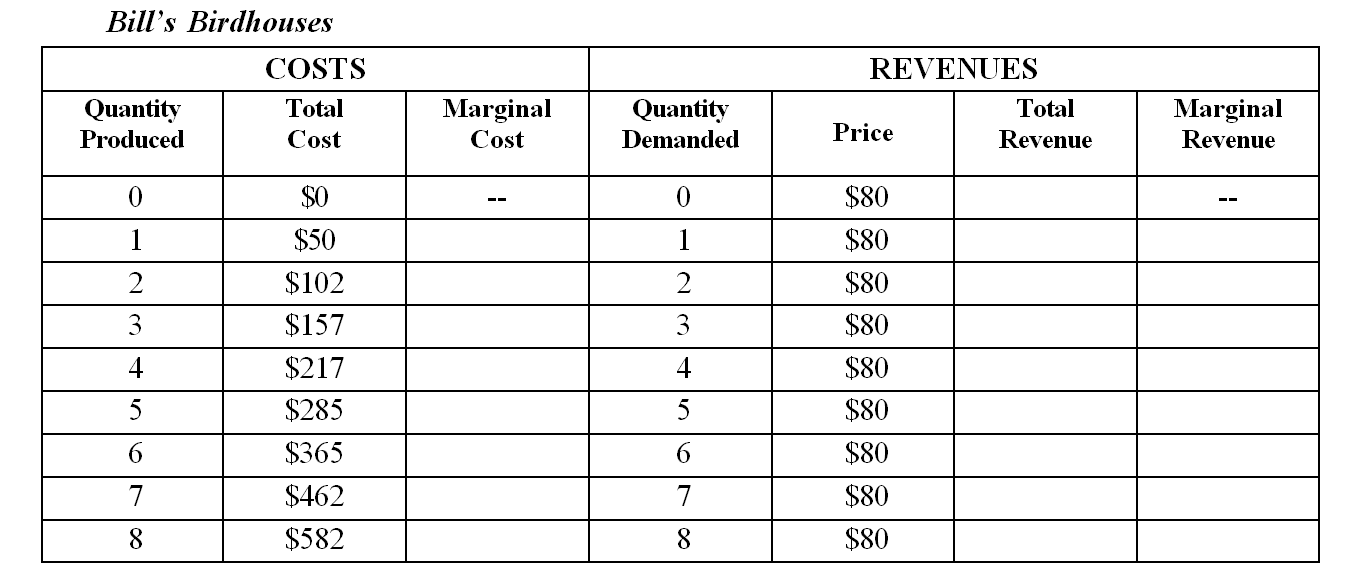 -Refer to Table 14-12. What is the marginal revenue from selling the 5th unit?
 (Multiple Choice)
4.9/5 (83)
(83) Table 14-12
-Refer to Table 14-12. What is the total revenue from selling 4 units?
-Refer to Table 14-12. What is the total revenue from selling 4 units? (Multiple Choice)
4.7/5 (89)
(89) Why would a firm in a perfectly competitive market always choose to set its price equal to the current market price? If a firm set its price below the current market price, what effect would this have on the market?
(Essay)
4.7/5 (78)
(78) Table 14-14
The following table presents cost and revenue information for Bob's bakery production and sales.
-Refer to Table 14-14. What is Bob's total fixed cost?
-Refer to Table 14-14. What is Bob's total fixed cost? (Multiple Choice)
4.8/5 (70)
(70) Profit-maximizing firms enter a competitive market when existing firms in that market have
(Multiple Choice)
4.8/5 (77)
(77) A firm operating in a perfectly competitive market earns zero economic profit in the long run but remains in business because the firm's revenues cover the business owners' opportunity costs.
(True/False)
4.9/5 (87)
(87) Figure 14-7  -Refer to Figure 14-7. At what price is the firm's maximum profit zero?
 (Multiple Choice)
4.8/5 (76)
(76) Table 14-9
Suppose that a firm in a competitive market faces the following revenues and costs:
 -Refer to Table 14-9. If the firm's marginal cost is $5, it should
 (Multiple Choice)
4.8/5 (79)
(79) Table 14-14
The following table presents cost and revenue information for Bob's bakery production and sales.
-Refer to Table 14-14. When Bob produces and sells the profit-maximizing quantity, how much profit does he earn?
-Refer to Table 14-14. When Bob produces and sells the profit-maximizing quantity, how much profit does he earn? (Multiple Choice)
4.7/5 (75)
(75) In a competitive market with free entry and exit, if all firms have the same cost structure, then
(Multiple Choice)
4.8/5 (89)
(89) In the long run, when price is less than average total cost for all possible levels of production, a firm in a competitive market will choose to exit or not enter) the market.
(True/False)
4.7/5 (93)
(93) A firm that has little ability to influence market prices operates in a
(Multiple Choice)
4.9/5 (80)
(80) Which of the following industries is most likely to exhibit the characteristic of free entry?
(Multiple Choice)
5.0/5 (71)
(71) In a perfectly competitive market, the process of entry and exit will end when
(Multiple Choice)
4.7/5 (85)
(85) In calculating accounting profit, accountants typically don't include
(Multiple Choice)
4.8/5 (79)
(79) In the long-run equilibrium of a competitive market, the number of firms in the market adjusts until the market demand is satisfied at a price equal to the minimum of
(Multiple Choice)
4.8/5 (87)
(87) In a competitive market the price is $8. A typical firm in the market has ATC = $6, AVC = $5, and MC = $8. How much economic profit is the firm earning in the short run?
(Multiple Choice)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)