



 Chat with AI
Exam 13: Firms in Competitive Markets

Exam 1: Ten Principles of Economics438 Questions
Exam 2: Thinking Like an Economist620 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand700 Questions
Exam 5: Elasticity and Its Application598 Questions
Exam 6: Supply, Demand, and Government Policies648 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets550 Questions
Exam 8: Application: The Costs of Taxation514 Questions
Exam 9: Application: International Trade496 Questions
Exam 10: Externalities522 Questions
Exam 11: Public Goods and Common Resources434 Questions
Exam 12: The Costs of Production420 Questions
Exam 13: Firms in Competitive Markets543 Questions
Exam 14: Monopoly637 Questions
Exam 15: Measuring a Nations Income522 Questions
Exam 16: Measuring the Cost of Living545 Questions
Exam 17: Production and Growth507 Questions
Exam 18: Saving, Investment, and the Financial System567 Questions
Exam 19: The Basic Tools of Finance513 Questions
Exam 20: Unemployment699 Questions
Exam 21: The Monetary System518 Questions
Exam 22: Money Growth and Inflation487 Questions
Exam 23: Aggregate Demand and Aggregate Supply563 Questions
Exam 24: The Influence of Monetary and Fiscal Policy on Aggregate Demand512 Questions
Select questions type


Suppose a firm operates in the short run at a price above its average total cost of production. In the long run the firm should expect
(Multiple Choice)
4.7/5  (87)
(87) All firms maximize profits by producing an output level where marginal revenue equals marginal cost; for firms operating in perfectly competitive industries, maximizing profits also means producing an output level where price equals marginal cost.
(True/False)
4.8/5 (61)
(61) Which of the following characteristics of competitive markets is necessary for firms to be price takers? i) There are many sellers.
Ii) Firms can freely enter or exit the market.
Iii) Goods offered for sale are largely the same.
(Multiple Choice)
4.9/5 (88)
(88) The long-run supply curve in a competitive market is more elastic than the short-run supply curve.
(True/False)
4.8/5 (83)
(83) For a firm operating in a perfectly competitive industry, marginal revenue and average revenue are equal.
(True/False)
4.8/5 (72)
(72) Figure 14-10
In the figure below, panel a) depicts the linear marginal cost of a firm in a competitive market, and panel b) depicts the linear market supply curve for a market with a fixed number of identical firms.
 -Refer to Figure 14-10. If there are 700 identical firms in this market, what is the value of Q2?
 (Multiple Choice)
4.9/5 (88)
(88) If occupational safety laws were changed so that firms no longer had to take expensive steps to meet regulatory requirements, we would expect that
(Multiple Choice)
4.8/5 (72)
(72) Figure 14-1
Suppose that a firm in a competitive market has the following cost curves:  -Refer to Figure 14-1. If the market price is $5.00, the firm will earn
 (Multiple Choice)
4.9/5 (74)
(74) For any competitive market, the supply curve is closely related to the
(Multiple Choice)
4.8/5 (62)
(62) Table 14-7
Suppose that a firm in a competitive market faces the following revenues and costs:
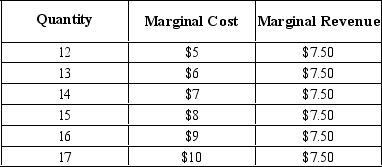 -Refer to Table 14-7. If the firm is currently producing 14 units, what would you advise the owners?
 (Multiple Choice)
4.9/5 (85)
(85) Which of the following statements regarding a competitive market is not correct?
(Multiple Choice)
4.9/5 (74)
(74) A firm operating in a perfectly competitive industry will continue to operate in the short run but earn losses if the
market price is less than that firm's average variable cost.
(True/False)
5.0/5 (77)
(77) Susan quit her job as a teacher, which paid her $36,000 per year, in order to start her own catering business. She spent $12,000 of her savings, which had been earning 10 percent interest per year, on equipment for her business. She also borrowed $12,000 from her bank at 10 percent interest, which she also spent on equipment. For the past several months she has spent $1,000 per month on ingredients and other variable costs. Also for the past several months she has taken in $3,500 in monthly revenue. In the short run, Susan should
(Multiple Choice)
4.9/5 (93)
(93) Suppose that a firm operating in perfectly competitive market sells 300 units of output at a price of $3 each. Which of the following statements is correct? i) Marginal revenue equals $3.
Ii) Average revenue equals $3.
Iii) Total revenue equals $900.
(Multiple Choice)
4.9/5 (77)
(77) The stable, long-run equilibrium in a competitive market occurs when the market price equals the lowest point on a firm's average total cost curve.
(True/False)
5.0/5 (66)
(66) In the transition from the short run to the long run, the number of firms in a competitive industry is
(Multiple Choice)
4.8/5 (87)
(87) When new entrants into a competitive market have higher costs than existing firms,
(Multiple Choice)
4.8/5 (75)
(75) In the long run, a firm should exit the industry if its total costs exceed its total revenues.
(True/False)
4.9/5 (76)
(76) When firms have an incentive to exit a competitive market, their exit will
(Multiple Choice)
4.8/5 (75)
(75) Scenario 14-4
The information below applies to a competitive firm that sells its output for $40 per unit.
• When the firm produces and sells 150 units of output, its average total cost is $24.50.
• When the firm produces and sells 151 units of output, its average total cost is $24.55.
-Refer to Scenario 14-4. When the firm produces 150 units of output, its total cost is
(Multiple Choice)
4.9/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)