



 Chat with AI
Exam 22: Long-Run Economic Growth: Sources and Policies

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System152 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes137 Questions
Exam 5: Externalities, environmental Policy, and Public Goods139 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply149 Questions
Exam 7: The Economics of Health Care117 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance140 Questions
Exam 9: Comparative Advantage and the Gains From International Trade124 Questions
Exam 10: Consumer Choice and Behavioral Economics154 Questions
Exam 11: Technology, production, and Costs174 Questions
Exam 12: Firms in Perfectly Competitive Markets153 Questions
Exam 13: Monopolistic Competition: The Competitive Model in a More Realistic Setting137 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets129 Questions
Exam 15: Monopoly and Antitrust Policy148 Questions
Exam 16: Pricing Strategy134 Questions
Exam 17: The Markets for Labor and Other Factors of Production149 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income134 Questions
Exam 19: GDP: Measuring Total Production and Income135 Questions
Exam 20: Unemployment and Inflation148 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies134 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run157 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 25: Money, banks, and the Federal Reserve System144 Questions
Exam 26: Monetary Policy145 Questions
Exam 27: Fiscal Policy155 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy135 Questions
Exam 29: Macroeconomics in an Open Economy145 Questions
Exam 30: The International Financial System139 Questions
Select questions type


The rate of growth of productivity in the United States was positive during the 20th century.
(True/False)
4.8/5  (68)
(68) From 1990-2010,productivity growth in the United States was ________ the growth rates of other high-income countries.
(Multiple Choice)
4.9/5 (82)
(82) Small differences in economic growth rates result in small differences in living standards.
(True/False)
4.9/5 (88)
(88) According to the World Bank,Albania does one of the worst jobs as a country enforcing the rule of law.The consequence of a weak rule of law is
(Multiple Choice)
4.9/5 (95)
(95) Table 22-1
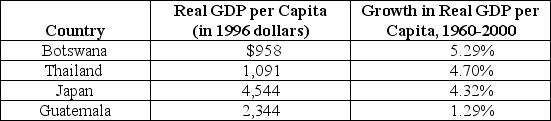 -Refer to Table 22-1.In the table above,which countries are consistent with the predictions of the economic growth model?
 (Multiple Choice)
4.8/5 (88)
(88) Suppose that an increase in capital per hour worked from $15,000 to $20,000 increases real GDP per hour worked by $500.If capital per hour worked increases further to $25,000,by how much would you expect real GDP per hour worked to increase if there are diminishing returns?
(Multiple Choice)
4.9/5 (87)
(87) The period of time from 1,000,000 B.C.to 1300 A.D.was a period of
(Multiple Choice)
4.8/5 (86)
(86) Which of the following is a true statement regarding the economic growth model's predictions and how it actually affects the real world?
(Multiple Choice)
4.9/5 (69)
(69) The "new economy" that emerged in the mid-1990s is based on
(Multiple Choice)
4.9/5 (85)
(85) The productivity slowdown of the mid-1970s can be explained by which of the following?
(Multiple Choice)
4.8/5 (67)
(67) When additions of input to a fixed quantity of another input lead to progressively smaller increases in output,we say we are facing
(Multiple Choice)
4.8/5 (93)
(93) Because firms can free ride on the research and development of other firms,
(Multiple Choice)
4.7/5 (79)
(79) Disease,poor nutrition,and substandard health care in developing nations can reduce growth in an economy by
(Multiple Choice)
4.8/5 (82)
(82) Why do some firms choose not to file for a patent and instead try to keep the results of their research a trade secret?
(Multiple Choice)
4.9/5 (78)
(78) Figure 22-1  -Refer to Figure 22-1.Diminishing marginal returns is illustrated in the per-worker production function in the figure above by a movement from
A) A to C.
B) B to C.
C) C to D.
D) D to C.
-Refer to Figure 22-1.Diminishing marginal returns is illustrated in the per-worker production function in the figure above by a movement from
A) A to C.
B) B to C.
C) C to D.
D) D to C. (Not Answered)
This question doesn't have any answer yet
If real GDP per capita in Ireland is estimated to be $7,400 in 2012,what will real GDP per capita be in 2017 if real GDP per capita grows at an annual rate of 2.8%?
(Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)