



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


In computing consolidated E & P, dividends paid to the parent by group members are subtracted.
(True/False)
4.9/5  (74)
(74) When an affiliated group elects to file Federal consolidated income tax returns, it gives up the ability to claim a deduction for distributions of profits paid to other members.
(Short Answer)
4.7/5 (86)
(86) Which of the following is not generally a disadvantage of filing Federal corporate income tax returns on a consolidated basis?
(Multiple Choice)
4.8/5 (71)
(71) Consolidated return members determine which affiliates will pay how much of the annual Federal income tax liability by making a(n) election.
(Short Answer)
4.8/5 (71)
(71) Match each of the following items with the appropriate description, indicating whether the item's treatment for financial accounting and Federal income tax purposes is the same or not.
a. Tax and book treatment is the same
b. Tax and book treatment differ
-Sales amounts (after returns and allowances) are combined in the consolidation process.
(Short Answer)
4.8/5 (97)
(97) ParentCo and SubCo recorded the following items of income and deduction for the current tax year. 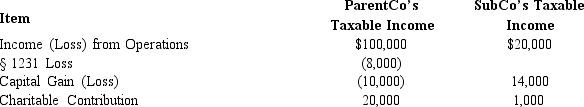 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.7/5 (78)
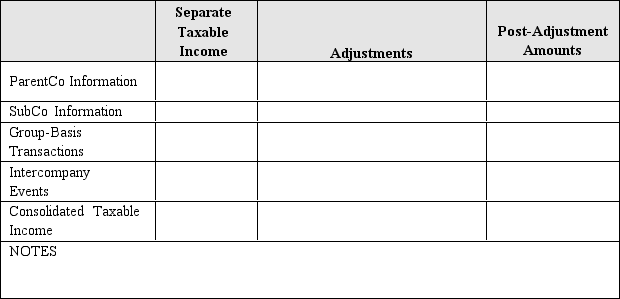
(78) Parent Corporation's currentyear taxable income included $100,000 net profit from operations and a $30,000 net long-term capital gain. Parent also made a $22,000 contribution to State University. SubCo produced $85,000 of income from operations and incurred a $25,000 net short-term capital loss.
Use the computational worksheet of Figure 8.2 to derive the group members' separate taxable incomes and the group's consolidated taxable income.
(Essay)
4.8/5 (76)
(76) Which of the following entities is eligible to file Federal income tax returns on a consolidated basis?
(Multiple Choice)
4.9/5 (76)
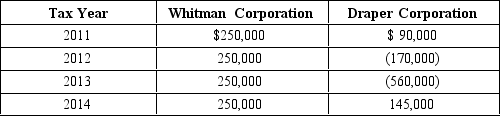
(76) For each of the indicated tax years, compute consolidated taxable income for the calendar year Whitman Group, which elected consolidated status immediately upon creation of the two member corporations in January 2011. All recognized income related to the data processing services of the firms. No intercompany transactions were completed during the indicated years.
(Essay)
4.9/5 (84)
(84) The rules for computing Federal consolidated taxable income are some of the most complex in the tax law.
(True/False)
4.8/5 (79)
(79) In terms of the consolidated return rules, the Radcliffe Charitable Foundation is a(n) entity.
(Short Answer)
5.0/5 (74)
(74) A penalty can be assessed by the IRS if the parent corporation does not keep good records to support the computation of a subsidiary's stock basis.
(True/False)
4.9/5 (85)
(85) Describe the general computational method used by a Federal consolidated group in computing taxable income.
(Essay)
4.9/5 (73)
(73) In computing consolidated taxable income, a net capital gain/loss is an example of a(n) ___________________ item.
(Short Answer)
4.7/5 (90)
(90) The foreign tax credit of a consolidated group can be greater than the sum of the credits of the group members when filing separately.
(True/False)
4.9/5 (81)
(81) Which of the following potentially is a disadvantage of electing to file a Federal corporate income tax consolidated return?
(Multiple Choice)
4.8/5 (92)
(92) Lacking elections to the contrary, Federal consolidated NOLs are carried back two years and then forward twenty years.
(True/False)
4.8/5 (69)
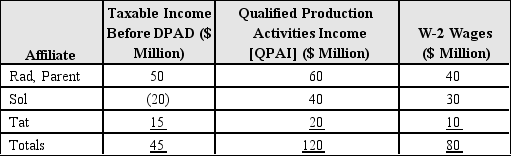
(69) Except for the § 199 domestic production activities deduction (DPAD), the members of an electing affiliated group report the following data. Compute the group's DPAD.
(Essay)
4.9/5 (88)
(88) Cooper Corporation joined the Duck consolidated Federal income tax return group, when Cooper held a $1 million NOL carryforward. In its first year as a part of the Duck group, Cooper generated a $150,000 taxable loss. For that year, Duck cannot deduct any of Cooper's NOL in computing consolidated taxable income.
(True/False)
4.9/5 (86)
(86) Gold and Bronze elect to form a Federal consolidated group. Gold, the parent entity, uses a calendar tax year, while Bronze's tax year ends on March 31. Which tax year(s) does the new consolidated group use?
(Essay)
4.7/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)