



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
a. Group item
b. Not a group item
-Charitable contributions
(Short Answer)
5.0/5  (92)
(92) Generally, when a subsidiary leaves an on-going consolidated group, it must wait years before it again can reenter the parent's consolidated group.
(Short Answer)
4.7/5 (74)
(74) How many consolidated tax returns are filed annually? What types of taxpayer do they represent?
(Essay)
4.9/5 (81)
(81) Parent Corporation, SubOne, and SubTwo have filed consolidated returns since 2013. All of the entities were incorporated in 2012. None of the group members incurred any capital gain or loss transactions during 2012-2015, nor did they make any charitable contributions. Taxable income computations for the members are listed below.
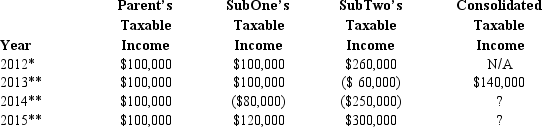 * Separate return year.
** Consolidated return year.
a. How much of the 2014 loss is apportioned to SubOne and SubTwo? How is this loss treated in generating a refund of prior tax payments?
b. Why would Parent consider electing to forgo the carryback of the 2014 consolidated NOL?
c. In this light, analyze the election to consolidate.
* Separate return year.
** Consolidated return year.
a. How much of the 2014 loss is apportioned to SubOne and SubTwo? How is this loss treated in generating a refund of prior tax payments?
b. Why would Parent consider electing to forgo the carryback of the 2014 consolidated NOL?
c. In this light, analyze the election to consolidate. (Essay)
4.8/5 (82)
(82) For each of the indicated tax years, compute consolidated taxable income for the calendar year Holloway Group, which elected consolidated status immediately upon creation of the two member corporations in January 2011. All recognized income related to the data processing services of the firms. No intercompany transactions were completed during the indicated years.
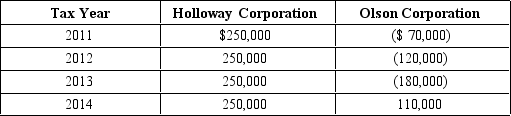
(Essay)
5.0/5 (78)
(78) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
a. Increases stock basis of subsidiary
b. Decreases stock basis of subsidiary
c. No effect on stock basis of subsidiary
-Member's operating loss, when stock basis = $0
(Short Answer)
4.7/5 (68)
(68) The Philstrom consolidated group reported the following taxable income amounts. Parent owns all of the stock of both Junior and Minor. Determine the net operating loss (NOL) that is apportioned to Minor. 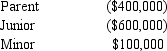
(Multiple Choice)
4.9/5 (66)
(66) If subsidiary stock is redeemed or sold outside the group when an excess loss account exists, the selling parent corporation recognizes ordinary income equal to the account balance.
(True/False)
4.9/5 (77)
(77) Forming a Federal consolidated tax return group is a discretionary action by eligible affiliates. List several tax attributes and situations that might make a subsidiary an attractive partner for a parent corporation on a consolidated return.
(Essay)
4.8/5 (78)
(78) A parent-subsidiary controlled group exists where there is percent ownership of all of the affiliates within the group, and there is an identifiable corporation.
(Short Answer)
4.8/5 (83)
(83) A limited partnership can join the parent's consolidated group for book and for tax purposes.
(True/False)
4.9/5 (84)
(84) ParentCo purchased all of the stock of ChildCo on January 2, 2012, and the two companies filed consolidated returns for 2012 and thereafter. Both entities were incorporated in 2011. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. No § 382 limit applies. 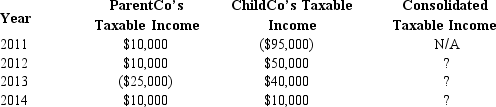 Assuming that no election is made to forgo the carryback, to what extent are ChildCo's 2011 losses used by the group in 2012-2014?
 (Multiple Choice)
4.9/5 (91)
(91) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
a. Increases stock basis of subsidiary
b. Decreases stock basis of subsidiary
c. No effect on stock basis of subsidiary
-Dividend paid to parent out of affiliate's E & P
(Short Answer)
4.7/5 (80)
(80) Calendar year ParentCo acquired all of the stock of SubCo on January 1, 2013, for $1,000,000. The parties immediately elected to file consolidated income tax returns. SubCo generated taxable income of $250,000 for 2013 and paid a dividend of $100,000 to ParentCo. In 2014, SubCo generated an operating loss of $350,000, and in 2015 it produced taxable income of $750,000. As of the last day of 2015, what was ParentCo's basis in the stock of SubCo?
(Multiple Choice)
4.9/5 (70)
(70) ParentCo's controlled group includes the following members. ParentCo owns all of the stock in each of the listed entities. Which entities can join ParentCo in a consolidated return?
-SubCoA, a manufacturer incorporated in India.
-SubCoB, a U.S. manufacturer.
-SubCoC, a U.S. S corporation.
-SubCoD, a U.S. partnership.
-SubCoE, a U.S. limited liability company (LLC).
-SubCoF, a U.S. manufacturer incorporated in Puerto Rico.
-SubCoG, a U.S. manufacturer that claims a deduction for its production activities (DPAD).
-SubCoH, a U.S. tax-exempt museum.
(Essay)
4.8/5 (75)
(75) The consolidated return rules are designed to allow a tax-neutral means by which to elect to file on a consolidated basis.
(True/False)
4.9/5 (76)
(76) Keep Corporation joined an affiliated group by merger in 2014. The group generated a consolidated 2014 NOL, and Keep's share of the loss was $50,000. Lacking an election by the parent to the contrary, Keep can carry the loss back to its separate 2012 return, and the parent can claim a tax refund.
(True/False)
4.8/5 (74)
(74) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
a. Increases stock basis of subsidiary
b. Decreases stock basis of subsidiary
c. No effect on stock basis of subsidiary
-Member's operating loss
(Short Answer)
4.7/5 (73)
(73) JuniorCo sells an asset to SeniorCo at a realized loss. That loss is not recognized by the group in the year of the sale, because of the:
(Multiple Choice)
4.8/5 (75)
(75) Match each of the following items with the appropriate description, indicating whether the item's treatment for financial accounting and Federal income tax purposes is the same or not.
a. Tax and book treatment is the same
b. Tax and book treatment differ
-Ownership level of parent at which a subsidiary can join the consolidated group.
(Short Answer)
4.9/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)