



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Gold, Silver, and Bronze constitute a Federal consolidated tax return group. Which of the members is responsible to pay the tax liability-the parent, the subsidiaries, or both? How are these tax-payable amounts determined? Hint: Use the term tax-sharing agreement in your answer.
(Essay)
4.8/5  (80)
(80) Which of the following entities is eligible to join in a Federal consolidated return?
(Multiple Choice)
4.9/5 (90)
(90) The calendar year Sterling Group files its Federal corporate income tax return on a consolidated basis. The group's Form 1120 is due on March 15, or September 15 if an extended due date is approved by the IRS.
(True/False)
4.8/5 (75)
(75) When negative adjustments are made to the stock basis of the subsidiary that exceed the basis as of the beginning of the tax year, a(n) account is created, rather than giving the parent a negative tax basis in the stock.
(Short Answer)
4.9/5 (79)
(79) A joint venture, taxed like a partnership, can join in a consolidated Federal income tax return.
(True/False)
4.9/5 (90)
(90) TopCo owns all of the stock of BottomCo. Both taxpayers are subject to the alternative minimum tax (AMT) this year for the first time, due to a dependence on accelerated MACRS deductions. The corporations incurred no intercompany transactions during the year. TopCo has a consolidation election in effect for the group.
If the affiliates were to file separate Forms 1120 this year, the following amounts would be reported.
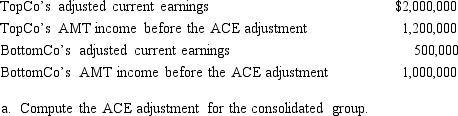 a. Comment on the effects of the consolidation election on the companies' AMT liabilities.
 (Essay)
4.8/5 (92)
(92) Which of the following statements is true with regard to intercompany transactions?
(Multiple Choice)
4.9/5 (78)
(78) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
a. Group item
b. Not a group item
-Interest income from Detroit School District bonds
(Short Answer)
4.8/5 (89)
(89) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return.
a. Advantage of consolidating
b. Disadvantage of consolidating
c. Neither an advantage nor a disadvantage
-Tax treatment of operating losses when the basis of the payor's stock is zero
(Short Answer)
4.8/5 (79)
(79) If one member sells an asset with a realized gain to another member of an affiliated group, any gain on the transaction is not recognized at that time; such a deferral applies the rule.
(Short Answer)
5.0/5 (68)
(68) Calendar year ParentCo purchased all of the stock of SubCo on January 1, 2013, for $500,000. SubCo produced a loss for 2013 of $150,000 and distributed cash of $25,000 to ParentCo. In 2014, SubCo generated a loss of $450,000; in 2015, it recognized net income of $90,000. What is ParentCo's capital gain or (loss) if it sells all of its SubCo stock to a nongroup member on January 1, 2016, for $150,000?
(Multiple Choice)
4.9/5 (78)
(78) The group of Parent Corporation, SubOne, and SubTwo has filed a consolidated return since 2013. The first two entities were incorporated in 2012, and SubTwo came into existence in 2013 through an asset spin-off from Parent. Taxable income computations for the members are shown below. None of the group members incurred any capital gain or loss transactions during 2012-2015, nor did they make any charitable contributions.
Describe the treatment of the group's 2014 consolidated NOL. Hint: Apply the offspring rule.
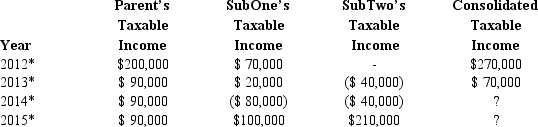 * Consolidated return year.
 (Essay)
4.9/5 (69)
(69) A Federal consolidated group reports a net operating loss for the year. How is this amount allocated to the various group members? Why is this allocation important?
(Essay)
4.8/5 (75)
(75) Members of the ABCD Federal consolidated group conduct various transactions with each other during the tax year. These include the purchase/sale of land and depreciable assets, the licensing of intangible assets, and the conduct of service arrangements. How does the tax law account for these intercompany items? In your answer, be sure to use the terms matching rule and acceleration rule at least once each.
(Essay)
4.9/5 (84)
(84) SubCo sells an asset to ParentCo at a realized gain. While ParentCo still holds the asset, SubCo leaves the consolidated group. As a result:
(Multiple Choice)
4.7/5 (79)
(79) Most of the Federal consolidated income tax return rules are found in detailed sections of the tax Regulations.
(True/False)
4.8/5 (72)
(72) Consolidated group members each must use the same tax year end, and all of the members must use the same tax accounting methods (e.g., LIFO or FIFO).
(True/False)
4.7/5 (83)
(83) In the year that the group terminates its consolidation election, a consolidated group's deferred gain from an
intercompany asset sale between affiliates is recognized in full, under the rule.
(Short Answer)
4.9/5 (77)
(77) Which of the following tax effects becomes more restrictive if an election is made to file a group's Federal corporate income tax returns on a consolidated basis?
(Multiple Choice)
4.8/5 (73)
(73) In computing consolidated taxable income, capital gains and losses are removed from the taxable incomes of the group members and determined on a group basis.
(True/False)
4.8/5 (62)
(62) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)