



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Which corporation is eligible to make the S election?

Free
(Multiple Choice)
4.8/5  (89)
(89) Correct Answer: Verified
B
Depreciation recapture income is a Schedule K item on the Form 1120S.
Free
(True/False)
4.9/5 (82)
(82) Correct Answer:Verified
VerifiedFalse
An S corporation can claim a deduction for its NOL carryovers.
Free
(True/False)
4.8/5 (66)
(66) Correct Answer:Verified
VerifiedFalse
On January 1, 2014, Kinney, Inc., an electing S corporation, holds $5,000 of AEP and $9,000 in AAA. Kinney has two shareholders, Eric and Maria, each of whom owns 500 shares of Kinney's stock. Kinney's 2014 taxable income is $6,000. Kinney distributes $6,000 to each shareholder on February 1, 2014, and distributes another $3,000 to each shareholder on September 1. How is Erin taxed on the distribution?
(Multiple Choice)
4.7/5 (86)
(86) Randall owns 800 shares in Fabrication, Inc., an S corporation in Moss Hill, Texas. In 2014, the basis in his stock is $30,000, before the adjustment for this year's losses. During 2014, Randall's share of the corporation's ordinary loss is $20,000, and his share of its capital loss is $15,000. How much can Randall deduct due to these losses?
(Multiple Choice)
4.8/5 (78)
(78) You are given the following facts about a 40% owner of an S corporation, and you are asked to prepare her ending stock basis. 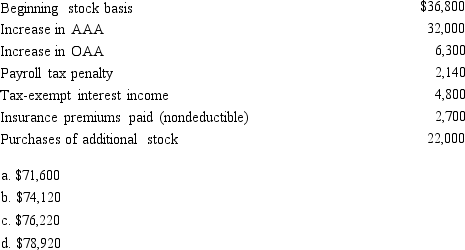
(Short Answer)
4.9/5 (93)
(93) All tax preference items flow through the S corporation, to be included in the shareholders' AMT calculations.
(True/False)
4.7/5 (82)
(82) Your client is a C corporation that would like to convert to S status. Advise this corporation with respect to minimizing any built-in gains tax.
(Essay)
4.9/5 (85)
(85) Claude Bergeron sold 1,000 shares of Ditta, Inc., an S corporation, for $12,000. He had owned the stock for three years and had a stock basis of $111,000 in the shares. Claude is single, and he is the original owner of the § 1244 stock shares. Calculate the appropriate tax treatment.
(Multiple Choice)
4.8/5 (69)
(69) A distribution of cash or other property by an S corporation to shareholders that does not exceed the balance of AAA during a one-year period following an S election termination receives special capital gain treatment.
(True/False)
4.7/5 (84)
(84) An S corporation is limited to a theoretical maximum of shareholders.
(Short Answer)
5.0/5 (77)
(77) An S shareholder's stock basis does not include a ratable share of S corporation liabilities.
(True/False)
4.8/5 (80)
(80) Which of the following reduces a shareholder's S corporation stock basis?
(Multiple Choice)
4.8/5 (74)
(74) Chris, the sole shareholder of Taylor, Inc., elects during 2014 to terminate the S election, effective January 1, 2015. As of the end of 2014, Taylor, Inc., holds AAA of $120,000 and OAA of $13,000. Chris receives a cash distribution of $130,000 on January 15, 2015. If his stock basis is $220,000 before the distribution, calculate Chris's taxable amount and his ending stock basis.
(Essay)
4.9/5 (66)
(66) Individuals Adam and Bonnie form an S corporation, with Adam contributing cash of $100,000 for a 50% interest, and Bonnie contributing appreciated ordinary income property with an adjusted basis of $20,000 and a fair market value of $100,000.
a. Determine Bonnie's initial basis in her stock, assuming that she receives a 50% interest.
b. The S corporation sells the property for $120,000. Determine Adam's and Bonnie's stock basis after the sale.
c. Determine Adam's and Bonnie's gain or loss if the company is liquidated.
(Essay)
4.9/5 (77)
(77) Arizona is a(n) property state for purposes of the S corporation requirements.
(Short Answer)
4.9/5 (83)
(83) An S shareholder's basis is decreased by distributions treated as being paid from AAA.
(True/False)
4.9/5 (77)
(77) An S corporation shareholder's stock basis includes his or her direct investments plus a ratable share of any corporate liabilities.
(True/False)
4.9/5 (79)
(79) A termination occurs on the day that a corporation to be an S corporation.
(Short Answer)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)