



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Shareholders owning a(n) of shares (voting and nonvoting) may
____________________ revoke an election.
(Short Answer)
4.9/5  (80)
(80) If a resident alien shareholder moves outside the U.S., the S election is terminated.
(True/False)
4.8/5 (81)
(81) Separately stated items are listed on Schedule of the Form 1120S.
(Short Answer)
4.9/5 (72)
(72) On January 1, Bobby and Alice own equally all of the stock of an electing S corporation called Prairie Dirt Delight. The dirt company has a $60,000 loss for a non-leap year. On the 200th day of the year, Bobby sells his one-half of the stock to his son, Saul. How much of the $60,000 loss, if any, is allocated to Bobby?
(Multiple Choice)
4.8/5 (82)
(82) For a new corporation, a premature S election may not be effective.
(True/False)
4.7/5 (76)
(76) Passthrough S corporation losses can reduce the basis in the shareholder's loan to the entity, but distributions do not reduce loan basis.
(True/False)
4.7/5 (77)
(77) Match the term with the proper response. There may be more than one responses for each term.
-OAA
(Multiple Choice)
4.9/5 (79)
(79) Grams, Inc., a calendar year S corporation is a manufacturer of widgets. Grams reports $20,000 DPGR and $15,000 of wages; its S corporation's QPAI is $5,000. Janet owns a 40% interest in the S corporation. All expenses that reduce DPGR are from wages, and all wages paid relate to DPGR. How much QPAI and wages are allocated to Janet?
(Multiple Choice)
4.8/5 (90)
(90) Gene Grams is a 45% owner of a calendar year S corporation during 2014. His beginning stock basis is $230,000, and the S corporation reports the following items.
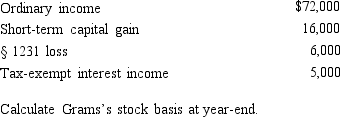
(Essay)
4.8/5 (88)
(88) An S corporation cannot be a shareholder in another corporation.
(True/False)
4.8/5 (93)
(93) An S corporation's LIFO recapture amount equals the excess of the inventory's value under
____________________ over the ____________________ value.
(Short Answer)
4.9/5 (93)
(93) An S corporation cannot incur a tax liability at the corporation level.
(True/False)
4.7/5 (83)
(83) Depletion in excess of basis in property causes a(n) adjustment to an S shareholder's basis.
(Short Answer)
4.9/5 (80)
(80) Any excess of S corporation losses or deductions over the shareholder's combined stock and debt basis is suspended until there is a subsequent stock or debt basis.
(True/False)
4.9/5 (77)
(77) An S corporation reports a recognized built-in gain of $110,000 and taxable income of $98,000. The company carries an $8,000 NOL carryforward from a C corporation year, and a $7,000 business credit carryforward from a C corporation year. The built-in gains tax liability is:
(Multiple Choice)
4.7/5 (82)
(82) Distribution of loss property by an S corporation to a shareholder generally should be .
(Short Answer)
4.8/5 (77)
(77) An S shareholder who dies during the S corporation tax year must report his or her share of the pro rata income (loss) items up to the date of death, on the final individual tax return.
(True/False)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)