



 Chat with AI
Exam 3: Corporations: Special Situations


Campbell, Inc., a calendar year corporation that was created in February 2010, has gross receipts as follows:
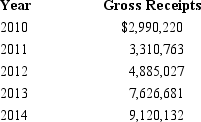 Does Campbell qualify for the small corporation exemption for each year (2010 through 2015)?
 (87)
 Verified
Since Campbell is a new corporation in 2010, the company is automatically exempt from the corporate AMT under the small corporation exemption regardless of gross receipts. Campbell also qualifies for the exemption in 2011 as 2010 gross receipts do not exceed $5 million.
Campbell calculates average gross receipts in the later years to determine whether the small business exemption is available. These calculations for the subsequent tax years are as follows:
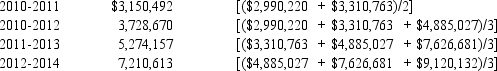 Campbell qualifies for the exemption in 2012, since the average gross receipts for 2010-2011 do not exceed $7.5 million. Likewise, Campbell continues to qualify for the exemption in 2013, 2014, and 2015, since the average gross receipts for each preceding three-year period (2010-2012, 2011-2013, and 2012-2014, respectively) do not exceed $7.5 million.
Passive activity losses of certain closely held corporations and personal service corporations are not tax preferences.
(96) VerifiedTrue
Rose, Inc., an S corporation, has taxable income of $14 million in 2014. Assume there are two shareholders, each in the 35% tax bracket. What is the maximum total DPAD tax savings for the S corporation shareholders?
(73) Ohio Corporation, a calendar year taxpayer, has a beginning balance in accumulated E & P of $3.5 million and current earnings of $1 million. If Ohio can justify accumulations for the needs of the business of $4.1 million, its accumulated earnings credit for ATI purposes is:
(80) One of the components of DPGR is qualified production property (QPP). The QPP must be manufactured, produced, grown, or extracted entirely within the U.S.
(71) The objective of the AMT is to force taxpayers that are more profitable than their taxable income reflects to pay additional income taxes.
(81) Yvonne Corporation manufactures and sells ceramic dinnerware. The company also sells dinnerware that is purchased from unrelated foreign producers. During the 2014 tax year, Yvonne had a U. S. profit of $1.3 million (QPAI) and a loss from the imported merchandise of $200,000. What is Yvonne's DPAD?
(86) The percentage applicable for computing the DPAD will ultimately increase to 12%.
(67) The penalty tax rate for the AET and PHC is the highest rate applicable to individual taxpayers.
(77) A small corporation with unused minimum tax credits may use what percentage of regular tax as a minimum credit in 2014?
(89) In 2014, Job Corporation, a calendar year taxpayer, has AMTI (before adjustment for adjusted current earnings) of $7 million. If Job Corporation's ACE is $16 million, its tentative minimum tax for 2014 is:
(83) The accumulated earnings credit for a personal service corporation is the greater of $150,000 or the current E & P for the year needed to meet the reasonable needs of the business.
(94) During 2014, Red Corporation (a calendar year taxpayer) has $4,000,000 of taxable income and the following transactions: AMTI (not including adjusted current earnings) $5,000,000
Adjusted current earnings 8,000,000
Red Corporation's alternative minimum tax (AMT) for 2014 is:
(83) In each of the following independent situations, determine the DPAD for 2014 for the corporation involved.
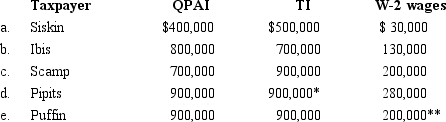 *Does not include a $120,000 NOL carryover from the prior year.
**Only $60,000 relates directly to manufacturing activities.
*Does not include a $120,000 NOL carryover from the prior year.
**Only $60,000 relates directly to manufacturing activities. (74) Which of the following would not be a positive tax preference item in 2014?
(80) Fewer corporations are subject to the AMT than to the domestic production activities deduction.
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)