



 Chat with AI
Exam 19: Family Tax Planning


The special use valuation method of § 2032A is available for valuing transfers by gift.

 (81)
 Verified
False
In April 2012, Jacob gives his mother, Grace, real estate (basis of $500,000; fair market value of $900,000). Jacob paid no Federal gift tax on the transfer. Before Grace's death in March 2013, she makes $20,000 in capital improvements to the property. The real estate is worth $910,000 when Grace dies. What is the income tax basis of the property to Grace's heir under each of the following assumptions?
a. The heir is Jacob's wife.
b. The heir is Grace's brother (i.e., Jacob's uncle).
(84) Verified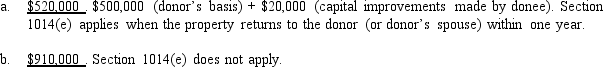
In planning for the use of § 6166, what are several steps that can be taken to aid the owner of a small business while he or she is alive? In this connection consider the following.
a. The number of owners and the amount of ownership in the business.
b. The nonqualifying assets held by the owner.
c. Aggregation of qualifying interest.
(72) Verifieda. A shifting of ownership interests might enable the taxpayer to comply with the 20% (or more) ownership test or the 45 (or fewer) number of owners (partners or shareholders) test. For example, if the taxpayer bought out another owner, this would increase his ownership interest and decrease the number of owners.
b. Getting rid of nonqualifying assets (e.g., real estate, other securities, life insurance) facilitates meeting the morethan35% test. However, gifts made within three years of a donor's death will be brought back into the gross estate for testing purposes.
c. By increasing the ownership interest in any one business (so as to meet the 20%-or-more test), this permits its aggregation with others in satisfying the more-than-35% test.
At the time of his death, Fred held some notes receivable for loans he made to his two daughters and the payment of which he forgives in his will. The amount to be included in Fred's gross estate as to these notes is not affected by his forgiveness.
(87) If a stock redemption is to be carried out, a cross-purchase type of buy and sell agreement cannot be involved.
(82) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a. Increases the probate estate
b. Decreases the probate estate
c. Has no effect on the probate estate
-Paid a gift tax on a gift made two years prior to death of the donor.
(86) If depreciable property is transferred by gift, any depreciation recapture potential carries over to the donee.
(78) The election of § 2032 (alternate valuation date) for estate tax purposes:
(71) In a typical estate freeze involving family limited partnerships established by parents for their children:
(78) Ramon sells a parcel of land (basis of $100,000; fair market value of $300,000) to his church. As long as the selling price does not exceed $100,000, Ramon recognizes no gain on the sale.
(73) Match each statement with a correct choice. Choices may be used more than once.
a. Increases the probate estate
b. Decreases the probate estate
c. Has no effect on the probate estate
-Brother purchased land listing ownership with decedent as tenants in common.
(74) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a. Revocable trusts
b. Income in respect of a decedent (IRD)
c. Conservation easement
d. Discretionary extension of time to pay estate tax (§ 6161)
e. Estate freeze-corporations
f. Extension of time involving interest in closely held business (§ 6166)
g. Special use valuation as to certain realty (§ 2032A)
h. Depreciation recapture potential eliminated
i. Alternate valuation date (§ 2032)
j. Election to split gifts (§ 2513)
k. No correct choice is given
-No step-up in basis at death.
(69) To prove successful in freezing the value of an interest in a family limited partnership (FLP), which, if any, of the following techniques is desirable?
(73) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a. Increases the probate estate
b. Decreases the probate estate
c. Has no effect on the probate estate
-Purchased a certificate of deposit listing daughter as the beneficiary under a payable on death designation.
(81) When will the price specified in a buy and sell agreement control the value used for estate tax purposes?
(80) Zane makes a gift of stock in Cerulean Company to family members. Cerulean is a closely held corporation that is not traded on any exchange. To hedge on the value used for gift tax purposes, Zane also donates some of the stock to a qualified charity. Explain the advantage of this approach.
(85) Buy and sell agreements can be used to help solve the estate tax valuation problems involved in the transfer by death of an interest in a small business.
(77) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a. Step-up in basis
b. Step-down in basis
c. Gift of installment notes receivable
d. Gift of property that has § 1245 or § 1250 potential for recapture of depreciation
e. Donor's basis on date of gift (appreciated property given, no gift tax due)
f. The amount of the deceased spouse's taxable estate does not change
g. Fair market value on date of gift
h. Expected surviving spouse is in good health and 10 years younger
i. No income tax consequences to the beneficiary
j. Income in respect of a decedent (IRD)
k. No correct choice is given
-Surviving spouse disclaims inheritance in favor of bypass amount.
(74) One way to dispute the existence of large goodwill is to argue that the decedent was not a key person in the operation of the business.
(97) Eric, age 80, has accumulated about $6 million in net assets. Among his assets are the following marketable securities held as investments. 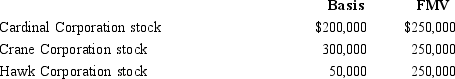 Eric would like to donate (either by lifetime or testamentary transfer) $250,000 in value to his church. In addition, to consummate a land deal, he needs $250,000 in cash. Looking solely to tax: considerations and using only the assets described above, Eric's best choice is to:
 (86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)