



 Chat with AI
Exam 19: Family Tax Planning

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


In 2014, Donna's father dies and leaves her the family farm. The farm has a current use value of $4,000,000 and a best use value of $4,500,000. If the § 2032A election is made, the farm should be included in the father's gross estate at a value of:
(Multiple Choice)
4.8/5  (78)
(78) A qualifying heir can make the § 2032A special valuation election only if he is not sure that he will keep the property for the full 10 years.
(True/False)
4.8/5 (60)
(60) Whether an organization is a qualified charity for estate tax purposes depends on its status on the date the will is executed and not when the transfer takes place.
(True/False)
4.9/5 (79)
(79) How can a disclaimer by an heir increase the charitable deduction allowed a decedent? Is such a disclaimer always wise? Explain.
(Essay)
4.7/5 (101)
(101) Curt owns the following assets which he gives to his daughter Carla. No gift tax results. Fair Market
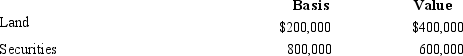 Both items have been held by Curt as an investment for more than one year. If Carla immediately sells these assets for $1 million ($400,000 + $600,000), she recognizes:
 (Multiple Choice)
4.8/5 (74)
(74) Chloe makes a gift of stock in Snipe Corporation, which is not closely held but is traded in an over-the-counter market. The transactions involving this stock that occurred closest to the date of gift took place five trading days before (mean selling price of $130) and seven days after (mean selling price of $140). Determine the fair market value of the Snipe stock on the date of the gift.
(Essay)
4.8/5 (69)
(69) One of the objectives of establishing a program of lifetime giving is to transfer assets that are likely to appreciate in value. Examples include life insurance policies, valuable collections (e.g., art works), vacation homes, and undeveloped real estate. However, such gifts could cause economic problems for certain donees. Explain why.
(Essay)
4.9/5 (80)
(80) In 1990, Mia, a resident of New Jersey, purchases realty for $600,000 listing title as "Mia and Ella, joint tenants with right of survivorship." In 2013, Mia predeceases Ella when the realty is worth $3,000,000. Ella's income tax basis in the property is:
(Multiple Choice)
4.8/5 (79)
(79) Wesley has created an irrevocable trust: life estate to Eve, remainder to Ernest upon Eve's death. In using the IRS valuation tables, what information is needed to determine the value of Eve's life estate?
(Essay)
4.9/5 (68)
(68) In each of the following independent situations, describe the effect of the disclaimer procedure on Ray's taxable estate. In this regard, advise as to how much should be disclaimed, by whom, and whether a disclaimer should be made, for the death in 2013.
a. Ray's will leaves $6,000,000 to his adult son and the remainder ($500,000) to Amy (Ray's surviving wife).
b. Ray's will leaves $7,000,000 to Amy (Ray's surviving wife) and the remainder ($3,000,000) to his adult son.
c. Ray's will leaves $6,000,000 to Amy (Ray's surviving spouse) and the remainder ($500,000) to a qualified charity.
(Essay)
4.8/5 (79)
(79) If the special use valuation method of § 2032A is elected and certain continuing requirements are not satisfied, recapture occurs. What is the amount of recapture and upon whom is it imposed?
(Essay)
4.8/5 (79)
(79) Which of the following procedures carried out will reduce both Mary's future gross estate and her probate estate?
(Multiple Choice)
4.8/5 (76)
(76) Match each statement with a correct choice. Choices may be used more than once.
a. Increases the probate estate
b. Decreases the probate estate
c. Has no effect on the probate estate
-Spouse purchased residence listing ownership as tenants by the entirety.
(Short Answer)
4.8/5 (98)
(98) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a. Increases the probate estate
b. Decreases the probate estate
c. Has no effect on the probate estate
-Made lifetime gifts.
(Short Answer)
4.9/5 (69)
(69) At the time of Elijah's death, he owned stock in Grey Corporation. The stock is traded on a local exchange with the most recent selling prices as follows.
Per Share Price
Four trading days prior to Elijah's death $120
Six trading days after Elijah's death 100
Presuming no alternate valuation date election, Elijah's gross estate should include a per share value of:
(Multiple Choice)
4.8/5 (85)
(85) Neither the transfer by gift or by death avoids the recognition (for income tax purposes) of any deferred interest on U.S. savings bonds.
(True/False)
4.8/5 (77)
(77) The election by an estate of § 2032A (special use valuation as to real estate) or § 2032 (the alternate valuation date) will have no effect on the income tax basis of the property received by the heirs.
(True/False)
4.9/5 (84)
(84) In 2011, Sophia sold real estate (adjusted basis of $500,000) for $1,500,000. Under the terms of the sale, she received two notes of $750,000 each, with 9% interest provided. One note is due in 2012 and the other in 2013. She did not elect out of the installment method of recognizing gain. In 2012 and before the first note matures, Sophia gives both notes to her adult children. At this time, the notes are worth a total of $1,400,000. Disregarding the interest element, a tax result of these transactions is:
(Multiple Choice)
4.8/5 (93)
(93) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a. Revocable trusts
b. Income in respect of a decedent (IRD)
c. Conservation easement
d. Discretionary extension of time to pay estate tax (§ 6161)
e. Estate freeze-corporations
f. Extension of time involving interest in closely held business (§ 6166)
g. Special use valuation as to certain realty (§ 2032A)
h. Depreciation recapture potential eliminated
i. Alternate valuation date (§ 2032)
j. Election to split gifts (§ 2513)
k. No correct choice is given
-Living trusts.
(Short Answer)
4.9/5 (87)
(87) In April 2013, Tim makes a gift of real estate (basis of $900,000; fair market value of $800,000) to his aunt. After the gift, the aunt makes $50,000 worth of capital improvements to the property. The aunt dies in March 2014, when the property is worth $840,000. Under the aunt's will, the realty passes to Tim. Tim's income tax basis in the property is:
(Multiple Choice)
4.7/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)