



 Chat with AI
Exam 19: Family Tax Planning

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


How could the election of the alternate valuation date (§ 2032) increase a decedent's marital deduction?
(Essay)
4.8/5  (74)
(74) In arriving at the valuation of assets for estate tax purposes, the location of the property is irrelevant.
(True/False)
4.9/5 (79)
(79) One of the advantages of an estate freeze is that the preferred stock is not included in the gross estate of the donor.
(True/False)
4.9/5 (85)
(85) Dustin owns all of the stock of Gold Corporation which includes both common and preferred shares. The preferred stock is noncumulative, has no redemption date, and possesses no liquidation preference. In 1995, Dustin makes a gift to his adult children of all of the common stock. He dies in 2013 still owning the preferred stock. The value of the Gold stock on the relevant dates is: 1995 2013
Preferred $ 400,000 $ 500,000
Common 3,000,000 5,000,000
One of the tax consequences of this estate freeze is:
(Multiple Choice)
4.8/5 (87)
(87) In making a choice as to which assets to use in carrying out a program of lifetime giving, comment on each of the following assets.
a. U.S. savings bonds.
b. Installment notes receivable.
c. Property subject to recapture of depreciation.
(Essay)
4.8/5 (78)
(78) A donee's income tax basis in property received as a gift will include any gift tax paid by the donor.
(True/False)
4.9/5 (76)
(76) In connection with a traditional IRA that is transferred at death, comment on the tax implications of each of the following.
a. The beneficiary does nothing, and a distribution occurs.
b. The beneficiary retitles the IRA as a "retirement IRA."
c. The additional tax advantages enjoyed when the beneficiary is the surviving spouse.
(Essay)
5.0/5 (74)
(74) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a. Step-up in basis
b. Step-down in basis
c. Gift of installment notes receivable
d. Gift of property that has § 1245 or § 1250 potential for recapture of depreciation
e. Donor's basis on date of gift (appreciated property given, no gift tax due)
f. The amount of the deceased spouse's taxable estate does not change
g. Fair market value on date of gift
h. Expected surviving spouse is in good health and 10 years younger
i. No income tax consequences to the beneficiary
j. Income in respect of a decedent (IRD)
k. No correct choice is given
-Donee's basis for loss.
(Short Answer)
4.8/5 (66)
(66) At the time of her death in 2012, Carol owns 60% of the stock in Drab Corporation, with the balance of the stock held by family members. Drab Corporation's total profits for the past five years are $3,200,000, and the book value of its stock is $2,400,000. If 8.5% is an appropriate rate of return and goodwill exists, what is a possible value for the stock to be included in Carol's gross estate?
(Essay)
4.9/5 (84)
(84) Using investments worth $3 million, Keith establishes a trust, life estate to Melinda, remainder to Dana.
a. Has Keith made one gift or two gifts?
b. How does your answer affect the Federal transfer tax liabilities?
(Essay)
4.9/5 (61)
(61) Under proper circumstances, a disclaimer by an heir may increase the charitable deduction allowed a decedent.
(True/False)
4.8/5 (87)
(87) Cost and time are usually saved by passing ownership to out-of-state real estate by death rather than by gift.
(True/False)
4.9/5 (82)
(82) Jim makes a gift of property (basis of $800,000; fair market value of $600,000) to his wife, Molly. Six months later Molly dies, and under her will, the property (now worth $700,000) returns to Jim. Jim's income tax basis in the property now is $800,000.
(True/False)
4.9/5 (84)
(84) Barney creates a trust, income payable to Madison for five years, remainder to Emma. Emma is Barney's daughter (and a single parent), and Madison is his 19-year old granddaughter. What might be the justification for this type of trust?
(Essay)
4.9/5 (90)
(90) Mason is the founder of Garnet Corporation and owns all of its stock, both common and preferred. The preferred stock is noncumulative and possesses no preferential rights as to liquidation. In 1996 and when the common stock has a value of $3,200,000, Mason gives it to his adult children. He retains the preferred stock which, at this time, has a value of $500,000. In 2013, Mason dies. Values on the date of death are: $4,500,000 for the common stock and $650,000 for the preferred.
a. What is the amount of the gift Mason makes in 1996?
b. How much as to Garnet Corporation is included in Mason's gross estate in 2013?
(Short Answer)
4.9/5 (72)
(72) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a. Use IRS valuation tables
b. Blockage rule
c. Special use value
d. Best or most suitable use value
e. Cost of going public
f. Replacement cost of a comparable contract
g. Portion of a deceased spouse's share of community property that passes to a surviving spouse
h. Cross-purchase buy and sell agreement
i. Entity buy and sell agreement
j. Bypass amount
k. No correct choice is given
-Surviving owners agree to purchase withdrawing owner's interest.
(Short Answer)
4.8/5 (84)
(84) Ingrid's projected adjusted gross estate is as follows.
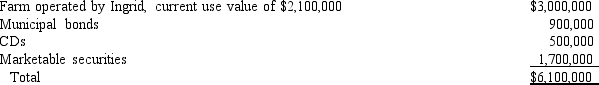 a. Presuming that Ingrid expects her estate to elect the special use valuation of § 2032A, what do you suggest?
b. What could go wrong?
a. Presuming that Ingrid expects her estate to elect the special use valuation of § 2032A, what do you suggest?
b. What could go wrong? (Essay)
4.9/5 (74)
(74) Passing installment notes by death will not avoid any income tax on the deferred gain.
(True/False)
4.9/5 (77)
(77) A decedent owned 25% of the voting stock of Siskin Corporation. Siskin has 53 shareholders. The decedent's estate cannot qualify for the § 6166 election.
(True/False)
4.9/5 (90)
(90) Richard and Marie are joint tenants in a tract of land. Upon Richard's prior death, Marie's income tax basis in the land does not change.
(True/False)
4.7/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)