



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Double weighting the sales factor effectively decreases the corporate income tax burden on taxpayers based in the state, such as entities with in-state headquarters.

Free
(True/False)
4.8/5  (78)
(78) Correct Answer: Verified
True
List at least five items that are included in the payroll factor of a typical state. Consider all forms of compensation that an employee might receive. Apply the general UDITPA rules.
Free
(Essay)
4.9/5 (74)
(74) Correct Answer:Verified
VerifiedThe following items, among others, are included in the payroll factor.
-Wages
-Salary
-Commissions
-Fees
-Other forms of compensation for services
-Lodging, board, and other benefits that constitute Federal gross income
-All states exclude payments for services made to independent contractors
-Many states exclude § 401(k) deferrals and other retirement contributions
-A few states exclude compensation paid to corporate officers
Several states allow the S corporation to file a(n) income tax return, usually in the form of a state-by-state spreadsheet, on behalf of its out-of-state shareholders.
Free
(Short Answer)
4.9/5 (80)
(80) Correct Answer:Verified
Verifiedcomposite
block
Typically, a sales/use tax is applied to a retail sale of ____________________ property.
(Short Answer)
4.8/5 (86)
(86) Troy, an S corporation, is subject to tax only in State A. On Schedule K of its Federal Form 1120S, Troy reported ordinary income of $2,000,000 from its business, municipal bond interest of $150,000, taxable interest of $150,000, and charitable contributions of $300,000. A does not recognize S status, but it does follow the Federal provisions with respect to the determination of taxable income for a corporation. Determine Troy's A taxable income.
(Essay)
4.8/5 (82)
(82) Sales/use tax nexus is established for the taxpayer by the sales-solicitation activities of an independent contractor acting on the taxpayer's behalf.
(True/False)
4.9/5 (70)
(70) S corporations flow-through income amounts to its shareholders, and most states require a withholding of shareholder taxes on the allocated amounts.
(True/False)
5.0/5 (77)
(77) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a. Taxable
b. Not taxable
-A garment purchased for resale.
(Short Answer)
4.9/5 (77)
(77) Typical indicators of income-tax nexus include the presence of customers in the state.
(True/False)
4.8/5 (91)
(91) Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses.
a. Addition modification
b. Subtraction modification
c. No modification
-Treasury Bond interest income.
(Short Answer)
4.7/5 (79)
(79) A unitary group of entities files a combined return that includes all of the affiliates' income and apportionment data.
(True/False)
4.9/5 (80)
(80) Allocation is a method under which a corporation's income is directly assigned to the specific states where the income is derived.
(Short Answer)
4.9/5 (69)
(69) José Corporation realized $900,000 taxable income from the sales of its products in States X and Z. José's activities in both states establish nexus for income tax purposes. José's sales, payroll, and property among the states include the following. 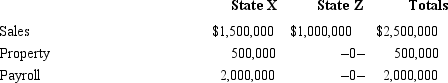 X utilizes an equally weighted threefactor apportionment formula. How much of José's taxable income is apportioned to X?
 (Multiple Choice)
4.9/5 (94)
(94) The model law relating to the assignment of income among the states for corporations is:
(Multiple Choice)
4.7/5 (93)
(93) By making a water's edge election, the multinational taxpayer can limit the reach of unitary principles to the apportionment factors and income of its U.S. and E.U. affiliates.
(True/False)
4.7/5 (76)
(76) José Corporation realized $900,000 taxable income from the sales of its products in States X and Z. José's activities in both states establish nexus for income tax purposes. José's sales, payroll, and property among the states include the following. 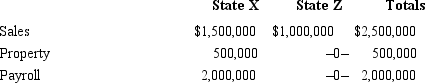 Z utilizes a doubleweighted sales factor in its threefactor apportionment formula. How much of José's taxable income is apportioned to Z?
 (Multiple Choice)
4.7/5 (83)
(83) In most states, a limited liability company (LLC) is subject to the state income tax:
(Multiple Choice)
4.9/5 (77)
(77) In determining a corporation's taxable income for state income tax purposes, which of the following does not constitute a subtraction from Federal income?
(Multiple Choice)
4.8/5 (92)
(92) Match each of the following items with the appropriate description, in applying the P.L. 86-272 definition of solicitation.
a. More than solicitation, creates nexus
b. Solicitation only, no nexus created
-Purchasing ads that show up on search-result screens for internet browsers.
(Short Answer)
4.9/5 (75)
(75) Trayne Corporation's sales office and manufacturing plant are located in State X. Trayne also maintains a manufacturing plant and sales office in State W. For purposes of apportionment, X defines payroll as all compensation paid to employees, including elective contributions to § 401(k) deferred compensation plans. Under the statutes of W, neither compensation paid to officers nor contributions to § 401(k) plans are included in the payroll factor. Trayne incurred the following personnel costs. 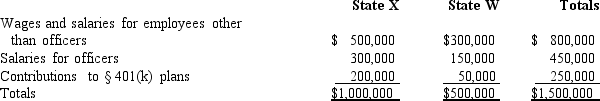 Trayne's payroll factor for State X is:

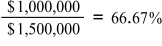
Trayne's payroll factor for State X is:
(Short Answer)
4.9/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)