



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


A taxpayer has nexus with a state for sales and use tax purposes if it has a physical presence in the state.
(True/False)
4.9/5  (84)
(84) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a. Taxable
b. Not taxable
-Earthmoving equipment used by the purchaser in construction business.
(Short Answer)
5.0/5 (80)
(80) Cruz Corporation owns manufacturing facilities in States A, B, and C. A uses a three-factor apportionment formula under which the sales, property and payroll factors are equally weighted. B uses a three-factor apportionment formula under which sales are double-weighted. C employs a single-factor apportionment factor, based solely on sales. Cruz's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows.
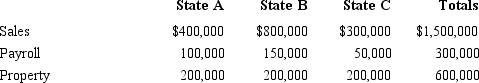 Cruz's apportionable income assigned to C is:
 (Multiple Choice)
4.8/5 (74)
(74) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a. Taxable
b. Not taxable
-Textbook purchased by a State University student.
(Short Answer)
4.9/5 (71)
(71) Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses.
a. Addition modification
b. Subtraction modification
c. No modification
-Deduction for advertising expenditures.
(Short Answer)
4.8/5 (87)
(87) Boot Corporation is subject to income tax in States A and B. Boot's operations generated $200,000 of apportionable income, and its sales and payroll activity and average property owned in each of the states is as follows. 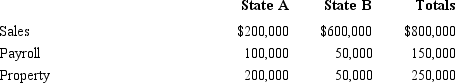 How much more (less) of Boot's income is subject to A income tax if, instead of using an equallyweighted threefactor apportionment formula, A uses a formula with a double-weighted sales factor?
 (Multiple Choice)
4.8/5 (78)
(78) Britta Corporation's entire operations are located in State A. Eighty percent ($800,000) of Britta's sales are made in A and the remaining sales ($200,000) are made in State B. B has not adopted a corporate income tax. If A has adopted a throwback rule, the numerator of Britta's A sales factor is:
(Multiple Choice)
4.8/5 (74)
(74) Condor Corporation generated $450,000 of state taxable income from selling its product in States A and B. For the taxable year, the corporation's activities within the two states were as follows.
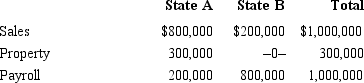 Condor has determined that it is subject to tax in both A and B. Both states utilize a three-factor apportionment formula that equally weights sales, property, and payroll. The rates of corporate income tax imposed in A and B are 5% and 3%, respectively. Determine Condor's state income tax liability.
 (Essay)
4.9/5 (73)
(73) In most states, legal and accounting services are exempt from the sales/use tax base.
(True/False)
4.8/5 (71)
(71) Your client, Hamlin Industries, wants to reduce its overall state/local income tax liability. Hamlin holds income- producing assets of various types, including tangible personal property, rental land and buildings, and high-yield stocks and bonds. You assess the asset portfolio and conclude that only the investment portfolio is "portable" and available for relocation at this time. What device might Hamlin use in a restructuring of its operations to achieve the desired tax result? Be specific.
(Essay)
4.8/5 (79)
(79) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a. Taxable
b. Not taxable
-Computer equipment purchased by a charity.
(Short Answer)
4.7/5 (82)
(82) Guilford Corporation is subject to franchise tax in State Z. The tax is imposed at a rate of 2.5% of the taxpayer's net worth that is apportioned to the state by use of a two factor (sales and property equally weighted) formula. The property factor includes real and tangible personal property, valued at net book value at the end of the taxable year. Sixty percent of Guilford's sales are attributable to Z, and $200,000 of the net book value of Guilford's tangible personal property is located in Z. Determine the Z franchise tax payable by Guilford this year, given the following end-of-the year balance sheet.
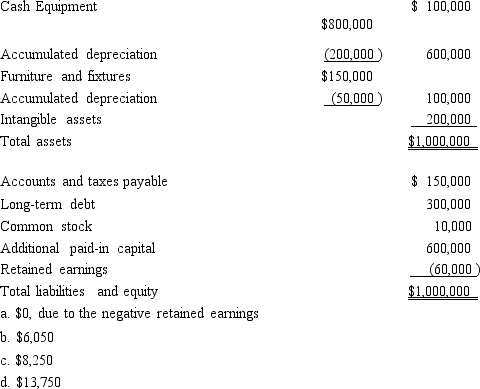
(Short Answer)
4.8/5 (80)
(80) Ramirez Corporation is subject to tax only in State A. Ramirez generated the following income and deductions. 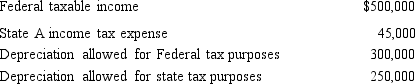 Federal taxable income is the starting point in computing A taxable income. State income taxes are not deductible for A tax purposes. Ramirez's A taxable income is:
 (Multiple Choice)
4.8/5 (76)
(76) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its A headquarters to a customer in B. This activity is not sufficient for General to create nexus with B. State A applies a throwback rule, but State B does not. In which state(s) will the sale be included in the sales factor numerator?
(Multiple Choice)
4.9/5 (75)
(75) Sylvia spends time working at the offices of her employer as a consultant to clients who are located in three different U.S. states. To which state(s)' payroll factor(s) is Sylvia's compensation assigned? Apply the general UDITPA rules.
(Essay)
4.8/5 (84)
(84) Most states begin the computation of corporate taxable income with an amount from the Federal income tax return.
(True/False)
5.0/5 (71)
(71) Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses.
a. Addition modification
b. Subtraction modification
c. No modification
-Dividend income from P & G stock held.
(Short Answer)
4.8/5 (78)
(78) P.L. 86-272 (does/does not) create nexus when the sales representative approves a sale at the customer's location.
(Short Answer)
4.7/5 (96)
(96) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)