



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


The benefits of a passive investment company typically include:
(Multiple Choice)
4.8/5  (78)
(78) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a. Taxable
b. Not taxable
-A new auto purchased in Europe and shipped by the driver to her home state in the U.S.
(Short Answer)
4.8/5 (79)
(79) Under P.L. 86-272, the taxpayer is exempt from state taxes on income resulting from the mere solicitation of orders for the sale of stocks and bonds.
(True/False)
5.0/5 (68)
(68) Hill Corporation is subject to tax only in State X. Hill generated the following income and deductions. State income taxes are not deductible for X income tax purposes.
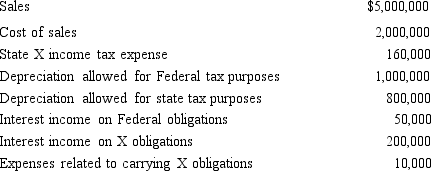 a. The starting point in computing the State X income tax base is Federal taxable income. Derive this amount.
b. Determine Hill's X taxable income, assuming that interest on X obligations is exempt from State X income tax.
c. Determine Hill's taxable income, assuming that interest on X obligations is subject to State X income tax.
a. The starting point in computing the State X income tax base is Federal taxable income. Derive this amount.
b. Determine Hill's X taxable income, assuming that interest on X obligations is exempt from State X income tax.
c. Determine Hill's taxable income, assuming that interest on X obligations is subject to State X income tax.
(Essay)
4.7/5 (83)
(83) All of the U.S. states use an apportionment formula based on the sales, property, and payroll factors.
(True/False)
4.8/5 (71)
(71) Parent and Junior form a unitary group of corporations. Parent is located in a state with an effective tax rate of 3%, while Junior's effective tax rate is 9%. Acting in concert to reduce overall tax liabilities, the group should:
(Multiple Choice)
4.9/5 (91)
(91) The individual seller of a used auto should collect and remit sales tax to the state.
(True/False)
4.9/5 (75)
(75) You are completing the State A income tax return for Quaint Company, LLC. Quaint operates in various states, showing the following results.
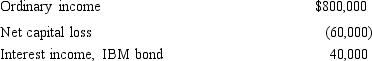 In A, all interest is treated as business income. A uses a salesonly apportionment factor. Compute Quaint's A
taxable income.
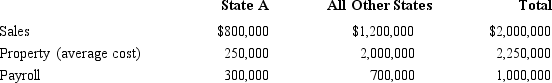
In A, all interest is treated as business income. A uses a salesonly apportionment factor. Compute Quaint's A
taxable income.
(Essay)
4.8/5 (64)
(64) The typical local property tax falls on both an investor's principal residence and her stock portfolio.
(True/False)
4.9/5 (74)
(74) In the broadest application of the unitary theory, the U.S. unitary business files a combined tax return using factors and income amounts for all affiliates:
(Multiple Choice)
4.8/5 (83)
(83) Typically exempt from the sales/use tax base is the purchase of clothing from a neighbor's "garage sale."
(True/False)
4.8/5 (79)
(79) Bobby and Sally work for the same employer, Wooster Manufacturing, which makes brushes for artists and painters. Bobby spends onehalf of his time managing the company's speculative investment portfolio, and the other half working with the corporate treasurer in securing cash flow for manufacturing payrolls. Sally is a foreman in the brush factory.
How are the salaries paid to Bobby and Sally treated in computing Wooster's payroll factor? Apply the general UDITPA rules.
(Essay)
4.8/5 (81)
(81) When a is in effect, out-of-state sales that are not subject to tax in the destination state are pulled back into the sales factor numerator of the origination state.
(Short Answer)
4.8/5 (67)
(67) Which of the following is not immune from state income taxation, even if P.L. 86-272 is in effect?
(Multiple Choice)
4.8/5 (84)
(84) In states, a(n) election permits a multinational corporation to elect to limit the reach of the state's taxing jurisdiction to activities occurring within the boundaries of the United States.
(Short Answer)
4.8/5 (71)
(71) Adams Corporation owns and operates two manufacturing facilities, one in State X and the other in State Y. Due to a temporary decline in the corporation's sales, Adams has rented 20% of its Y facility to an unaffiliated corporation. Adams generated $1,000,000 net rental income and $5,000,000 income from manufacturing. Adams is incorporated in Y. For X and Y purposes, rental income is classified as allocable nonbusiness income. By applying the statutes of each state, Adams determined that its apportionment factors are .65 for X and .35 for Y.
Adams's income attributed to X is:
(Multiple Choice)
4.8/5 (76)
(76) A service engineer spends 80% of her time maintaining the employer's productive business property and 20% maintaining the employer's nonbusiness rental properties. This year, her compensation totaled $90,000. The payroll factor assigns $90,000 to the state in which the employer is based.
(True/False)
4.7/5 (77)
(77) Under P.L. 86-272, which of the following transactions by itself would create nexus with a state?
(Multiple Choice)
5.0/5 (75)
(75) describe(s) the degree of business activity that must be present before a taxing jurisdiction has the right to impose a tax on an outofstate entity's income.
(Short Answer)
5.0/5 (81)
(81) Most of the U.S. states have adopted an alternative minimum tax, similar to the Federal system, in taxing the income of corporations.
(True/False)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)