



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses.
a. Addition modification
b. Subtraction modification
c. No modification
-Federal depreciation deduction in excess of state amount.
(Short Answer)
5.0/5  (84)
(84) P.L. 86-272 (does/does not) create nexus when the seller inserts advertising flyers into the Sunday newspaper that is sold in the state.
(Short Answer)
4.7/5 (80)
(80) Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses.
a. Addition modification
b. Subtraction modification
c. No modification
-Federal general business credit.
(Short Answer)
4.9/5 (82)
(82) Typically exempt from the sales/use tax base is the purchase of prescription medicines by an individual.
(True/False)
4.9/5 (80)
(80) Typically included in the sales/use tax base is the purchase of tablet computers and cell phone equipment by a large manufacturing firm, whose sales force uses the items.
(True/False)
4.9/5 (74)
(74) Hopper Corporation's property holdings in State E are as follows. 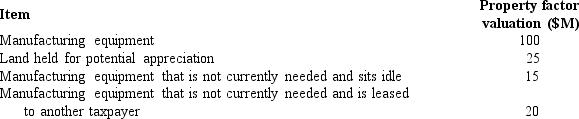 Compute the numerator of Hopper's E property factor.
 (Multiple Choice)
4.9/5 (79)
(79) Under P.L. 86-272, which of the following transactions by itself would create nexus with a state?
(Multiple Choice)
4.9/5 (75)
(75) Your supervisor has shifted your responsibilities from the Federal corporate income tax to a multistate corporate income tax practice. In what areas might your Federal income tax knowledge also be applicable in your new assignment?
(Essay)
4.8/5 (75)
(75) Net Corporation's sales office and manufacturing plant are located in State X. Net also maintains a manufacturing plant and sales office in State W. For purposes of apportionment, X defines payroll as all compensation paid to employees, including contributions to § 401(k) deferred compensation plans. Under the statutes of W, neither compensation paid to officers nor contributions to § 401(k) plans are included in the payroll factor. Net incurred the following personnel costs. 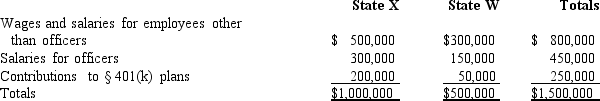 Net's payroll factor for State W is:
 (Multiple Choice)
4.8/5 (85)
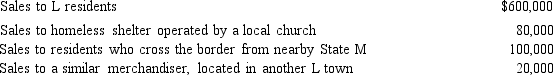
(85) Pail Corporation is a merchandiser. It purchases overstock garments from various suppliers and sells the goods in its State L retail store. Determine the total sales that are subject to the L consumer sales tax.
(Essay)
4.7/5 (76)
(76) The typical state sales/use tax falls on sales of both real and personal property.
(True/False)
4.9/5 (88)
(88) In some states, an S corporation must withhold Federal income tax for the proportionate flowthrough income of its shareholders who (are/are not) state residents.
(Short Answer)
4.9/5 (93)
(93) Match each of the following items with the appropriate description, in applying the P.L. 86-272 definition of solicitation.
a. More than solicitation, creates nexus
b. Solicitation only, no nexus created
-Operating a warehouse for inventory that is held in the state.
(Short Answer)
4.8/5 (84)
(84) An LLC apportions and allocates its annual taxable income in the same manner used by any other business operating in the state.
(True/False)
4.8/5 (93)
(93) Provide the required information for Orange Corporation, whose Federal taxable income totals $100 million. Orange apportions 70% of its business income to State C. Orange generates $10 million of nonbusiness income each year. Forty percent of that income is attributable to rentals of buildings located in C. Orange's business income this year totals $90 million.
a. State C taxes how much of Orange's business income?
b. State C taxes how much of Orange's nonbusiness income?
c. Explain your results.
(Essay)
4.8/5 (75)
(75) Politicians frequently use tax credits and exemptions to create economic development incentives.
(True/False)
4.7/5 (78)
(78) A state can levy an income tax on a business only if the business was incorporated in the state.
(True/False)
4.8/5 (80)
(80) For most taxpayers, which of the traditional apportionment factors yields the greatest opportunities for tax reduction?
(Multiple Choice)
4.7/5 (87)
(87) Bert Corporation, a calendar-year taxpayer, owns property in States M and O. Both M and O require that the average value of assets be included in the property factor. M requires that the property be valued at its historical cost, and O requires that the property be included in the property factor at its net depreciated book value.
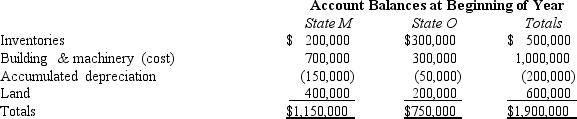
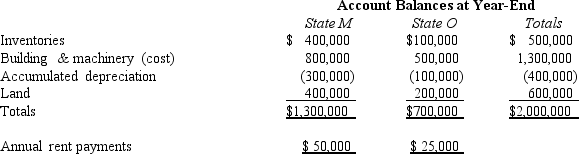 Bert's State M property factor is:

Bert's State M property factor is:
(Short Answer)
4.8/5 (82)
(82) Almost all of the states assess some form of consumer-level sales/use tax.
(True/False)
4.9/5 (95)
(95) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)