



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Realized gain is recognized by an S corporation on its distribution of property.
(Short Answer)
4.8/5  (83)
(83) Any distribution made by an S corporation during a tax year is taken into account before accounting for the year's losses.
(True/False)
4.9/5 (83)
(83) Passive investment income (for passive investment income penalty tax)
(Short Answer)
4.8/5 (87)
(87) The passive investment income of an S corporation includes net capital gains from the sale of stocks and securities.
(True/False)
4.8/5 (75)
(75) What statement is correct with respect to an S corporation?
(Multiple Choice)
4.8/5 (95)
(95) What method is used to allocate S corporation income or losses (unless an election to the contrary is made)?
(Multiple Choice)
4.9/5 (86)
(86) A new S corporation shareholder can revoke the S election unilaterally, if he/she owns how much of the existing S corporation's stock?
(Multiple Choice)
4.8/5 (84)
(84) Estela, Inc., a calendar year S corporation, incurred the following items in 2014.
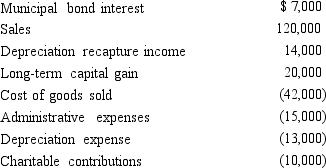 Calculate Estela's nonseparately computed income.
 (Essay)
4.7/5 (81)
(81) Samantha owned 1,000 shares in Evita, Inc., an S corporation, that uses the calendar year. On October 11, 2014, Samantha sells all of her Evita stock. Her basis at the beginning of 2014 was $60,000. Her share of the corporate income for 2014 was $22,000, and she receives a distribution of $35,000 between January 1 and October 11, 2014. Her stock basis at the time of the sale is:
(Multiple Choice)
4.9/5 (81)
(81) When an S corporation liquidates, which of its tax attributes disappear?
(Multiple Choice)
4.8/5 (92)
(92) If any entity electing S status is currently a C corporation, NOL carryovers from prior years
be used in an S corporation year.
(Short Answer)
4.9/5 (75)
(75) The maximum number of actual shareholders in an S corporation is:
(Multiple Choice)
4.9/5 (82)
(82) Which, if any, of the following can be eligible shareholders of an S corporation?
(Multiple Choice)
4.8/5 (60)
(60) Mock Corporation converts to S corporation status in 2014. Mock used the LIFO inventory method in 2013 and had a LIFO inventory of $435,000 (FIFO value of $550,000) on the date of the S election. How much tax must be added to Mock's 2013 corporate tax liability, assuming that Mock is subject to a 35% tax rate.
(Multiple Choice)
4.9/5 (87)
(87) An item that appears in the "Other Adjustments Account" affects stock basis, but not AAA, such as taxexempt interest.
(True/False)
4.9/5 (74)
(74) An S shareholder's stock basis is reduced by flowthrough losses before accounting for distributions.
(True/False)
4.9/5 (67)
(67) If an S corporation's beginning balance in OAA is zero, and the following transactions occur, what is the ending OAA balance? 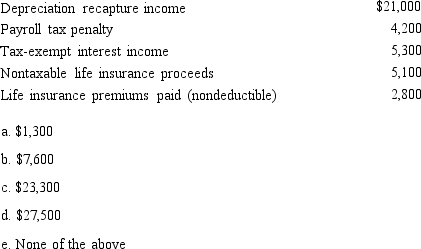
(Short Answer)
4.9/5 (88)
(88) Which statement is incorrect with respect to an S shareholder's consent?
(Multiple Choice)
4.8/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)