



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


The § 1202 exclusion of gain is not available on disposition of S corporation stock.
(True/False)
4.8/5  (55)
(55) The Section 179 expense deduction is a Schedule K item on the Form 1120S.
(True/False)
4.7/5 (68)
(68) You are given the following facts about a 50% owner of an S corporation. Compute his ending stock basis. 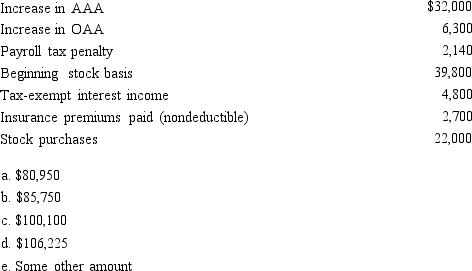
(Short Answer)
4.8/5 (94)
(94) Any distribution of cash or property by a corporation that does not exceed the balance of AAA with respect to S stock during a post-termination transition period of approximately one year is applied against and reduces the basis of the S stock.
(True/False)
4.8/5 (74)
(74) Stock basis first is increased by income items, then by distributions, and finally decreased by ____________________.
(Short Answer)
4.8/5 (83)
(83) An S shareholder's basis is increased by stock purchases and capital contributions.
(True/False)
4.8/5 (82)
(82) During 2014, Oxen Corporation incurs the following transactions. 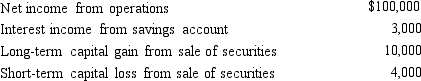 Oxen maintains a valid S election and does not distribute any assets (cash or property) to its sole shareholder, Megan. As a result, Megan must recognize:
 (Multiple Choice)
4.8/5 (76)
(76) The corporate-level tax on recognized built-in gains applies in 2014 when an S corporation disposes of an asset in a taxable disposition within ten 12-months years after the date on which the S election took effect.
(True/False)
4.9/5 (81)
(81) You are a 60% owner of an S corporation. Calculate your ending stock basis, based upon these facts.
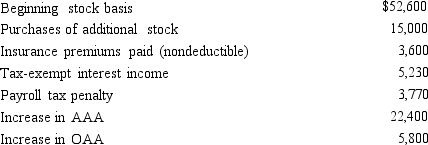
(Essay)
4.9/5 (76)
(76) An S corporation recognizes a on any distribution of appreciated property.
(Short Answer)
4.9/5 (81)
(81) The carryover period for the NOLs of a C corporation does not continue to run during S corporation years.
(True/False)
5.0/5 (82)
(82) Match the term with the proper response. There may be more than one responses for each term.
-Built-in gains tax
(Multiple Choice)
4.8/5 (77)
(77) S corporations are treated as partnerships under state property laws.
(True/False)
4.8/5 (69)
(69) The choice of a flow-through entity for a closely-held corporation often is between a(n) (a Federal tax entity) and a(n) (a state tax entity).
(Short Answer)
5.0/5 (76)
(76) A per-day, per-share allocation of flow-through S corporation items must be used, unless the shareholder disposes of the entire interest in the entity.
(True/False)
4.9/5 (75)
(75) Form 1120S provides an S shareholder's computation of his or her stock basis.
(True/False)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)