



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Which transaction affects the Other Adjustments Account on an S corporation's Schedule M2?
(Multiple Choice)
4.8/5  (86)
(86) Four unrelated individuals acquire assets on behalf of Jump Corporation on May 21, 2014, purchased assets on June 5, 2014, and begin doing business on June 15, 2014. They subscribe to shares of stock, file articles of incorporation for Jump, and become shareholders on July 23, 2014. The S election must be filed no later than 2 1/2 months after:
(Multiple Choice)
4.9/5 (82)
(82) An S corporation that has total assets of at least $10 million on Schedule L at the end of the tax year must file a Schedule M-3.
(True/False)
4.8/5 (86)
(86) The § 1202 exclusion of on the disposition of small business stock (is/is not)
available for S stock.
(Short Answer)
4.8/5 (73)
(73) Since loss property receives a in basis without any loss recognition, S corporation distributions of loss property should be .
(Short Answer)
4.8/5 (95)
(95) On January 2, 2013, David loans his S corporation $10,000. By the end of 2013 David's stock basis is zero and the basis in his note has been reduced to $8,000. During 2014, the company's operating income is $10,000. The company makes 2014 distributions to David of $11,000. David reports a(n):
(Multiple Choice)
4.9/5 (94)
(94) An S corporation must possess which of the following characteristics?
(Multiple Choice)
4.9/5 (84)
(84) On January 2, 2013, Tim loans his S corporation $10,000. By the end of 2013, Tim's stock basis is zero, and the basis in his note has been reduced to $8,000. During 2014, the company's operating income is $10,000. The company makes 2014 distributions to Tim of $8,000. Tim reports a(n):
(Multiple Choice)
4.9/5 (76)
(76) husband and wife must consent to an S election if they own their stock jointly.
(Short Answer)
4.9/5 (79)
(79) A capital loss allocated to a shareholder always reduces the Other Adjustments Account.
(True/False)
5.0/5 (80)
(80) During 2014, Miles Nutt, the sole shareholder of a calendar year S corporation, received a distribution of $16,000. On December 31, 2013, his stock basis was $4,000. The corporation earned $11,000 ordinary income during the year. It has no accumulated E & P. Which statement is correct?
(Multiple Choice)
4.9/5 (86)
(86) Alomar, a cash basis S corporation in Orlando, Florida, holds the following assets and liabilities on January 1, 2014, the date the S election is made.
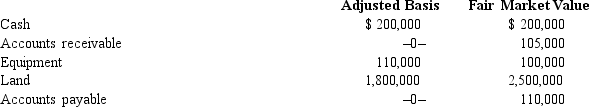 During 2014, Alomar collects the accounts receivable and pays the accounts payable. The land is sold for $3 million, and the taxable income for the year is $590,000. Calculate any built-in gains tax.
 (Essay)
4.9/5 (84)
(84) S corporation status allows shareholders to realize tax benefits from corporate losses immediately (assuming sufficient stock basis).
(True/False)
4.8/5 (74)
(74) The amount of any distribution to an S corporation shareholder is equal to the plus the fair market value of any other property distributed.
(Short Answer)
4.8/5 (80)
(80) Compare the distribution of property rules for an S corporation with the corresponding partnership rules.
(Essay)
4.8/5 (73)
(73) If an S corporation has C corporation E & P and passive investment income in excess of ____________________ % of its gross receipts for ____________________ consecutive taxable years,
the S election is terminated at the beginning of the year.
(Short Answer)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)