



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


How do the members of a Federal consolidated group split among themselves the benefits of the lower tax brackets on the first $75,000 of taxable income?
(Multiple Choice)
4.9/5  (93)
(93) Within a Federal consolidated income tax group, SubOne (can/cannot) use the LIFO inventory method at the same time that SubTwo uses the FIFO method.
(Short Answer)
4.9/5 (90)
(90) The consolidated return rules combine the members' transactions involving items (e.g., § 1231 gain/loss) when computing consolidated taxable income.
(Short Answer)
4.8/5 (81)
(81) Deferring recognition of an intercompany gain is one ____________________ (advantage/disadvantage) of electing to file consolidated returns.
(Short Answer)
4.8/5 (72)
(72) ParentCo, SubOne and SubTwo have filed consolidated returns since 2014. All of the entities were incorporated in 2013. Taxable income computations for the members include the following. None of the group members incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 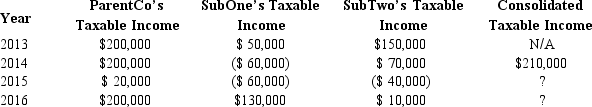 How should the 2015 consolidated net operating loss be apportioned among the group members?
ParentCo SubOne SubTwo
How should the 2015 consolidated net operating loss be apportioned among the group members?
ParentCo SubOne SubTwo (Multiple Choice)
4.8/5 (85)
(85) The consolidated income tax return rules apply only for Federal tax purposes. Financial accounting rules can be quite different from the corresponding tax rules, but the tax professional should be familiar with both sets of requirements. Describe the major differences between the book and tax treatment for the conglomerate's reporting of:
a. The ownership levels required to consolidate.
b. Goodwill.
c. The entities included on the report.
(Essay)
4.8/5 (79)
(79) Certain tax return items are computed on a group basis when a Federal consolidated return election is in place. List five or more of these group-basis items.
(Essay)
4.9/5 (81)
(81) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
a. Increases stock basis of subsidiary
b. Decreases stock basis of subsidiary
c. No effect on stock basis of subsidiary
-Increase in affiliate's E & P
(Short Answer)
4.9/5 (80)
(80) The losses of a consolidated group member are subject to both the SRLY rules and a § 382 limitation. When both limitations apply, the § 382 restrictions override the SRLY rules for this affiliate.
(True/False)
5.0/5 (74)
(74) ParentCo purchased all of the stock of ChildCo on January 2, 2012, and the two companies filed consolidated returns for 2012 and thereafter. Both entities were incorporated in 2011. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. No § 382 limit applies. 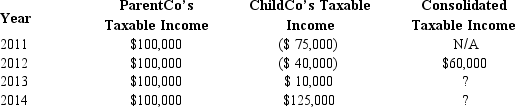 To what extent can ChildCo's 2011 losses be used by the group in 2014?
 (Multiple Choice)
4.8/5 (76)
(76) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
a. Increases stock basis of subsidiary
b. Decreases stock basis of subsidiary
c. No effect on stock basis of subsidiary
-Member's operating gains/profits
(Short Answer)
4.8/5 (78)
(78) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
a. Group item
b. Not a group item
-Dividends received deduction
(Short Answer)
5.0/5 (77)
(77) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
a. Group item
b. Not a group item
-Net operating loss
(Short Answer)
4.7/5 (81)
(81) Most of the rules governing the use of consolidated returns are found in tax , and not the ____________________.
(Short Answer)
4.8/5 (87)
(87) List some of the non-tax reasons that groups of corporations form conglomerates and may be eligible also to file consolidated Federal income tax returns.
(Essay)
4.8/5 (85)
(85) An example of an intercompany transaction is the use of the trademarks of the parent corporation by a subsidiary for an arm's length licensing fee.
(True/False)
4.9/5 (93)
(93) ParentCo's separate taxable income was $200,000, and JuniorCo's was $50,000. Consolidated taxable income before contributions was $200,000. Charitable contributions made by the affiliated group included $5,000 by ParentCo and $1,000 by JuniorCo. Compute the group's maximum charitable contribution deduction.
(Multiple Choice)
4.8/5 (77)
(77) Campbell Corporation left the Crane consolidated tax return group after the calendar 2014 tax year. Generally, Crane can add Campbell back to the consolidated group, but no earlier than for the 2020 tax year.
(True/False)
4.9/5 (78)
(78) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return.
a. Advantage of consolidating
b. Disadvantage of consolidating
c. Neither an advantage nor a disadvantage
-Gain deferral on intercompany transactions
(Short Answer)
4.9/5 (70)
(70) The right to file on a consolidated basis is available to a group of corporations when they constitute a "parent subsidiary affiliated group."
(True/False)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)