



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


ParentCo and SubCo had the following items of income and deduction for the current year. 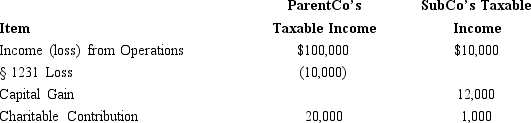 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.9/5  (72)
(72) Where are the controlling Federal income tax rules regarding consolidated tax returns to be found? What is the general philosophy of those rules? Do they tend to be pro-or anti-taxpayer?
(Essay)
4.8/5 (81)
(81) For consolidated tax return purposes, purchased goodwill is amortized as a deduction to taxable income over 15 years. Under financial accounting rules, 40-year amortization is allowed.
(True/False)
4.8/5 (81)
(81) ParentCo and SubCo had the following items of income and deduction for the current year.
ParentCo's SubCo's Taxable
Item Taxable Income Income
Income (loss) from Operations $100,000 ($10,000)
§ 1231 Loss (5,000)
Capital Gain 15,000
Charitable Contribution 12,000
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
a. $85,000 $5,000
a. None of the above.
b. $85,000 $3,000
c. $85,500 $5,000
d. $85,500 $3,000
(Essay)
4.8/5 (68)
(68) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return.
a. Advantage of consolidating
b. Disadvantage of consolidating
c. Neither an advantage nor a disadvantage
-Loss deferral on intercompany transactions
(Short Answer)
4.9/5 (75)
(75) ParentCo and SubCo had the following items of income and deduction for the current year.
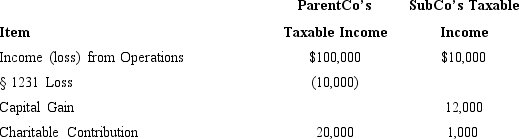 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
a. $81,000 $21,000
b. $81,000 $22,000
c. $70,000 $22,000
d. $70,000 $21,000
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
a. $81,000 $21,000
b. $81,000 $22,000
c. $70,000 $22,000
d. $70,000 $21,000 (Essay)
4.9/5 (68)
(68) When both apply, the § 382 NOL limitation rules override the limits.
(Short Answer)
4.8/5 (75)
(75) The treatment of group items on a Federal consolidated corporate income tax return (always, sometimes, never) results in a reduction of consolidated taxable income.
(Short Answer)
4.8/5 (74)
(74) If there is a balance in the excess loss account when a subsidiary's stock is sold, the balance is recognized as
____________________ gain/income.
(Short Answer)
4.8/5 (100)
(100) ParentCo and SubCo had the following items of income and deduction for the current year. 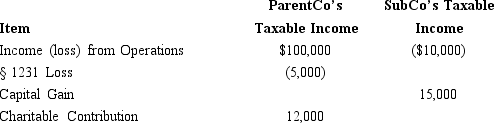 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.8/5 (70)
(70) In computing consolidated taxable income, compensation amounts are removed from the taxable incomes of the group members and determined on a group basis.
(True/False)
4.8/5 (85)
(85) Members of a parent-subsidiary controlled group must share one $40,000 for the tax year.
(Short Answer)
5.0/5 (95)
(95) When a corporate group elects to file Federal income tax returns on a consolidated basis, it is subject to several tax return filing requirements for its first and subsequent tax years. List the most important of those requirements.
(Essay)
4.9/5 (86)
(86) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
a. Increases stock basis of subsidiary
b. Decreases stock basis of subsidiary
c. No effect on stock basis of subsidiary
-Member's capital gain
(Short Answer)
4.8/5 (75)
(75) Consider AB, a brother-sister group of U.S. corporations, and CD, a parent-subsidiary group of U.S. corporations. Which of these could comprise a controlled group? An affiliated group?
(Essay)
4.8/5 (70)
(70) In computing consolidated taxable income, the profit/loss from a sale between Subsidiary and Parent is an example of a(n) ____________________ item.
(Short Answer)
4.7/5 (85)
(85) The domestic production activities deduction (DPAD) of the affiliates is an example of an item that is computed on a basis on a Federal corporate income tax consolidated return.
(Short Answer)
4.7/5 (70)
(70) ParentCo owns all of the stock of both SubOne and SubTwo. List three "intercompany transactions" that might occur among the three members of the consolidated filing group.
(Essay)
4.9/5 (89)
(89) A Federal consolidated filing group aggregates its separate charitable contributions for the tax year, deductions for which then are subject to an annual limitation of 10% of consolidated taxable income.
(True/False)
4.8/5 (86)
(86) Match each of the following items with the appropriate description, indicating whether the item's treatment for financial accounting and Federal income tax purposes is the same or not.
a. Tax and book treatment is the same
b. Tax and book treatment differ
-Parent owns 100% of a U.S. partnership and wants the entity to join the consolidated group.
(Short Answer)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)