



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations109 Questions
Exam 4: Corporations: Organization and Capital Structure92 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions130 Questions
Exam 6: Corporations: Redemptions and Liquidations115 Questions
Exam 7: Corporations: Reorganizations140 Questions
Exam 8: Consolidated Tax Returns175 Questions
Exam 9: Taxation of International Transactions177 Questions
Exam 10: Partnerships: Formation, Operation, and Basis135 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations144 Questions
Exam 12: S: Corporations158 Questions
Exam 13: Comparative Forms of Doing Business170 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities185 Questions
Exam 16: Multistate Corporate Taxation187 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes222 Questions
Exam 19: Family Tax Planning188 Questions
Exam 20: Income Taxation of Trusts and Estates183 Questions
Select questions type


Gold, Silver, and Tin are the affiliates in a Federal consolidated group. Each of the members conducts traditional manufacturing activities. Is a domestic production activities deduction (DPAD) available to the group members? Who can claim it? How is each member's DPAD, if any, computed?
(Essay)
4.8/5  (94)
(94) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return.
a. Advantage of consolidating
b. Disadvantage of consolidating
c. Neither an advantage nor a disadvantage
-Choice of tax year-ends by affiliates
(Short Answer)
5.0/5 (88)
(88) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
a. Group item
b. Not a group item
-Domestic production activities deduction
(Short Answer)
4.7/5 (84)
(84) Discuss how a parent corporation computes its stock basis for a subsidiary that joins in a Federal consolidated income tax return.
(Essay)
5.0/5 (74)
(74) When a subsidiary sells to the parent some business-use property that has appreciated from its $20,000 basis to a $50,000 fair market value, the subsidiary immediately recognizes $30,000 ordinary income on the consolidated return.
(True/False)
4.9/5 (81)
(81) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return.
a. Advantage of consolidating
b. Disadvantage of consolidating
c. Neither an advantage nor a disadvantage
-Offsetting gains against other members' losses
(Short Answer)
4.7/5 (75)
(75) ParentCo owned 100% of SubCo for the entire year. ParentCo uses the accrual method of tax accounting, whereas SubCo uses the cash method. During the year, SubCo sold raw materials to ParentCo for $35,000 under a contract that requires no payment to SubCo until the following year. Exclusive of this transaction, ParentCo had income for the year of $30,000, and SubCo had income of $50,000. The group's consolidated taxable income for the year was:
(Multiple Choice)
4.7/5 (78)
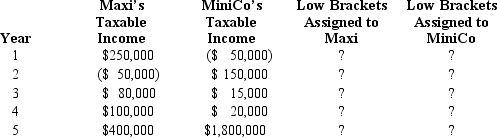
(78) Maxi Corporation owns 100% of the stock of MiniCo, and the two corporations file a consolidated tax return. Over a five-year period, the corporations generate the following taxable income/(loss). Indicate how you would assign the taxpayers' low marginal rates that apply to the group's first $75,000 of taxable income. Explain the rationale for your recommendation.
(Essay)
4.9/5 (78)
(78) The consolidated tax return regulations use "SRLY" limitations with respect to losses of a subsidiary that can be deducted on the consolidated return. Describe the various SRLY rules that might apply to a consolidated group member's losses.
(Essay)
4.8/5 (91)
(91) ParentCo purchased 100% of SubCo's stock on January 1, 2014, and the companies have filed consolidated returns since then. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 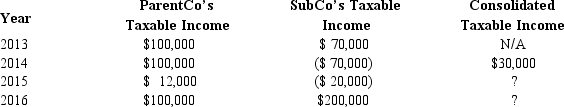 The 2015 net operating loss:
 (Multiple Choice)
4.9/5 (77)
(77) In computing consolidated taxable income, the purchase at a realized gain of a depreciable asset by Subsidiary from Parent is an example of a(n) transaction.
(Short Answer)
4.7/5 (85)
(85) In computing consolidated E & P, a negative adjustment is allowed for the group's disallowed travel and entertainment expenditures.
(True/False)
4.9/5 (77)
(77) The U.S. states apply different rules in treating Federal consolidated groups for corporate income tax purposes. Describe at least three different approaches that the states currently use to allow or restrict conglomerates' use of consolidations.
(Essay)
4.9/5 (85)
(85) The "SRLY" and § 382 limitation rules for Federal consolidated tax returns are designed to keep corporations from "trafficking" their net operating losses. These rules are restrictive and somewhat complex. Explain why these rules exist, and how they interact if both apply in the same tax year.
(Essay)
4.8/5 (76)
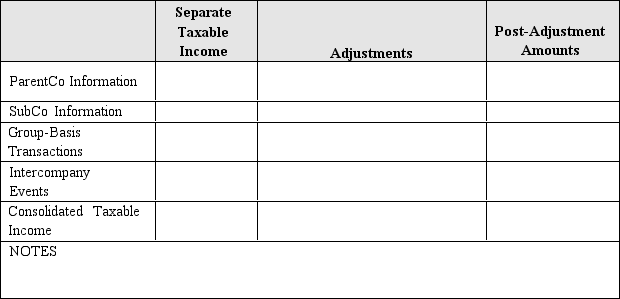
(76) In the current year, Parent Corporation provided advertising services to its 100%-owned subsidiary, SubCo, under a contract that requires no payments to Parent until next year. Both parties use the accrual method of tax accounting and a calendar tax year. The services that Parent rendered were valued at $250,000. In addition, Parent received $20,000 of interest payments from SubCo., relative to an arm's length note between them.
Including these transactions, Parent's taxable income for the year amounted to $400,000. SubCo reported $200,000 separate taxable income. Derive the group's consolidated taxable income, using the format of Figure 82.
(Essay)
4.9/5 (77)
(77) Keep Corporation joined an affiliated group by merger in 2010. The group generated a 2014 consolidated NOL, and Keep's share of the loss was $50,000. Keep's share of the loss is included in the group's NOL carryforward to 2015.
(True/False)
4.8/5 (88)
(88) Consolidated estimated tax payments must begin for the (first, second, etc.) tax year after the group's election.
(Short Answer)
4.9/5 (70)
(70) When a consolidated NOL is generated, each affiliate is allocated a share of the loss.
(True/False)
4.8/5 (66)
(66) Business reasons, and not tax incentives, constitute the primary motivation for most corporations to form a conglomerate and file tax and financial accounting reports on a consolidated basis.
(True/False)
4.7/5 (80)
(80) Which of the following entities is eligible to file Federal income tax returns on a consolidated basis?
(Multiple Choice)
4.9/5 (95)
(95) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)