



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Which of the following is eligible to file Federal income tax returns on a consolidated basis?
(Multiple Choice)
4.9/5  (80)
(80) If the negative adjustments to the stock basis of the subsidiary exceed the positive adjustments plus the subsidiary stock basis at the beginning of the tax year, a(n) ____________________ account is created.
(Short Answer)
4.8/5 (81)
(81) Keep Corporation joined an affiliated group by merger. The group generated a 2011 consolidated NOL, and Keep's share of the loss was $50,000. Keep's share of the loss is included in the group's NOL carryforward to 2012.
(True/False)
4.9/5 (77)
(77) Within a Federal consolidated income tax group, SubOne ____________________ (can/cannot) use the LIFO inventory method at the same time that SubTwo uses dollar-cost averaging.
(Short Answer)
4.8/5 (89)
(89) The parent computes a basis in the stock of its subsidiary that is part of a Federal consolidated tax return group. This stock basis cannot be a negative amount. Explain.
(Essay)
4.7/5 (80)
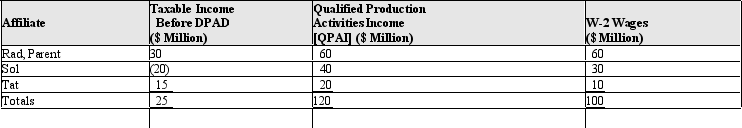
(80) Except for the § 199 domestic production activities deduction (DPAD), the members of an electing affiliated group report the following data. Compute the group's DPAD for calendar tax year 2011.
(Essay)
4.9/5 (67)
(67) An affiliated group exists where there is ____________________ percent ownership of all of the affiliates within the group, and there is an identifiable ____________________ corporation.
or
(Short Answer)
5.0/5 (74)
(74) Dividends paid by a subsidiary to the parent cause a ____________________ (positive/negative) adjustment to the parent's stock basis of the subsidiary.
(Short Answer)
4.8/5 (79)
(79) A corporation organized outside of the U.S. can be included in a Federal consolidated return.
(True/False)
4.9/5 (74)
(74) In computing consolidated E & P, dividends paid to the parent by group members are ignored.
(True/False)
4.7/5 (62)
(62) ParentCo purchased 100% of SubCo's stock on January 1, 2011, and the companies have filed consolidated returns since then. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 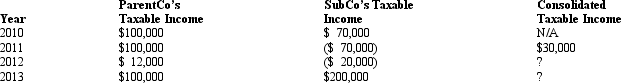 The 2012 net operating loss:
 (Multiple Choice)
4.9/5 (67)
(67) The right to file on a consolidated basis is available to a group of corporations when they constitute a "parent-subsidiary affiliated group."
(True/False)
5.0/5 (81)
(81) Over time, the consolidated return rules have shifted from penalizing joint filing to allowing a tax-neutral means by which to elect to file on a consolidated basis.
(True/False)
4.8/5 (84)
(84) In computing consolidated E & P, a negative adjustment is allowed for the group's Federal income tax payments.
(True/False)
4.8/5 (79)
(79) In computing consolidated taxable income, a charitable contribution is an example of a(n) ____________________ item.
(Short Answer)
4.9/5 (66)
(66) ParentCo and SubCo had the following items of income and deduction for the current year. 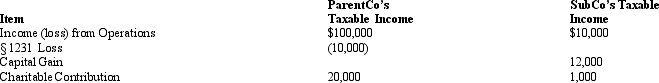 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.9/5 (74)
(74) The group of Parent Corporation, SubOne, and SubTwo has filed a consolidated return since 2010. The first two entities were incorporated in 2009, and SubTwo came into existence in 2010 through an asset spin-off from Parent. Taxable income computations for the members are shown below. None of the group members incurred any capital gain or loss transactions during 2009-2012, nor did they make any charitable contributions.
Describe the treatment of the group's 2011 consolidated NOL. Hint: Apply the offspring rule.
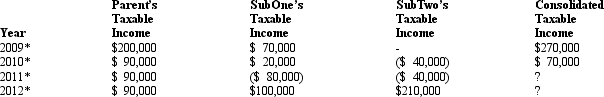 * Consolidated return year.
 (Essay)
4.7/5 (92)
(92) Cooper Corporation joined the Duck consolidated Federal income tax return group, when Cooper held a $1 million NOL carryforward. In its first year as a part of the Duck group, Cooper generated a $150,000 NOL. For that year, Duck can deduct only $150,000 of Cooper's NOL in computing consolidated taxable income.
(True/False)
4.9/5 (71)
(71) The consolidated net operating loss of the Parent Group includes all of the following except:
(Multiple Choice)
4.7/5 (99)
(99) Campbell Corporation left the Crane consolidated tax return group after the calendar 2011 tax year. Crane can add Campbell back to the consolidated group, but no earlier than for the 2017 tax year.
(True/False)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)