



 Chat with AI
Exam 4: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Mary transfers a building (adjusted basis of $15,000 and fair market value of $90,000) to White Corporation. In return, Mary receives 80% of White Corporation's stock (worth $65,000) and an automobile (fair market value of $5,000). In addition, there is an outstanding mortgage of $20,000 (taken out 15 years ago) on the building, which White Corporation assumes. With respect to this transaction:

Free
(Multiple Choice)
4.8/5  (78)
(78) Correct Answer: Verified
A
Kathleen transferred the following assets to Mockingbird Corporation. 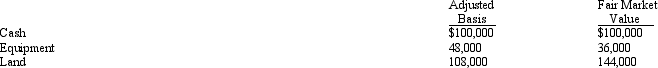 In exchange, Kathleen received 40% of Mockingbird Corporation's only class of stock outstanding. The stock has no established value. However, all parties sincerely believe that the value of the stock Kathleen received is the equivalent of the value of the assets she transferred. The only other shareholder, Rick, formed Mockingbird Corporation five years ago.
Free
(Multiple Choice)
5.0/5 (84)
(84) Correct Answer:Verified
VerifiedD
Kirby and Helen form Red Corporation. Kirby transfers property, basis of $20,000 and value of $300,000, for 100 shares in Red Corporation. Helen transfers property, basis of $40,000 and value of $280,000, and provides legal services in organizing the corporation. The value of her services is $20,000. In return Helen receives 100 shares in Red Corporation. With respect to the transfers:
Free
(Multiple Choice)
4.9/5 (87)
(87) Correct Answer:Verified
VerifiedE
Dawn, a sole proprietor, was engaged in a service business and reported her income on a cash basis. Later, she incorporates her business and transfers the assets of the business to the corporation in return for all the stock in the corporation plus the corporation's assumption of the liabilities of her proprietorship. All the receivables and the unpaid trade payables are transferred to the newly formed corporation. The assets of the proprietorship had a basis of $105,000 and fair market value of $300,000. The trade accounts payable totaled $25,000. There was a note payable to the bank in the amount of $95,000 that the corporation assumes. The note was issued for the purchase of computers and other business equipment.
(Multiple Choice)
4.9/5 (84)
(84) Four individuals form Chickadee Corporation under § 351. Two of these individuals, Jane and Walt, made the following contributions: 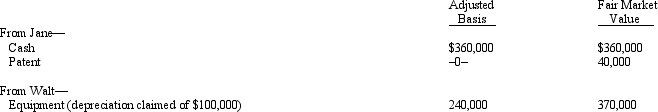 Both Jane and Walt receive stock in Chickadee Corporation equal to the value of their investments.
 (Multiple Choice)
4.8/5 (73)
(73) Adam transfers cash of $300,000 and land worth $200,000 to Camel Corporation for 100% of the stock in Camel. In the first year of operation, Camel has net taxable income of $70,000. If Camel distributes $50,000 to Adam:
(Multiple Choice)
4.9/5 (74)
(74) Similar to like-kind exchanges, the receipt of "boot" under § 351 can cause loss to be recognized.
(True/False)
5.0/5 (77)
(77) Robert organized Redbird Corporation 10 years ago by contributing property worth $3 million, basis of $550,000, for 2,000 shares of stock in Redbird, representing 100% of the stock in the corporation. Robert later gave each of his children, Brittany and Julie, 600 shares of stock in Redbird Corporation. In the current year, Robert transfers property worth $700,000, basis of $150,000, to Redbird for 1,000 shares in the corporation. What gain, if any, will Robert recognize on the transfer?
(Essay)
4.9/5 (86)
(86) Linda formed Pink Corporation with an investment of $200,000 cash, for which she received $20,000 in stock and $180,000 in 5% interest-bearing bonds maturing in ten years. A few years later Linda loaned Pink an additional $40,000 on open account. Pink becomes insolvent in the current year and is adjudged bankrupt. Linda was the president of Pink Corporation and was paid an annual salary of $35,000 for the past three years. Linda has no other employment. How will Linda treat her losses for tax purposes?
(Essay)
4.9/5 (69)
(69) In order to encourage the development of an industrial park, a county donates land to Ecru Corporation. The donation does not result in gross income to Ecru.
(True/False)
4.8/5 (92)
(92) Julio exchanges property, basis of $100,000 and fair market value of $1.8 million, for 75% of the stock of Lime Corporation. The other 25% is owned by Gloria who acquired it several years ago. What are the tax consequences to the parties involved?
(Essay)
4.8/5 (81)
(81) The use of § 351 is not limited to the initial formation of a corporation, and it can apply to later transfers as well.
(True/False)
4.9/5 (91)
(91) Silver Corporation receives $1 million in cash from Madison County as an inducement to expand its operations. Within one year, Silver spends $1.5 million to enlarge its existing plant. Silver Corporation's basis in the expansion is $500,000.
(True/False)
4.9/5 (75)
(75) Section 351 (which permits transfers to controlled corporations to be tax deferred) can be justified under the wherewithal to pay concept.
(True/False)
4.8/5 (64)
(64) Thomas transfers cash of $160,000 to Grouse Corporation, a newly formed corporation, for 100% of the stock in Grouse worth $90,000 and debt in the amount of $70,000, payable in equal annual installments of $7,000 plus interest at the rate of 5% per annum. In the first year of operation, Grouse has net taxable income of $40,000. If Grouse pays Thomas interest of $3,500 and $7,000 principal payment on the note:
(Multiple Choice)
4.7/5 (75)
(75) Issues relating to basis arise when a taxpayer is involved in a § 351 transaction. Describe the underlying rules, and the purpose they serve.
(Essay)
4.9/5 (82)
(82) Since services are not considered property under § 351, a taxpayer must report as income the fair market value of stock received for such services.
(True/False)
4.9/5 (85)
(85) In a § 351 transfer, gain will be recognized to the extent of the lesser of realized gain or the boot received.
(True/False)
4.7/5 (81)
(81) Ann, Irene, and Bob incorporate their respective businesses and form Dove Corporation. Ann exchanges her property (basis of $100,000 and fair market value of $400,000) for 200 shares in Dove Corporation on March 1, 2009. Irene exchanges her property (basis of $140,000 and fair market value of $600,000) for 300 shares in Dove Corporation on April 11, 2009. Bob transfers his property (basis of $250,000 and fair market value of $1,000,000) for 500 shares in Dove Corporation on May 15, 2011. Bob's transfer is not part of a prearranged plan with Ann and Irene to incorporate their businesses. What gain, if any, will Bob recognize on the transfer?
(Multiple Choice)
4.7/5 (87)
(87) Trudy forms Oak Corporation by transferring land with a basis of $150,000 (fair market value of $800,000), subject to a mortgage of $450,000. Two weeks prior to incorporating Oak, Trudy borrows $10,000 for personal purposes and gives the lender a second mortgage on the land. Oak Corporation issues stock worth $340,000 to Trudy and assumes the two mortgages on the land. What are the tax consequences to Trudy and to Oak Corporation?
(Essay)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)