



 Chat with AI
Exam 19: Family Tax Planning

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


At the time of her death in 2011, Corinne owned stock in Gray Corporation. The stock is traded on a local exchange with the most recent selling prices as follows.  Presuming no alternate valuation date election, Corinne's gross estate should include a per share value of:
Free
(Multiple Choice)
4.9/5  (77)
(77) Correct Answer: Verified
D
For the IRS to grant a discretionary extension of time to pay estate taxes (under § 6161), the executor need not show that the estate would otherwise undergo undue hardship.
Free
(True/False)
5.0/5 (82)
(82) Correct Answer:Verified
VerifiedTrue
A decedent owned 25% of the voting stock of Siskin Corporation. Siskin has 53 shareholders. The decedent's estate can still qualify for the § 6166 election.
Free
(True/False)
4.9/5 (71)
(71) Correct Answer:Verified
VerifiedTrue
One way to dispute the existence of large goodwill is to argue that the decedent was a key person in the operation of the business.
(True/False)
4.8/5 (82)
(82) Cost and time are usually saved by passing ownership to out-of-state real estate by death rather than by gift.
(True/False)
5.0/5 (84)
(84) Harvey owns a certificate of deposit listed as: "Harvey, payable on proof of death to April." On Harvey's prior death, the CD is not subject to probate.
(True/False)
4.7/5 (70)
(70) Which of the following procedures carried out will reduce both Mary's future gross estate and her probate estate?
(Multiple Choice)
4.8/5 (72)
(72) Doug inherited his mother's bedroom furniture worth $3,000. For sentimental reasons, Martha, the daughter, pays Doug $3,500 for the furniture. The furniture should be included in the mother's gross estate at $3,500.
(True/False)
5.0/5 (71)
(71) In April 2010, Ed gives his mother, Grace, real estate (basis of $400,000; fair market value of $800,000). Ed paid no Federal gift tax on the transfer. Before Grace's death in March 2011, she makes $40,000 in capital improvements to the property. The real estate is worth $840,000 when Grace dies. What is the income tax basis of the property to Grace's heir under each of the following assumptions?
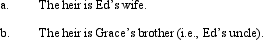
(Essay)
4.9/5 (90)
(90) 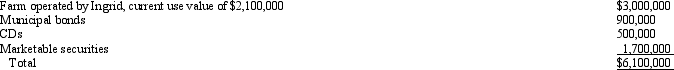
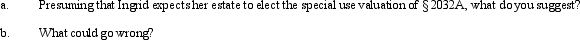
If the special use valuation method of § 2032A is elected and certain continuing requirements are not satisfied, recapture occurs.
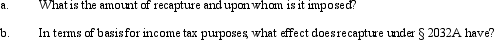
(Essay)
4.8/5 (84)
(84) Which, if any, of the items listed below are valid factors utilized in valuing the stock in a closely held corporation?
(Multiple Choice)
4.9/5 (69)
(69) Jane is the founder of Citron Corporation and owns all of its stock, both common and preferred. The preferred stock is noncumulative and possesses no preferential rights as to liquidation. In 1996 and when the common stock has a value of $1,200,000, Jane gives it to her adult children. She retains the preferred stock which, at this time, has a value of $300,000. In 2011, Jane dies. Values on the date of death are: $3,000,000 for the common stock and $500,000 for the preferred.
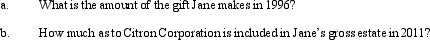
(Essay)
4.8/5 (82)
(82) Which, if any, of the following statements reflects the correct tax valuation rules?
(Multiple Choice)
4.8/5 (90)
(90) At the time of her death in 2011, Lila owns 50% of the stock in Kingfisher Corporation, with the balance of the stock held by family members. Kingfisher Corporation's total profits for the past five years are $3,000,000, and the book value of its stock is $2,000,000. If 8% is an appropriate rate of return and goodwill exists, what is a possible value for the stock to be included in Lila's gross estate?
(Essay)
4.9/5 (86)
(86) Richard and Marie are joint tenants in a tract of land. Upon Richard's prior death, Marie's income tax basis in the land does not change.
(True/False)
4.8/5 (83)
(83) Art makes a gift of stock in Drab Corporation, which is not closely held but is traded in an over-the-counter market. The transactions involving this stock that occurred closest to the date of gift took place five trading days before (mean selling price of $120) and six days after (mean selling price of $100). Determine the fair market value of the Drab stock on the date of the gift.
(Essay)
4.8/5 (79)
(79) For purposes of § 6166 (i.e., extension of estate tax payments relative to an interest in a closely held business), an interest in a closely held business does not include:
(Multiple Choice)
4.9/5 (74)
(74) In 1989, Tony, a resident of New York, purchases realty for $500,000 listing title as "Tony and Ben, joint tenants with right of survivorship." In 2011, Tony predeceases Ben when the realty is worth $2,000,000. Ben's income tax basis in the property is:
(Multiple Choice)
5.0/5 (76)
(76) What are some of the pitfalls in the use of § 2032A (special use valuation method)?
(Essay)
5.0/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)