



 Chat with AI
Exam 19: Family Tax Planning

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


At the time of his death, Fred held some notes receivable for loans he made to his two daughters and the payment of which he forgives in his will. The amount to be included in Fred's gross estate as to these notes is affected by his forgiveness.
(True/False)
4.9/5  (87)
(87) Wesley has created an irrevocable trust: life estate to Eve, remainder to Ernest upon Eve's death. In using the IRS valuation tables, what information is needed to determine the value of Eve's life estate?
(Essay)
4.9/5 (78)
(78) The election of § 2032 (alternate valuation date) for estate tax purposes:
(Multiple Choice)
4.8/5 (77)
(77) In 2009, Sophia sold real estate (adjusted basis of $500,000) for $1,500,000. Under the terms of the sale, she received two notes of $750,000 each, with 9% interest provided. One note is due in 2010 and the other in 2011. She did not elect out of the installment method of recognizing gain. In 2010 and before the first note matures, Sophia gives both notes to her adult children. At this time, the notes are worth a total of $1,400,000. Disregarding the interest element, a tax result of these transactions is:
(Multiple Choice)
4.8/5 (86)
(86) Eric, age 80, has accumulated about $6 million in net assets. Among his assets are the following marketable securities held as investments.  Eric would like to donate (either by lifetime or testamentary transfer) $250,000 in value to his church. In addition, to consummate a land deal, he needs $250,000 in cash. Looking solely to tax: considerations and using only the assets described above, Eric's best choice is to:
 (Multiple Choice)
4.9/5 (73)
(73) Using investments worth $1 million, Roland establishes a trust, life estate to Melinda, remainder to Kim.
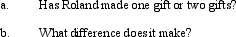
(Essay)
4.8/5 (86)
(86) Giselle, a widow, has an extensive investment portfolio that has appreciated in value. Starting in 2009, she initiates a policy of making annual gifts of securities to her grandchildren who are attending college. Evaluate Giselle's policy in terms of the:
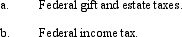
(Essay)
4.8/5 (73)
(73) At the time of his death, Harvey was a shareholder in Grebe Corporation. In valuing the Grebe stock included in Harvey's gross estate, the IRS contends that the corporation possessed considerable goodwill. In disputing this contention, which of the following point(s) is/are relevant?
(Multiple Choice)
5.0/5 (89)
(89) One of the objectives of family tax planning is to minimize income taxes on transfers of property within the family unit.
(True/False)
4.9/5 (80)
(80) At the time of Rick's death, he owned 70% of the stock in Robin Corporation, a closely held family business. Over the past five years, Robin has averaged annual profits of $400,000 in an industry where the usual rate of return is 9%. If the book value of the corporation's assets is $1,000,000 and goodwill exists, what might be a realistic value of the stock in Rick's gross estate?
(Multiple Choice)
5.0/5 (73)
(73) Which, if any, of the following statements properly characterize features involving buy-sell agreements?
(Multiple Choice)
4.9/5 (75)
(75) In 2011, Arlene makes a gift of stock (basis of $813,000; fair market value of $413,000) to her mother, Elizabeth. As a result of the transfer, Arlene paid a gift tax of $60,000. Elizabeth's income tax basis in the stock is:
(Multiple Choice)
4.8/5 (83)
(83) In satisfying the more-than-35% test for qualification under § 6166, interests in multiple closely held businesses are aggregated when the decedent's gross estate includes 20% or more of the value of each such business.
(True/False)
4.9/5 (75)
(75) Under proper circumstances, a disclaimer by an heir may increase the charitable deduction allowed a decedent.
(True/False)
4.9/5 (86)
(86) How can a disclaimer by an heir increase the charitable deduction allowed a decedent? Is such a disclaimer always wise? Explain.
(Essay)
4.9/5 (80)
(80) Which statement is correct concerning the rules governing the application of § 2032A ("special use" valuation)?
(Multiple Choice)
4.8/5 (76)
(76) Regarding the effects of § 1014(e) (i.e., step-up in basis and the one-year rule), comment on the following variables.
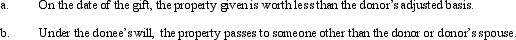
(Essay)
4.9/5 (82)
(82) Rick and Gail are equal tenants in common in real estate. Upon Gail's prior death, Rick's basis in the real estate does not change.
(True/False)
4.8/5 (85)
(85) In 1990, Jude, a resident of New York, purchases realty for $500,000 listing title as "Jude and Tony, joint tenants with right of survivorship." In 2011, Tony predeceases Jude when the realty is worth $2,000,000. Tony's income tax basis in the property is:
(Multiple Choice)
4.7/5 (77)
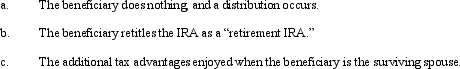
(77) In connection with a traditional IRA that is transferred at death, comment on the tax implications of each of the following.
(Essay)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)