



 Chat with AI
Exam 18: The Federal Gift and Estate Taxes

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Walt dies intestate (i.e., without a will) in the current year with a gross estate valued at $4,000,000. Under applicable state law, Walt's property passes to Kelly or to Belle, in that order. Kelly has an estimated net worth of $3,000,000 while Belle has none. From a tax planning standpoint, what course of action might be advisable.

Free
(Essay)
4.9/5  (63)
(63) Correct Answer: Verified
This might be a good situation to make use of § 2518. Thus, Kelly could disclaim some of the $4,000,000 inheritance and, in effect, pass it to Belle free of any transfer tax to Kelly (i.e., estate or gift tax).
Lila is the owner and beneficiary of a policy on the life of her husband, Austin. Upon Austin's prior death, the insurance proceeds paid to Lila do not qualify for the marital deduction.
Free
(True/False)
4.9/5 (72)
(72) Correct Answer:Verified
VerifiedTrue
In 1990, Bret and Olivia acquire realty for $1 million, with Bret furnishing $400,000 of the purchase price and Olivia providing the balance. Title to the property is listed as: "Bret and Olivia, joint tenants with right of survivorship." In 2011, Olivia dies first when the realty is worth $4 million. How much is included in her gross estate under the following circumstances?
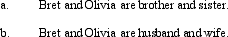
Free
(Essay)
4.9/5 (82)
(82) Correct Answer:Verified
Verified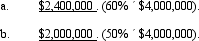
Death does not defeat a deceased spouse's interest in a tenancy by the entirety.
(True/False)
4.8/5 (80)
(80) If a donor has a fiscal year of July 1-June 30 for income tax purposes, this changes the normal filing date for Form 709.
(True/False)
4.8/5 (81)
(81) In which of the following situations is Polly's property ownership interest not lost by her prior death?
(Multiple Choice)
4.8/5 (78)
(78) As reflected by the tax law, Congressional policy relative to the Federal gift and estate taxes has been very inconsistent. Comment on this policy regarding the following time periods.
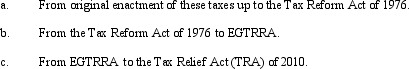
(Essay)
4.8/5 (87)
(87) Distributions from retirement plans and proceeds from life insurance plans usually are not subject to probate.
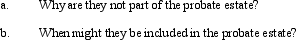
(Essay)
4.8/5 (84)
(84) In determining the gift tax due on a current gift, a credit is allowed for gift taxes actually paid on prior taxable gifts. Comment on the accuracy of this statement.
(Essay)
4.9/5 (85)
(85) At the time of his prior death, Raul owned a residence with his wife, Manuela, as tenants by the entirety. The residence was purchased by Manuela ten years ago at a cost of $300,000 and has a fair market value of $1.4 million. Raul's estate will be allowed no marital deduction as to the property.
(True/False)
4.9/5 (80)
(80) Under the alternate valuation date election, each asset in the gross estate is valued at the lesser of the date of death value or six months thereafter.
(True/False)
4.9/5 (71)
(71) The § 2513 election to split gifts is less useful in community property states than in common law states. Explain.
(Essay)
4.8/5 (80)
(80) The use of the election to split gifts under § 2513 may be necessary for spouses who live in community property states.
(True/False)
4.9/5 (79)
(79) In 2009, Katherine made some taxable gifts upon which she paid a Federal gift tax of $96,000. If Katherine dies in 2011, the $96,000 is included in her gross estate under the "gross up" rule.
(True/False)
4.9/5 (80)
(80) The current Federal transfer tax rate of 35% is as low as any top rate that ever has been imposed.
(True/False)
4.7/5 (80)
(80) As a result of an auto accident from which she later died, Irene totaled a Bentley worth $95,000. If the insurance company covers $60,000 of the loss, Irene's estate can claim a deduction of $35,000 in arriving at the taxable estate.
(True/False)
4.9/5 (72)
(72) Sally's will passes real estate to Otto (her surviving spouse). The real estate is worth $800,000 but is subject to a mortgage of $200,000. The transfer provides Sally's estate with a marital deduction of $600,000.
(True/False)
4.9/5 (89)
(89) Ben and Lynn are married and have two pre-teen grandchildren. They want to contribute to a § 529 plan on behalf of their education. For 2011, what is the maximum amount they can transfer to the plan without making a taxable gift?
(Essay)
4.9/5 (74)
(74) Which of the following is not a characteristic of both the Federal gift tax and the Federal estate tax?
(Multiple Choice)
4.9/5 (86)
(86) Regarding the transfer tax credits available, which of the following statements is correct?
(Multiple Choice)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)