



 Chat with AI
Exam 20: Income Taxation of Trusts and Estates

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


The Bard Estate incurs a $25,000 fee in disposing of the real property of the decedent. The deduction is claimed against the Federal estate tax, unless by election it is claimed on the estate's income tax return.

Free
(True/False)
4.9/5  (84)
(84) Correct Answer: Verified
True
A complex trust can claim a Year 1 deduction for a gift to charity, where the contribution was made on October 20 of Year 2 out of gross income recognized in Year 1.
Free
(True/False)
4.7/5 (83)
(83) Correct Answer:Verified
VerifiedTrue
With respect to a trust, the terms creator, donor, and grantor are synonyms.
Free
(True/False)
4.9/5 (82)
(82) Correct Answer:Verified
VerifiedTrue
To reduce trustee commissions, the Sigrid Trust is operated as though it were two trusts (i.e., with 70-year-old Grandma and 7-year old Skippy each holding equal shares). This year the trust generated distributable net income (DNI) of $80,000. The Sigrid trustee distributed $100,000 to Grandma this year: $40,000 as her one-half share of the entity's income, and $60,000 as a distribution of principal. Skippy received no distribution. How much of the year's distributable net income is assigned to Grandma?
(Multiple Choice)
5.0/5 (75)
(75) The depreciation deductions of a trust usually are allocable to ____________________ beneficiaries.
or
(Short Answer)
4.8/5 (84)
(84) The grantor set up a trust, income to a daughter, remainder to a grandson. To the extent that trust income is used to pay a life insurance premium on the grantor's spouse, Subchapter J rules are ignored, and the income is taxed to the grantor.
(True/False)
4.8/5 (78)
(78) "First-tier distributions" allowed by the will or trust document are made at the discretion of the executor or trustee.
(True/False)
4.9/5 (73)
(73) Tax planning usually dictates that high-income and -wealth individuals be specified as first-tier beneficiaries of a trust arrangement.
(True/False)
4.9/5 (81)
(81) The accounting income of a trust is distributed to the grantor's ex-spouse, in satisfaction of the year's alimony obligation. The ____________________ is taxed on the amount of the distribution.
(Short Answer)
4.8/5 (82)
(82) Remainder beneficiary Shelley receives a $50,000 net operating loss carryover when the Malone Trust terminates. Shelley deducts this amount ____________________ (for/from) AGI on her Form 1040.
(Short Answer)
4.8/5 (82)
(82) The Code defines a grantor trust as which of the following?
(Multiple Choice)
4.9/5 (76)
(76) The grantor of a trust generally designates both ____________________ and ____________________ beneficiaries under the controlling agreement.
or
(Short Answer)
5.0/5 (83)
(83) The Cooper Trust is required to distribute $80,000 annually, split equally between its two income beneficiaries, Amber and Byron. If trust income is not sufficient to pay these amounts, the trustee can invade corpus to the extent necessary. During the current year, the trust has DNI of $50,000. Byron receives an additional $20,000 discretionary corpus distribution.
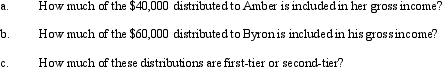
(Essay)
4.8/5 (76)
(76) A fiduciary's distribution deduction shifts the tax burden for current-year income from the entity to the beneficiary.
(True/False)
4.7/5 (79)
(79) Jose is subject to the top marginal Federal income tax rates. Carlita is considering establishing a trust in which Jose would be an income beneficiary. Considering only income tax consequences, Jose should be designated as:
(Multiple Choice)
4.8/5 (78)
(78) The distributable net income (DNI) of a fiduciary taxpayer:
(Multiple Choice)
4.9/5 (73)
(73) The unextended due date for a calendar-year trust to file its Form 1041 is March 15.
(True/False)
5.0/5 (87)
(87) Every ____________________ trust is allowed a $300 personal exemption.
(Short Answer)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)