



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


A consolidated Federal income tax group must meet the eligibility requirements of the Regulations only on the first day of the first year for which the election to consolidate is effective.

Free
(True/False)
4.8/5  (67)
(67) Correct Answer: Verified
False
When an affiliated group elects to file Federal consolidated income tax returns, it gives up the ability to claim a ____________________ deduction for distributions of profits paid to other members.
Free
(Short Answer)
4.9/5 (85)
(85) Correct Answer:Verified
Verifieddividends received
Certain tax return items are computed on a group basis when a Federal consolidated return election is in place. List five or more of these group-basis items.
Free
(Essay)
4.8/5 (78)
(78) Correct Answer:Verified
VerifiedThe following items are among those that are computed on a group basis for a Federal corporate consolidated income tax return.
· Net long-term capital gain/loss
· Net short-tem capital gain/loss
· § 1231 gain/loss
· AMT adjustments and preferences
· Domestic production activities deduction
· Casualty/theft gain/loss
· Charitable contributions
· Dividends received deduction
· Net operating loss
Which of the following potentially is a disadvantage of electing to file a Federal corporate income tax consolidated return?
(Multiple Choice)
4.8/5 (76)
(76) Forming a Federal consolidated tax return group is a discretionary action by eligible affiliates. List several tax attributes and situations that might make a subsidiary an attractive partner for a parent corporation on a consolidated return.
(Essay)
5.0/5 (75)
(75) For consolidated tax return purposes, goodwill is amortized as a deduction to taxable income. Under financial accounting rules, no such amortization is allowed.
(True/False)
4.8/5 (83)
(83) The calendar-year Sterling Group files its Federal corporate income tax return on a consolidated basis. Its Form 1120 is due on March 15, or September 15 if an extended due date is approved by the IRS.
(True/False)
4.9/5 (82)
(82) The casualty/theft gain/loss of the affiliates is an example of an item that is computed on a ____________________ basis on a Federal corporate income tax consolidated return.
(Short Answer)
4.9/5 (69)
(69) ParentCo and SubOne have filed consolidated returns since 2008. SubTwo was formed in 2012 through an asset spin-off from ParentCo. SubTwo has joined in the filing of consolidated returns since then. Taxable income computations for the members include the following. None of the group members incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 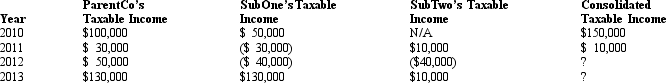 If ParentCo does not elect to forgo the carryback of the 2012 net operating loss, how much of the 2012 consolidated net operating loss is carried back to offset prior years' income?
 (Multiple Choice)
4.9/5 (86)
(86) Generally, when a subsidiary leaves an on-going consolidated group, it must wait ____________________ years before it can reenter another consolidated group.
or
(Short Answer)
4.8/5 (84)
(84) Parent Corporation owns 100% of the stock of SubCo, and the two corporations file a consolidated tax return. Over a five-year period, the corporations generate the following taxable income/(loss). Indicate how you would assign the taxpayers' low marginal rates that apply to the group's first $75,000 of taxable income. Explain the rationale for your recommendation.
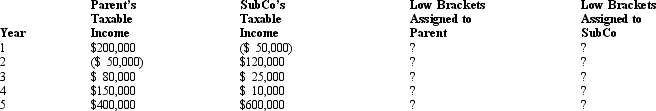
(Essay)
4.8/5 (86)
(86) ParentCo and SubCo had the following items of income and deduction for the current year. 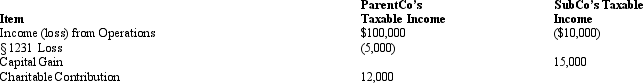 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.7/5 (93)
(93) A joint venture, taxed like a partnership, can join in a consolidated Federal income tax return.
(True/False)
4.9/5 (86)
(86) The purpose of the rules governing intercompany sales on a Federal consolidated tax return is to treat the group as though it is:
(Multiple Choice)
4.9/5 (72)
(72) The domestic production activities deduction of a consolidated group can be greater than the sum of the deductions of the group members when filing separately.
(True/False)
4.7/5 (90)
(90) How do the Federal consolidated return requirements differ in identifying an affiliated group rather than a parent-subsidiary controlled group?
(Essay)
4.8/5 (97)
(97) How are the members of a Federal consolidated group affected by computations related to E & P?
(Multiple Choice)
5.0/5 (86)
(86) After a takeover, the parent takes a fair market value cost basis in the subsidiary, for both book and tax purposes.
(True/False)
4.9/5 (87)
(87) The Harris consolidated group reports a net operating loss (NOL) for the year. The tax law works to:
(Multiple Choice)
4.9/5 (86)
(86) LargeCo files on a consolidated basis with LittleCo. The subsidiary was acquired for $400,000 on January 1, Year 1, and it paid a $75,000 dividend to LargeCo at the end of both Year 2 and Year 3.
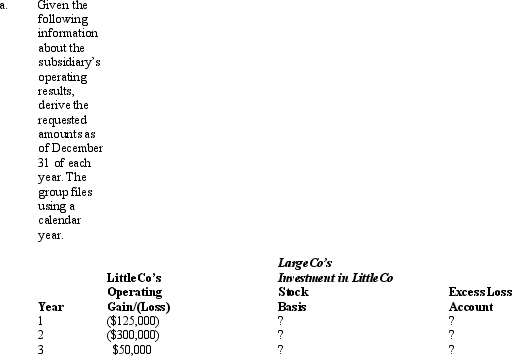
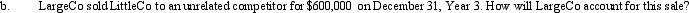
(Essay)
4.9/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)