



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


In computing consolidated taxable income, § 1231 gains and losses are removed from the taxable incomes of the group members and determined on a group basis.
(True/False)
4.9/5  (75)
(75) Members of a controlled group share all but which of the following tax attributes?
(Multiple Choice)
4.9/5 (72)
(72) Which of the following is not generally a disadvantage of filing Federal corporate income tax returns on a consolidated basis?
(Multiple Choice)
4.8/5 (84)
(84) If, on joining an affiliated group, SubCo has a different tax year than that of ParentCo, SubCo must switch its year-end to ParentCo's by the end of the ____________________ (first, second, etc.) tax year after the election to consolidate.
or
(Short Answer)
4.9/5 (88)
(88) In the year that the group terminates its consolidation election, a consolidated group's deferred gain from an intercompany asset sale between affiliates is recognized in full, under the ____________________ rule.
(Short Answer)
4.8/5 (69)
(69) Which of the following items is not computed on a consolidated basis?
(Multiple Choice)
4.9/5 (80)
(80) Most of the rules governing the use of consolidated returns are found in tax ____________________, and not the ____________________.
(Short Answer)
4.7/5 (88)
(88) In the context of a Federal consolidated income tax return, describe the matching rule and the acceleration rule. The Regulations apply these rules to some of the intercompany transactions of an affiliated group.
(Essay)
4.7/5 (88)
(88) Most of the Federal consolidated income tax return rules are found in detailed sections of the Internal Revenue Code.
(True/False)
4.7/5 (73)
(73) The rules for computing Federal consolidated taxable income can differ a significant way from those governing financial reporting for conglomerates.
(True/False)
4.9/5 (75)
(75) The Parent consolidated group reports the following results for the tax year. Determine each member's share of the consolidated tax liability, assuming that the members all have consented to use the relative taxable income tax-sharing method. Dollar amounts are listed in millions, and a 35% marginal income tax rate applies.
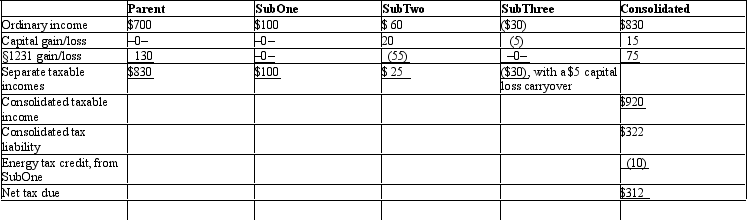
(Essay)
4.8/5 (75)
(75) Tax incentives constitute the primary motivation for most corporations to form a conglomerate and file tax and financial accounting reports on a consolidated basis.
(True/False)
4.9/5 (75)
(75) The starting point in computing consolidated taxable income is the separate Federal taxable income amounts of the affiliated group members.
(True/False)
4.9/5 (68)
(68) ParentCo and SubCo had the following items of income and deduction for the current year. 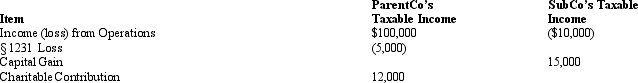 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo (Multiple Choice)
4.8/5 (83)
(83) Members of an affiliated group must share one $40,000 ____________________ for the tax year.
(Short Answer)
4.8/5 (91)
(91) The Rub, Sal, and Ton Corporations file Federal income tax returns on a consolidated basis. The group's tax return currently is under audit. Under a valid tax-sharing agreement, each corporation is liable for one-third of the group's consolidated tax liability. The affiliates have agreed with the auditor that the group's unpaid liability for the year is $90,000. Because of an incorrect tax return position, another $3,000 in interest and a $1,800 penalty is attributable solely to Ton. At present, only Rub is solvent and has the cash with which to make such a tax payment. What is the maximum amount for which the government could be successful in forcing Rub to satisfy the outstanding liabilities of the consolidated group?
(Multiple Choice)
4.8/5 (75)
(75) A wholly owned LLC can join the parent's consolidated group for book, but not for tax, purposes.
(True/False)
4.9/5 (78)
(78) Which of the following is eligible to join in a Federal consolidated return?
(Multiple Choice)
4.9/5 (88)
(88) Conformity among the members of a consolidated group must be implemented for which of the following tax items?
(Multiple Choice)
4.8/5 (78)
(78) Consolidated estimated tax payments must begin for the ____________________ (first, second, etc.) tax year after the group's election.
or
(Short Answer)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)