



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


List three "intercompany transactions" of a Federal consolidated income tax group. ParentCo owns all of the stock of both SubOne and SubTwo.
(Essay)
4.9/5  (83)
(83) ParentCo's controlled group includes the following members. ParentCo owns all of the stock in each of the listed entities. Which entities can join ParentCo in a consolidated return?
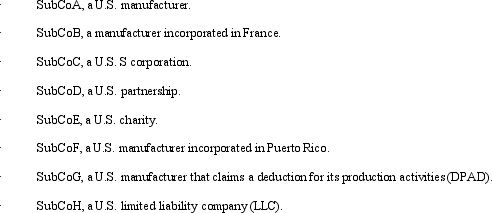
(Essay)
4.8/5 (88)
(88) ParentCo owned 100% of SubCo for the entire year. ParentCo uses the accrual method of tax accounting, whereas SubCo uses the cash method. During the year, SubCo sold raw materials to ParentCo for $35,000 under a contract that requires no payment to SubCo until the following year. Exclusive of this transaction, ParentCo had income for the year of $30,000, and SubCo had income of $50,000. The group's consolidated taxable income for the year was:
(Multiple Choice)
4.7/5 (84)
(84) When a member departs a consolidated group, it forfeits the use of any NOLs it generated while in the group.
(True/False)
4.9/5 (72)
(72) ParentCo, SubOne and SubTwo have filed consolidated returns since 2011. All of the entities were incorporated in 2010. Taxable income computations for the members include the following. None of the group members incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 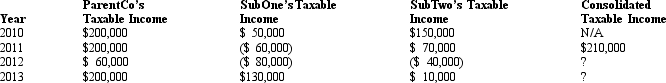 How should the 2012 consolidated net operating loss be apportioned among the group members?
ParentCo SubOne SubTwo
How should the 2012 consolidated net operating loss be apportioned among the group members?
ParentCo SubOne SubTwo (Multiple Choice)
4.8/5 (66)
(66) When the parent acquires 51% of a subsidiary U.S. corporation, the subsidiary can join the consolidated financial statements, but not the consolidated tax return of the parent.
(True/False)
4.9/5 (70)
(70) A Federal consolidated group can claim a dividends received deduction for payments that the parent receives from other affiliates.
(True/False)
4.9/5 (83)
(83) ParentCo and SubCo had the following items of income and deduction for the current year. 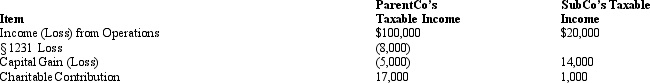 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo (Multiple Choice)
4.8/5 (68)
(68) In computing consolidated taxable income, the purchase of database services by Subsidiary from Parent is an example of a(n) ____________________ transaction.
(Short Answer)
4.9/5 (92)
(92) ParentCo and SubCo had the following items of income and deduction for the current year. 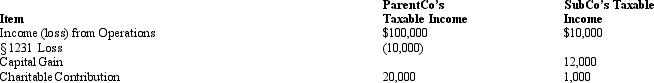 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo (Multiple Choice)
4.9/5 (92)
(92) If subsidiary stock is redeemed or sold outside the group when an excess loss account exists, the selling parent corporation recognizes capital gain income equal to the account balance.
(True/False)
4.9/5 (73)
(73) When a corporate group elects to file Federal income tax returns on a consolidated basis, it is subject to several tax return filing requirements for its first and subsequent tax years. List the most important of those requirements.
(Essay)
4.7/5 (70)
(70) Consolidated group members each must use the same tax year end.
(True/False)
4.7/5 (81)
(81) In computing consolidated taxable income, cost of goods sold is removed from the taxable incomes of the group members and determined on a group basis.
(True/False)
4.9/5 (76)
(76) A Federal consolidated tax return group commonly applies the "relative tax liability" method as a means to apportion the tax liabilities of the members among the affiliates.
(True/False)
4.8/5 (73)
(73) The capital gain/loss of the affiliates is an example of an item that is computed on a ____________________ basis on a Federal corporate income tax consolidated return.
(Short Answer)
4.8/5 (86)
(86) How many consolidated tax returns are filed annually? What types of taxpayer do they represent?
(Essay)
4.7/5 (77)
(77) Which of the following tax effects becomes more restrictive if an election is made to file a group's Federal corporate income tax returns on a consolidated basis?
(Multiple Choice)
4.9/5 (78)
(78) A penalty can be assessed by the IRS if the parent corporation does not keep good records to support the computation of a subsidiary's stock basis.
(True/False)
4.9/5 (75)
(75) Discuss how a parent corporation computes its stock basis for a subsidiary that joins in a Federal consolidated income tax return.
(Essay)
4.9/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)