



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Typically exempt from the sales/use tax base is the purchase of tools by a manufacturer to make the widgets that it sells.

Free
(True/False)
4.8/5  (83)
(83) Correct Answer: Verified
True
Pail Corporation is a merchandiser. It purchases overstock garments from various suppliers and sells the goods in its State L retail store. Determine the total sales that are subject to the L consumer sales tax.

Free
(Essay)
4.9/5 (79)
(79) Correct Answer:Verified
VerifiedPail must collect L sales tax on $900,000. No tax is collected from sales to charities, nor to other entities who will then re-sell the goods. The sales to M residents actually create an M use tax, as the goods presumably are worn by the customers in M. M residents should file a return to pay the M sales tax and then claim a credit for the payment actually made to L. Compliance with this cross-border result is very low. M might enforce this rule if its sales tax was applied at a higher rate than L's, perhaps only on big-ticket items like automobiles.
In determining state taxable income, all of the following are adjustments to Federal income except:
Free
(Multiple Choice)
4.9/5 (89)
(89) Correct Answer:Verified
VerifiedD
A state sales/use tax is designed to be collected by the ____________________ (seller/purchaser) of the product and then remitted to the state.
(Short Answer)
4.7/5 (77)
(77) A service engineer spends 60% of her time maintaining the employer's productive business property and 40% maintaining the employer's nonbusiness rental properties. This year, her compensation totaled $90,000. The payroll factor assigns $54,000 to the state in which the employer is based.
(True/False)
4.7/5 (83)
(83) Kim Corporation, a calendar year taxpayer, has manufacturing facilities in States A and
B. A summary of Kim's property holdings follows.
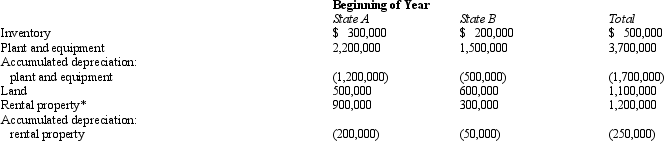
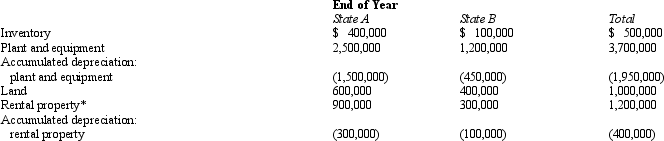 *Unrelated to Kim's regular business and operations.
Determine Kim's property factors for the two states. A's statutes provide that the average historical cost of business property is to be included in the property factor. B's statutes provide that the property factor is based on the average depreciated basis of in-state business property.
Kim Corporation's property factor is 61.90% for State A, and its property factor for State B is 44.53%. Under the statutes of A and B, nonbusiness property (i.e., the rental property) is not taken into consideration in computing the property factor. The basis for determining the average property in A is historical cost, whereas the value employed for B is depreciated cost.
HISTORICAL COST-EXCLUDING NONBUSINESS PROPERTY
*Unrelated to Kim's regular business and operations.
Determine Kim's property factors for the two states. A's statutes provide that the average historical cost of business property is to be included in the property factor. B's statutes provide that the property factor is based on the average depreciated basis of in-state business property.
Kim Corporation's property factor is 61.90% for State A, and its property factor for State B is 44.53%. Under the statutes of A and B, nonbusiness property (i.e., the rental property) is not taken into consideration in computing the property factor. The basis for determining the average property in A is historical cost, whereas the value employed for B is depreciated cost.
HISTORICAL COST-EXCLUDING NONBUSINESS PROPERTY (Essay)
4.8/5 (92)
(92) Under the UDITPA's ____________________ concept, sales are assumed to take place at the point of delivery, as opposed to the location at which the shipment originates.
(Short Answer)
4.8/5 (76)
(76) Typically exempt from the sales/use tax base is the purchase of lumber by a do-it-yourself homeowner, when she builds a deck onto her patio.
(True/False)
4.9/5 (71)
(71) Giant Corporation owns all of the stock of Junior Corporation, a Delaware passive investment company. Giant operates strictly in nonunitary State B, which levies a 9% income tax. This year, Junior earned $200,000 of portfolio interest income and paid a $150,000 dividend to Giant. In which state(s) will the interest income create an income tax liability?
(Multiple Choice)
4.9/5 (84)
(84) A state wants to increase its income tax collections, but politically it would be unwise to raise taxes on in-state individuals or businesses. Identify some changes to the income tax apportionment formula that would shift the scheduled income tax increases to out-of-state businesses.
(Essay)
4.7/5 (81)
(81) A typical state taxable income addition modification is the interest income from U.S. Treasury bonds.
(True/False)
4.9/5 (76)
(76) All of the U.S. states use the same apportionment formula and factors.
(True/False)
4.8/5 (88)
(88) A taxpayer has nexus with a state for sales and use tax purposes if it has a physical presence in the state.
(True/False)
4.9/5 (77)
(77) Mercy Corporation, headquartered in F, sells wireless computer devices, including keyboards and bar code readers. Mercy's degree of operations is sufficient to establish nexus only in E and
F. Determine its sales factor in those states.
State E applies a throwback rule to sales, while State F does not. State G has not adopted an income tax to date. Mercy reported the following sales for the year. All of the goods were shipped from Mercy's F manufacturing facilities.
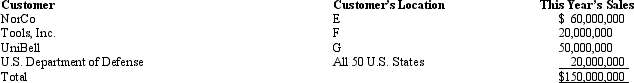
(Essay)
4.9/5 (87)
(87) Roughly forty percent of all taxes paid by businesses in the U.S. are to state, local, and municipal jurisdictions.
(True/False)
4.8/5 (90)
(90) Compost Corporation has finished its computation of Federal taxable income. In State Q, the derivation of state corporate taxable income starts with the Federal amount and makes a number of modifications. List at least five such modifications that Compost is likely to encounter.
(Essay)
4.9/5 (82)
(82) A taxpayer wishing to reduce the negative tax effects of the application of the unitary theory might:
(Multiple Choice)
4.9/5 (76)
(76) The ____________________ tax usually is applied at the city or county level, as its main source of revenue.
(Short Answer)
4.9/5 (75)
(75) Garcia Corporation is subject to tax in States G, H, and I. Garcia's compensation expense includes the following.
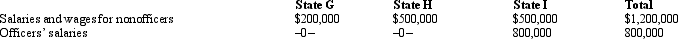 Officers' salaries are included in the payroll factor for G and H, but not for I. Compute Garcia's payroll factors for G, H, and I.
 (Essay)
4.8/5 (84)
(84) If a state follows Federal income tax rules, the state's tax compliance and enforcement become easier to accomplish.
(True/False)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)