



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Cruz Corporation owns manufacturing facilities in States A, B, andC. A uses a three-factor apportionment formula under which the sales, property and payroll factors are equally weighted. B uses a three-factor apportionment formula under which sales are double-weighted. C employs a single-factor apportionment factor, based solely on sales.
Cruz's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows.
 Cruz's apportionable income assigned to C is:
 (Multiple Choice)
4.8/5  (96)
(96) Which of the following is not immune from state income taxation, even if P.L. 86-272 is in effect?
(Multiple Choice)
4.8/5 (81)
(81) Net Corporation's sales office and manufacturing plant are located in State X. Net also maintains a manufacturing plant and sales office in State W. For purposes of apportionment, X defines payroll as all compensation paid to employees, including contributions to § 401(k) deferred compensation plans. Under the statutes of W, neither compensation paid to officers nor contributions to § 401(k) plans are included in the payroll factor. Net incurred the following personnel costs. 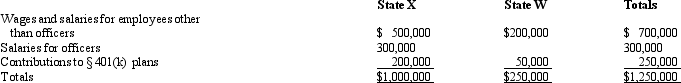 Net's payroll factor for State W is:
 (Multiple Choice)
4.9/5 (81)
(81) You are completing the State A income tax return for Quaint Company. Quaint is a limited liability company, and it operates in various states, showing the following results.
 In A, all interest is treated as business income. A uses a sales-only apportionment factor. Compute Quaint's A taxable income.

In A, all interest is treated as business income. A uses a sales-only apportionment factor. Compute Quaint's A taxable income.
(Essay)
4.7/5 (88)
(88) P.L. 86-272 ____________________ (does/does not) create nexus when the seller conducts its sales solicitations from a calling center building that it owns.
(Short Answer)
4.7/5 (67)
(67) All of the U.S. states have adopted a tax based on net taxable income.
(True/False)
4.9/5 (72)
(72) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its A headquarters to a customer in B. This activity is not sufficient for General to create nexus with B. State B applies a throwback rule, but State A does not. In which state(s) will the sale be included in the sales factor numerator?
(Multiple Choice)
4.9/5 (79)
(79) José Corporation realized $600,000 taxable income from the sales of its products in States X and Z. José's activities in both states establish nexus for income tax purposes. José's sales, payroll, and property among the states include the following.  Z utilizes a double-weighted sales factor in its three-factor apportionment formula. How much of José's taxable income is apportioned to Z?
 (Multiple Choice)
4.7/5 (72)
(72) Use tax would be due if an individual purchased an auto in State A and used it at his home in State
B.
(True/False)
5.0/5 (68)
(68) You attend a tax webinar in which the presenter mentions the "ultimate destination concept." Define this term, and identify at least two of the most important exceptions to the general rule.
(Essay)
4.8/5 (77)
(77) In the broadest application of the unitary theory, the U.S. unitary business files a combined tax return using factors and income amounts for all affiliates:
(Multiple Choice)
4.9/5 (82)
(82) _________________________ is a means by which a corporation's business income is divided among the states in which it conducts business.
(Short Answer)
4.9/5 (78)
(78) A state cannot levy a tax on a business unless the business was incorporated in the state.
(True/False)
4.8/5 (76)
(76) Parent and Junior form a unitary group of corporations. Parent is located in a state with an effective tax rate of 3%, while Junior's effective tax rate is 9%. Acting in concert to reduce overall tax liabilities, the group should:
(Multiple Choice)
4.8/5 (74)
(74) In computing the property factor, property owned by the corporation typically is valued at its ____________________, plus the cost of additions and improvements, but without adjusting for ____________________.
or
(Essay)
4.9/5 (75)
(75) Your supervisor has shifted your responsibilities from the Federal corporate income tax to a multistate corporate income tax practice. On which issues, if any, are the tax bases and procedures likely to overlap?
(Essay)
4.9/5 (91)
(91) A ____________________ tax is designed to complement the local sales tax structure, to prevent the consumer from making purchases in another, lower-tax state.
(Short Answer)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)