



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Typically, the state's payroll factor ____________________ (does/does not) include the fringe benefits provided to its sales force.
(Short Answer)
4.8/5  (64)
(64) In determining taxable income for state income tax purposes, the Federal NOL deduction typically constitutes a(n) ____________________ modification.
(Short Answer)
4.9/5 (82)
(82) ____________________ describe(s) the degree of business activity that must be present before a taxing jurisdiction has the right to impose a tax on an entity's income.
(Short Answer)
4.9/5 (82)
(82) Under _____________________, a state is prohibited from taxing a business if the only connection with the state is the solicitation of orders for sales of tangible personal property that are sent outside the state for approval or rejection and, if approved, are filled and shipped by the business from a point outside of the state.
(Short Answer)
4.7/5 (90)
(90) In the apportionment formula, most states assign more than a one-third weight to the ____________________ factor.
(Short Answer)
4.8/5 (85)
(85) Dott Corporation generated $300,000 of state taxable income from selling its mapping software in States A and
B. Both states utilize a three-factor apportionment formula which equally weights sales, property, and payroll. The rates of corporate income tax imposed in A and B are 7% and 10%, respectively. Determine Dott's state income tax liability.
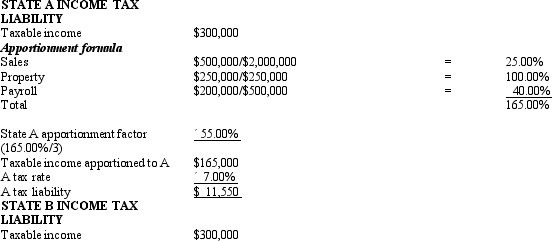 B. For the taxable year, the corporation's activities within the two states were as follows.
 Dott has determined that it is subject to tax in both A and
B. For the taxable year, the corporation's activities within the two states were as follows.
Dott has determined that it is subject to tax in both A and (Essay)
4.8/5 (75)
(75) Bert Corporation, a calendar-year taxpayer, owns property in States M and O. Both M and O require that the average value of assets be included in the property factor. M requires that the property be valued at its historical cost, and O requires that the property be included in the property factor at its net depreciated book value. 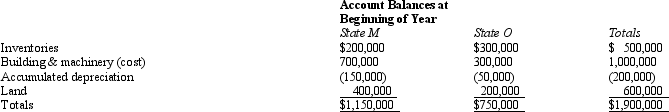
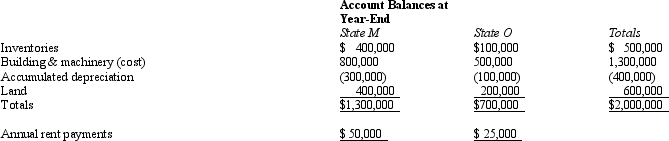 Bert's M property factor is:
 (Multiple Choice)
4.9/5 (83)
(83) Under P.L. 86-272, which of the following transactions by itself would create nexus with a state?
(Multiple Choice)
4.8/5 (79)
(79) Nonbusiness income includes dividends received from investment securities.
(True/False)
4.9/5 (70)
(70) Your client wants to reduce its overall state/local income tax rate. It holds income-producing assets of various types, including tangible personal property, rental land and buildings, and high-yield stocks and bonds. How might this taxpayer restructure its operations to achieve the desired tax result?
(Essay)
4.8/5 (77)
(77) Bobby and Sally work for the same employer, Wooster Manufacturing. Bobby manages the company's speculative investment portfolio, and Sally is a foreman in the factory. How are the salaries paid to Bobby and Sally treated in computing Wooster's payroll factor? Apply the general UDITPA rules.
(Essay)
4.9/5 (91)
(91) Trayne Corporation's sales office and manufacturing plant are located in State X. Trayne also maintains a manufacturing plant and sales office in State W. For purposes of apportionment, X defines payroll as all compensation paid to employees, including elective contributions to § 401(k) deferred compensation plans. Under the statutes of W, neither compensation paid to officers nor contributions to § 401(k) plans are included in the payroll factor. Trayne incurred the following personnel costs. 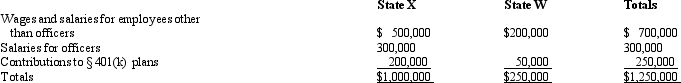 Trayne's payroll factor for State X is:
 (Multiple Choice)
4.8/5 (81)
(81) Kurt Corporation realized $900,000 taxable income from the sales of its products in States X and Z. Kurt's activities establish nexus for income tax purposes in both states. Kurt's sales, payroll, and property among the states include the following.  Z utilizes an equally weighted three-factor apportionment formula. Kurt is incorporated in X. How much of Kurt's taxable income is apportioned to Z?
 (Multiple Choice)
4.8/5 (65)
(65) The starting point in computing state taxable income generally is ____________________.
(Short Answer)
4.9/5 (78)
(78) Wailes Corporation is subject to a corporate income tax only in State X. The starting point in computing X taxable income is Federal taxable income. Wailes' Federal taxable income is $750,000, which includes a $75,000 deduction for state income taxes. During the year, Wailes received $20,000 interest on Federal obligations. X tax law does not allow a deduction for state income tax payments. Wailes' taxable income for X purposes is:
(Multiple Choice)
4.9/5 (74)
(74) A unitary business is treated as a single entity for state tax purposes, with a combined apportionment formula including data from all of the operations of the business.
(True/False)
4.9/5 (81)
(81) Sales/use tax nexus is established for the taxpayer by the sales-solicitation activities of an independent contractor acting on the taxpayer's behalf.
(True/False)
4.9/5 (88)
(88) In some states, an S corporation must withhold Federal income tax for its shareholders who ____________________ (are/are not) state residents.
(Short Answer)
5.0/5 (98)
(98) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)