



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Typically included in the sales/use tax base is the purchase of computer and cell phone equipment by a large consulting firm that is incorporated in the state.
(True/False)
4.8/5  (76)
(76) The model law relating to the assignment of income among the states for corporations is:
(Multiple Choice)
4.8/5 (81)
(81) Mandy Corporation realized $1,000,000 taxable income from the sales of its products in States X and Z. Mandy's activities establish nexus for income tax purposes only in Z. Mandy's sales, payroll, and property among the states include the following.  X utilizes a sales-only factor in its three-factor apportionment formula. How much of Mandy's taxable income is apportioned to X?
 (Multiple Choice)
4.9/5 (85)
(85) Judy, a regional sales manager, has her office in State X. Her region includes several states, as indicated in the sales report below. Determine how much of Judy's $200,000 compensation is assigned to the payroll factor of State X. 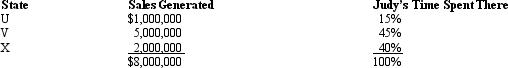
(Multiple Choice)
4.8/5 (89)
(89) The use tax is designed to complement the sales tax. A use tax typically covers purchases made out of state and brought into the jurisdiction.
(True/False)
4.9/5 (87)
(87) Most states begin the computation of taxable income with an amount from the Federal income tax return.
(True/False)
4.7/5 (79)
(79) A few states recognize an entity's S corporation status, such that taxable income flows through directly to shareholders, but they also assess a state-level tax on the entity.
(True/False)
4.8/5 (81)
(81) Valdez Corporation, a calendar-year taxpayer, owns property in States M and O. Both M and O require that the average value of assets be included in the property factor. M requires that the property be valued at its historical cost, and O requires that the property be included in the property factor at its net depreciated book value. 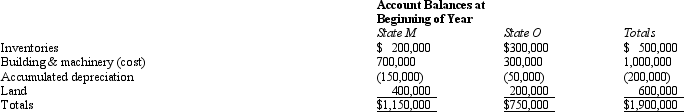
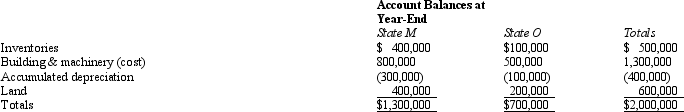 Valdez's O property factor is:
 (Multiple Choice)
4.8/5 (75)
(75) Discuss how a multistate business divides up its corporate taxable income among the states in which it operates. Hint: use the terms allocation and apportionment in your comments.
(Essay)
4.8/5 (77)
(77) Typically, a sales/use tax is applied to a retail sale of ____________________ property.
(Short Answer)
4.8/5 (84)
(84) The corporate income tax provides about 5 percent of the annual tax revenues for the typical U.S. state.
(True/False)
4.8/5 (92)
(92) Condor Corporation generated $450,000 of state taxable income from selling its product in States A and
B. Both states utilize a three-factor apportionment formula that equally weights sales, property, and payroll. The rates of corporate income tax imposed in A and B are 5% and 3%, respectively. Determine Condor's state income tax liability.
Condor's total state income tax liability is determined as follows.
STATE A INCOME TAX LIABILITY

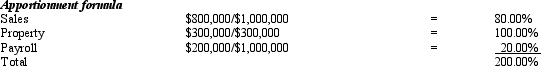
 B. For the taxable year, the corporation's activities within the two states were as follows.
 Condor has determined that it is subject to tax in both A and
B. For the taxable year, the corporation's activities within the two states were as follows.
Condor has determined that it is subject to tax in both A and (Essay)
4.8/5 (77)
(77) Shaker Corporation operates in two states, as indicated below. All goods are manufactured in State
A. Determine the sales to be assigned to both states to be used in computing Shaker's sales factor for the year. Both states follow the UDITPA and the MTC regulations in this regard.
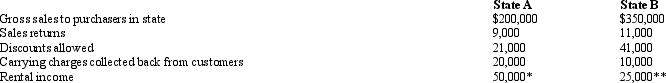 * Excess warehouse space
** Land held for speculation
* Excess warehouse space
** Land held for speculation (Essay)
4.9/5 (83)
(83) ____________________ is a method under which a corporation's nonbusiness income is directly assigned to the specific states where the income is derived.
(Short Answer)
4.8/5 (86)
(86) States collect the most tax dollars from the corporate income tax.
(True/False)
5.0/5 (80)
(80) In determining a corporation's taxable income for state income tax purposes, which of the following does not constitute a subtraction from Federal income?
(Multiple Choice)
4.8/5 (86)
(86) Almost all of the states treat a general partnership as a ____________________ entity for income tax purposes.
or
(Short Answer)
4.8/5 (85)
(85) In most states, a limited liability company (LLC) is subject to the state income tax:
(Multiple Choice)
5.0/5 (79)
(79) A local business wants your help in making a decision about a large capital investment. Should your advice concentrate on tax or non-tax implications of the decision?
(Essay)
4.8/5 (63)
(63) Hermann Corporation is based in State A (corporate income tax rate 10%). It sells its goods to customers in both A and State B (corporate income tax rate 4%). Hermann's state taxable income for the year is $1 million, 30% of which relates to B customers. Hermann's level of activities in B is insufficient to create nexus there, but A has adopted a throwback rule as to multistate sales. Would Hermann reduce its total state income tax liability by creating nexus with B, say by allowing its sales force to make credit decisions? Elaborate.
(Essay)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)