



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Outline the major advantages and disadvantages of filing Federal corporate income tax returns on a consolidated basis. Limit your comments to the income tax effects of the election.
(Essay)
4.8/5  (68)
(68) The consolidated income tax return rules apply only for Federal tax purposes. Financial accounting rules can be quite different from the corresponding tax rules, but the tax professional should be familiar with both sets of requirements. Describe the major differences between the book and tax treatment for the conglomerate's reporting of:
(Essay)
4.9/5 (90)
(90) Cooper Corporation joined the Duck consolidated Federal income tax return group, when Cooper held a $1 million NOL carryforward. In its first year as a part of the Duck group, Cooper generated a $150,000 taxable profit. For that year, Duck can deduct up to $150,000 of Cooper's NOL in computing consolidated taxable income.
(True/False)
4.8/5 (99)
(99) The Philstrom consolidated group reported the following taxable income amounts. Parent owns all of the stock of both Junior and Minor. Determine the net operating loss (NOL) that is apportioned to Junior. 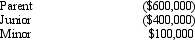
(Multiple Choice)
4.9/5 (93)
(93) Consolidated group members each are jointly and severally liable for the entire consolidated income tax liability.
(True/False)
4.8/5 (79)
(79) ParentCo and SubCo had the following items of income and deduction for the current year. 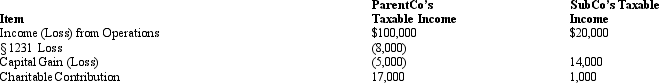 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.9/5 (79)
(79) In terms of the consolidated return rules, Akron Manufacturing LLC is a(n) ____________________ entity.
(Short Answer)
4.9/5 (82)
(82) Keep Corporation joined an affiliated group by merger in 2011. The group generated a consolidated 2011 NOL, and Keep's share of the loss was $50,000. Lacking an election by the parent to the contrary, Keep can carry the loss back to its separate 2009 return, and the parent can claim a tax refund.
(True/False)
4.9/5 (78)
(78) ParentCo acquired all of the stock of SubCo on January 1, 2011, for $1,000,000. The parties immediately elected to file consolidated income tax returns. SubCo generated taxable income of $150,000 for 2011 and paid a dividend of $100,000 to ParentCo. In 2012, SubCo generated an operating loss of $350,000, and in 2013 it produced taxable income of $75,000. As of the last day of 2013, what was ParentCo's basis in the stock of SubCo?
(Multiple Choice)
4.9/5 (78)
(78) The ____________________ rules can limit the net operating loss deduction claimed on a Federal consolidated return.
(Short Answer)
4.8/5 (71)
(71) The losses of a consolidated group member are subject to both the SRLY rules and a § 382 limitation. When both limitations apply, the SRLY rules override the § 382 restrictions for this affiliate.
(True/False)
4.8/5 (67)
(67) In computing consolidated taxable income, the domestic production activities deduction (DPAD) is removed from the taxable incomes of the group members and determined on a group basis.
(True/False)
4.7/5 (71)
(71) In computing consolidated taxable income, the profit/loss from a sale between Subsidiary and Parent is an example of a(n) ____________________ item.
(Short Answer)
4.9/5 (75)
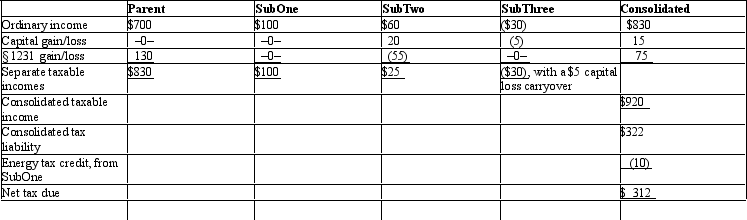
(75) The Parent consolidated group reports the following results for the tax year. Determine each member's share of the consolidated tax liability, assuming that the members all have consented to use the relative tax liability tax-sharing method. Dollar amounts are listed in millions, and a 35% marginal income tax rate applies.
(Essay)
5.0/5 (79)
(79) When a subsidiary sells to the parent some business-use property that has appreciated from its $20,000 basis to a $50,000 fair market value, the subsidiary immediately recognizes $30,000 ordinary income on the consolidated return.
(True/False)
4.8/5 (69)
(69) The Philstrom consolidated group reported the following taxable income amounts. Parent owns all of the stock of both Junior and Minor. Determine the net operating loss (NOL) that is apportioned to Minor. 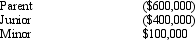
(Multiple Choice)
4.9/5 (85)
(85) Where are the controlling Federal income tax rules regarding consolidated tax returns to be found? What is the general philosophy of those rules?
(Essay)
4.9/5 (73)
(73) All members of an affiliated group have ____________________ and ____________________ liability for each other's Federal income tax liabilities.
or
(Short Answer)
4.8/5 (87)
(87) The Philstrom consolidated group reported the following taxable income amounts. Parent owns all of the stock of both Junior and Minor. Determine the net operating loss (NOL) that is apportioned to Parent. 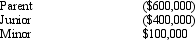
(Multiple Choice)
4.8/5 (83)
(83) How must the IRS collect the liability for Federal taxes from among a consolidated group?
(Multiple Choice)
4.9/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)