



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


A Federal consolidated group reports a net operating loss for the year. How is this amount allocated to the various group members? Why is this allocation important?
(Essay)
4.9/5  (75)
(75) How does a consolidated Federal income tax group compute its domestic production activities deduction (DPAD)? Assume that all of the affiliates in a consolidated group conduct allowable manufacturing activities.
(Essay)
4.8/5 (77)
(77) Each of the members of a Federal consolidated tax return group can claim its own $40,000 AMT exemption, subject to phase-out.
(True/False)
4.7/5 (78)
(78) The U.S. states apply different rules in treating Federal consolidated groups for corporate income tax purposes. Describe three different treatments that the states currently use.
(Essay)
4.8/5 (77)
(77) The consolidated return rules combine the members' transactions involving ____________________ items when computing consolidated taxable income.
(Short Answer)
4.8/5 (81)
(81) The "SRLY" rules for consolidated tax returns are designed to keep corporations from "trafficking" their net operating losses. Explain.
(Essay)
4.8/5 (84)
(84) ParentCo purchased all of the stock of ChildCo on January 2, 2011, and the two companies filed consolidated returns for 2011 and thereafter. Both entities were incorporated in 2010. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. No § 382 limit applies. 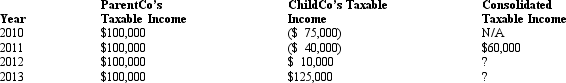 To what extent can SubCo's 2010 losses be used by the group in 2013?
 (Multiple Choice)
4.7/5 (87)
(87) List some of the non-tax reasons that groups of corporations form conglomerates and may be eligible also to file consolidated Federal income tax returns.
(Essay)
4.9/5 (84)
(84) Which of the following potentially is a disadvantage of electing to file a Federal consolidated corporate income tax return?
(Multiple Choice)
4.8/5 (82)
(82) A C corporation must leave the consolidated group if it is restructured as an LLC.
(True/False)
4.9/5 (73)
(73) Lacking elections to the contrary, Federal consolidated NOLs are carried back two years and then forward twenty years.
(True/False)
4.7/5 (75)
(75) The parent and affiliates must elect to file on a consolidated basis by ____________________ after the first consolidated tax year.
or
(Essay)
4.7/5 (73)
(73) ParentCo's separate taxable income was $200,000, and JuniorCo's was $50,000. Consolidated taxable income before contributions was $200,000. Charitable contributions made by the affiliated group included $5,000 by ParentCo and $1,000 by JuniorCo. Compute the group's maximum charitable contribution deduction.
(Multiple Choice)
5.0/5 (82)
(82) In an affiliated group, the parent must own at least 50 percent of each of the subsidiaries.
(True/False)
4.9/5 (76)
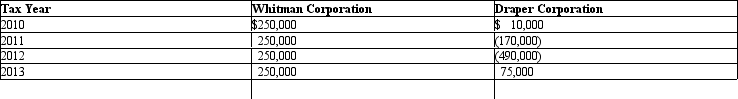
(76) Compute consolidated taxable income for the calendar year Whitman Group, which elected consolidated status immediately upon creation of the two member corporations in January 2009. All recognized income related to the data processing services of the firms. No intercompany transactions were completed during the indicated years.
(Essay)
4.8/5 (90)
(90) Deferring recognition of an intercompany loss is one ____________________ (advantage/disadvantage) of electing to file consolidated returns.
(Short Answer)
4.8/5 (81)
(81) An affiliated group aggregates its separate charitable contributions, deductions for which then are subject to an annual limitation of 10% of consolidated taxable income.
(True/False)
4.9/5 (87)
(87) A consolidated Federal income tax return may be the product of a merger of the affiliates, or of some other tax-favored reorganization.
(True/False)
4.9/5 (91)
(91) Consolidated return members determine which affiliates will pay how much of the annual Federal income tax liability by making a(n) ____________________ election.
(Short Answer)
4.7/5 (81)
(81) An example of an intercompany transaction is the use of the financial accounting software of the parent corporation by a subsidiary for an arm's length management fee.
(True/False)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)