



 Chat with AI
Exam 18: The Federal Gift and Estate Taxes

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Which, if any, of the following is not a characteristic of the Federal estate tax?
(Multiple Choice)
4.8/5  (79)
(79) In 2000, Dale and Andrea acquire real estate for $1,000,000, with Dale furnishing $400,000 of the purchase price and Andrea providing the balance. Title to the property is listed as: "Dale and Andrea, equal tenants in common." Dale dies first in 2011, when the real estate is worth $2,000,000.
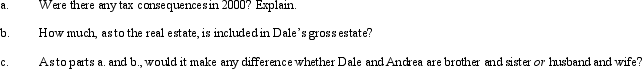
(Essay)
4.9/5 (86)
(86) Which of the following statements relating to the Federal gift tax is incorrect?
(Multiple Choice)
4.7/5 (86)
(86) At the time of her death, Rita held a promissory note from a loan she had made to her son. Even if Rita's will forgives the loan, the note is included in her gross estate.
(True/False)
4.7/5 (79)
(79) Sometimes also known as transaction taxes, Federal gift and estate taxes are excise taxes.
(True/False)
4.8/5 (75)
(75) Cary and Bo are husband and wife. Using their community funds, they create a trust, life estate to Bo, remainder to their children. Four years later, Bo predeceases Cary. Nothing as to this trust is included in Bo's gross estate.
(True/False)
4.8/5 (80)
(80) In which, if any, of the following independent situations can the alternate valuation date be elected? Value of Gross Estate Estate Tax Result
Date of Alternate Date of Alternate
Death Date Death Date
(Multiple Choice)
5.0/5 (84)
(84) A transfer in trust in which the trustee has the power to accumulate income is not a gift of a future interest if the trustee never exercises the power.
(True/False)
4.8/5 (82)
(82) In 1985, Drew creates a trust with $1,000,000 of securities. Under the terms of the trust, Paula (Drew's wife) is granted a life estate with remainder to their children. Drew makes a QTIP election as to the trust. Drew dies in 1992 when the trust is worth $1,500,000, and Paula dies in 2011 when the trust is worth $2,000,000. Which, if any, of the following is a correct statement?
(Multiple Choice)
4.9/5 (72)
(72) The current $5 million exemption equivalent is not permanent but is scheduled to expire after 2012.
(True/False)
4.7/5 (83)
(83) The U.S. has death tax conventions (i.e., treaties) with most of the countries of the world.
(True/False)
4.9/5 (70)
(70) June made taxable gifts as follows: $400,000 in 1973, $200,000 in 1977, $600,000 in 1985, and $700,000 in 2001. In 2011, June dies leaving a taxable estate of $4,000,000. June's tax base for applying the unified tax rate schedules (for estate tax purposes) is:
(Multiple Choice)
4.9/5 (82)
(82) Iris dies intestate (i.e., without a will). All of her property passes to her heirs in accordance with the order of distribution prescribed under Federal law.
(True/False)
4.9/5 (89)
(89) Although qualified tuition plans under § 529 are treated favorably for gift tax purposes, such plans are subject to estate tax consequences upon the grantor's death.
(True/False)
4.9/5 (82)
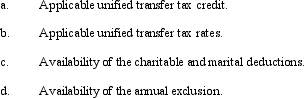
(82) The Federal gift and estate taxes were restructured in 1976 into the unified transfer tax. The objective of the change was to eliminate the tax difference between transfers during life (gift tax) and at death (estate tax). Does this uniformity of treatment currently exist? In this regard, comment on the following differences between the two taxes.
(Essay)
4.9/5 (87)
(87) Lyle and Beatrice are brother and sister. Using his funds, Lyle purchases land, listing title as: "Lyle and Beatrice, joint tenants with right of survivorship." If Lyle dies first, all of the land is included in his gross estate.
(True/False)
4.8/5 (84)
(84) To make the election to split gifts under § 2513, spouses must file a Form 709 (Federal gift tax return).
(True/False)
4.9/5 (86)
(86) In community property states, all property acquired after marriage by either spouse is community property.
(True/False)
4.9/5 (86)
(86) At one point, the tax rates applicable to transfers by gift were lower than those applying to transfers by death.
(True/False)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)