



 Chat with AI
Exam 19: Family Tax Planning

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


In satisfying the more-than-35% test of § 6166 (i.e., extended estate tax payment schedule relative to an interest in a closely held business), some prior gifts the decedent may have made must be considered.
(True/False)
4.9/5  (73)
(73) A recapture of special use valuation will not occur if a qualified heir ceases to use the property for farming purposes but does not otherwise dispose of it.
(True/False)
4.9/5 (80)
(80) A well-known artist dies and among her assets are a large number of her paintings. What approach might be taken to lower the value of her estate?
(Essay)
4.8/5 (70)
(70) Dustin owns all of the stock of Gold Corporation which includes both common and preferred shares. The preferred stock is noncumulative, has no redemption date, and possesses no liquidation preference. In 1995, Dustin makes a gift to his adult children of all of the common stock. He dies in 2011 still owning the preferred stock. The value of the Gold stock on the relevant dates is:  One of the tax consequences of this estate freeze is:
 (Multiple Choice)
4.7/5 (80)
(80) If a decedent's household goods are sold through public auction, the price received should be the valuation used for Federal estate tax purposes.
(True/False)
5.0/5 (66)
(66) Because of the estate tax deduction, a testamentary bequest to charity is preferable to a lifetime transfer.
(True/False)
4.9/5 (96)
(96) Clancy and Maureen are husband and wife and have always lived in a community property state. When Clancy learns that he is terminally ill, he gives to Maureen all of his share of the community investments that have declined in value. Why?
(Essay)
4.9/5 (77)
(77) Neither the transfer by gift or by death avoids the recognition (for income tax purposes) of any deferred interest on U.S. savings bonds.
(True/False)
4.8/5 (93)
(93) Brad and Heather are husband and wife and live in New Mexico. Under Brad's will, his share of the community property passes to the children. Upon Brad's prior death, there will be a change in Heather's income tax basis in her half of the community property.
(True/False)
4.7/5 (81)
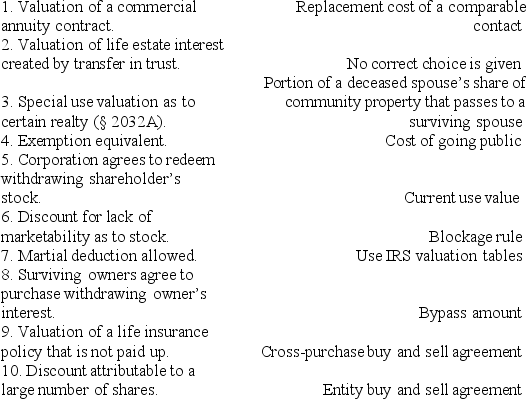
(81) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
(Essay)
4.9/5 (60)
(60) Herbert leaves one-half of his estate to his wife, Ramona, and the remainder to a qualified charity. Herbert's estate taxes would not be reduced if Ramona disclaims her interest in favor of the charity.
(True/False)
4.8/5 (72)
(72) Several years ago, Tad purchased land listing ownership as "Tad, Ellen, and Kay, equal tenants in common." In the current year, Kay dies first. None of the value of the land is included in Kay's probate estate.
(True/False)
4.9/5 (80)
(80) Ten years ago, Austin purchased a residence listing ownership as tenants by the entirety with his wife, Jean. In the current year, Austin predeceases Jean. As to the residence, nothing is included in Austin's probate estate.
(True/False)
4.8/5 (73)
(73) The special use valuation method of § 2032A is available for valuing transfers by gift.
(True/False)
4.8/5 (76)
(76) Edgar creates a trust, life estate to Connie (age 46), remainder to Gene (age 18). In determining the value of the life estate, use the multiple given in the IRS valuation table for a person age 18.
(True/False)
4.9/5 (87)
(87) Carol inherits her father's farm, and the executor of the estate properly makes a § 2032A election. Five years later, Carol sells the farm. It is determined that the election, which allowed $800,000 in value to be excluded, saved $160,000 in estate taxes. What are Carol's tax options? Tax consequences?
(Essay)
4.8/5 (72)
(72) In 1990, Gloria purchased as an investment unimproved land for $50,000. In 2011, she sells the land, now worth $200,000, to her church for $50,000. As a result of this transaction, Gloria reports:
(Multiple Choice)
4.8/5 (78)
(78) Mel's estate includes a number of notes receivable signed by his daughter, Tammy. These notes were issued by Tammy on different occasions when she obtained funds from Mel. The total face amount of these notes is $150,000. The notes are forgiven by Mel's will. How much, if any, regarding these notes should be included in Mel's gross estate?
(Essay)
4.9/5 (70)
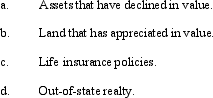
(70) In making a choice as to which assets to use in carrying out a program of lifetime giving, comment on the use of each of the following assets.
(Essay)
4.8/5 (64)
(64) Joseph makes a gift of securities (basis of $900,000; fair market value of $600,000) to his son, Earl. As a result of the transfer, Joseph paid a gift tax of $90,000. What is Earl's income tax basis in the securities if the gift occurred in 2011?
(Essay)
4.7/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)